Building a Cash Flow Analysis Worksheet Excel That Actually Works
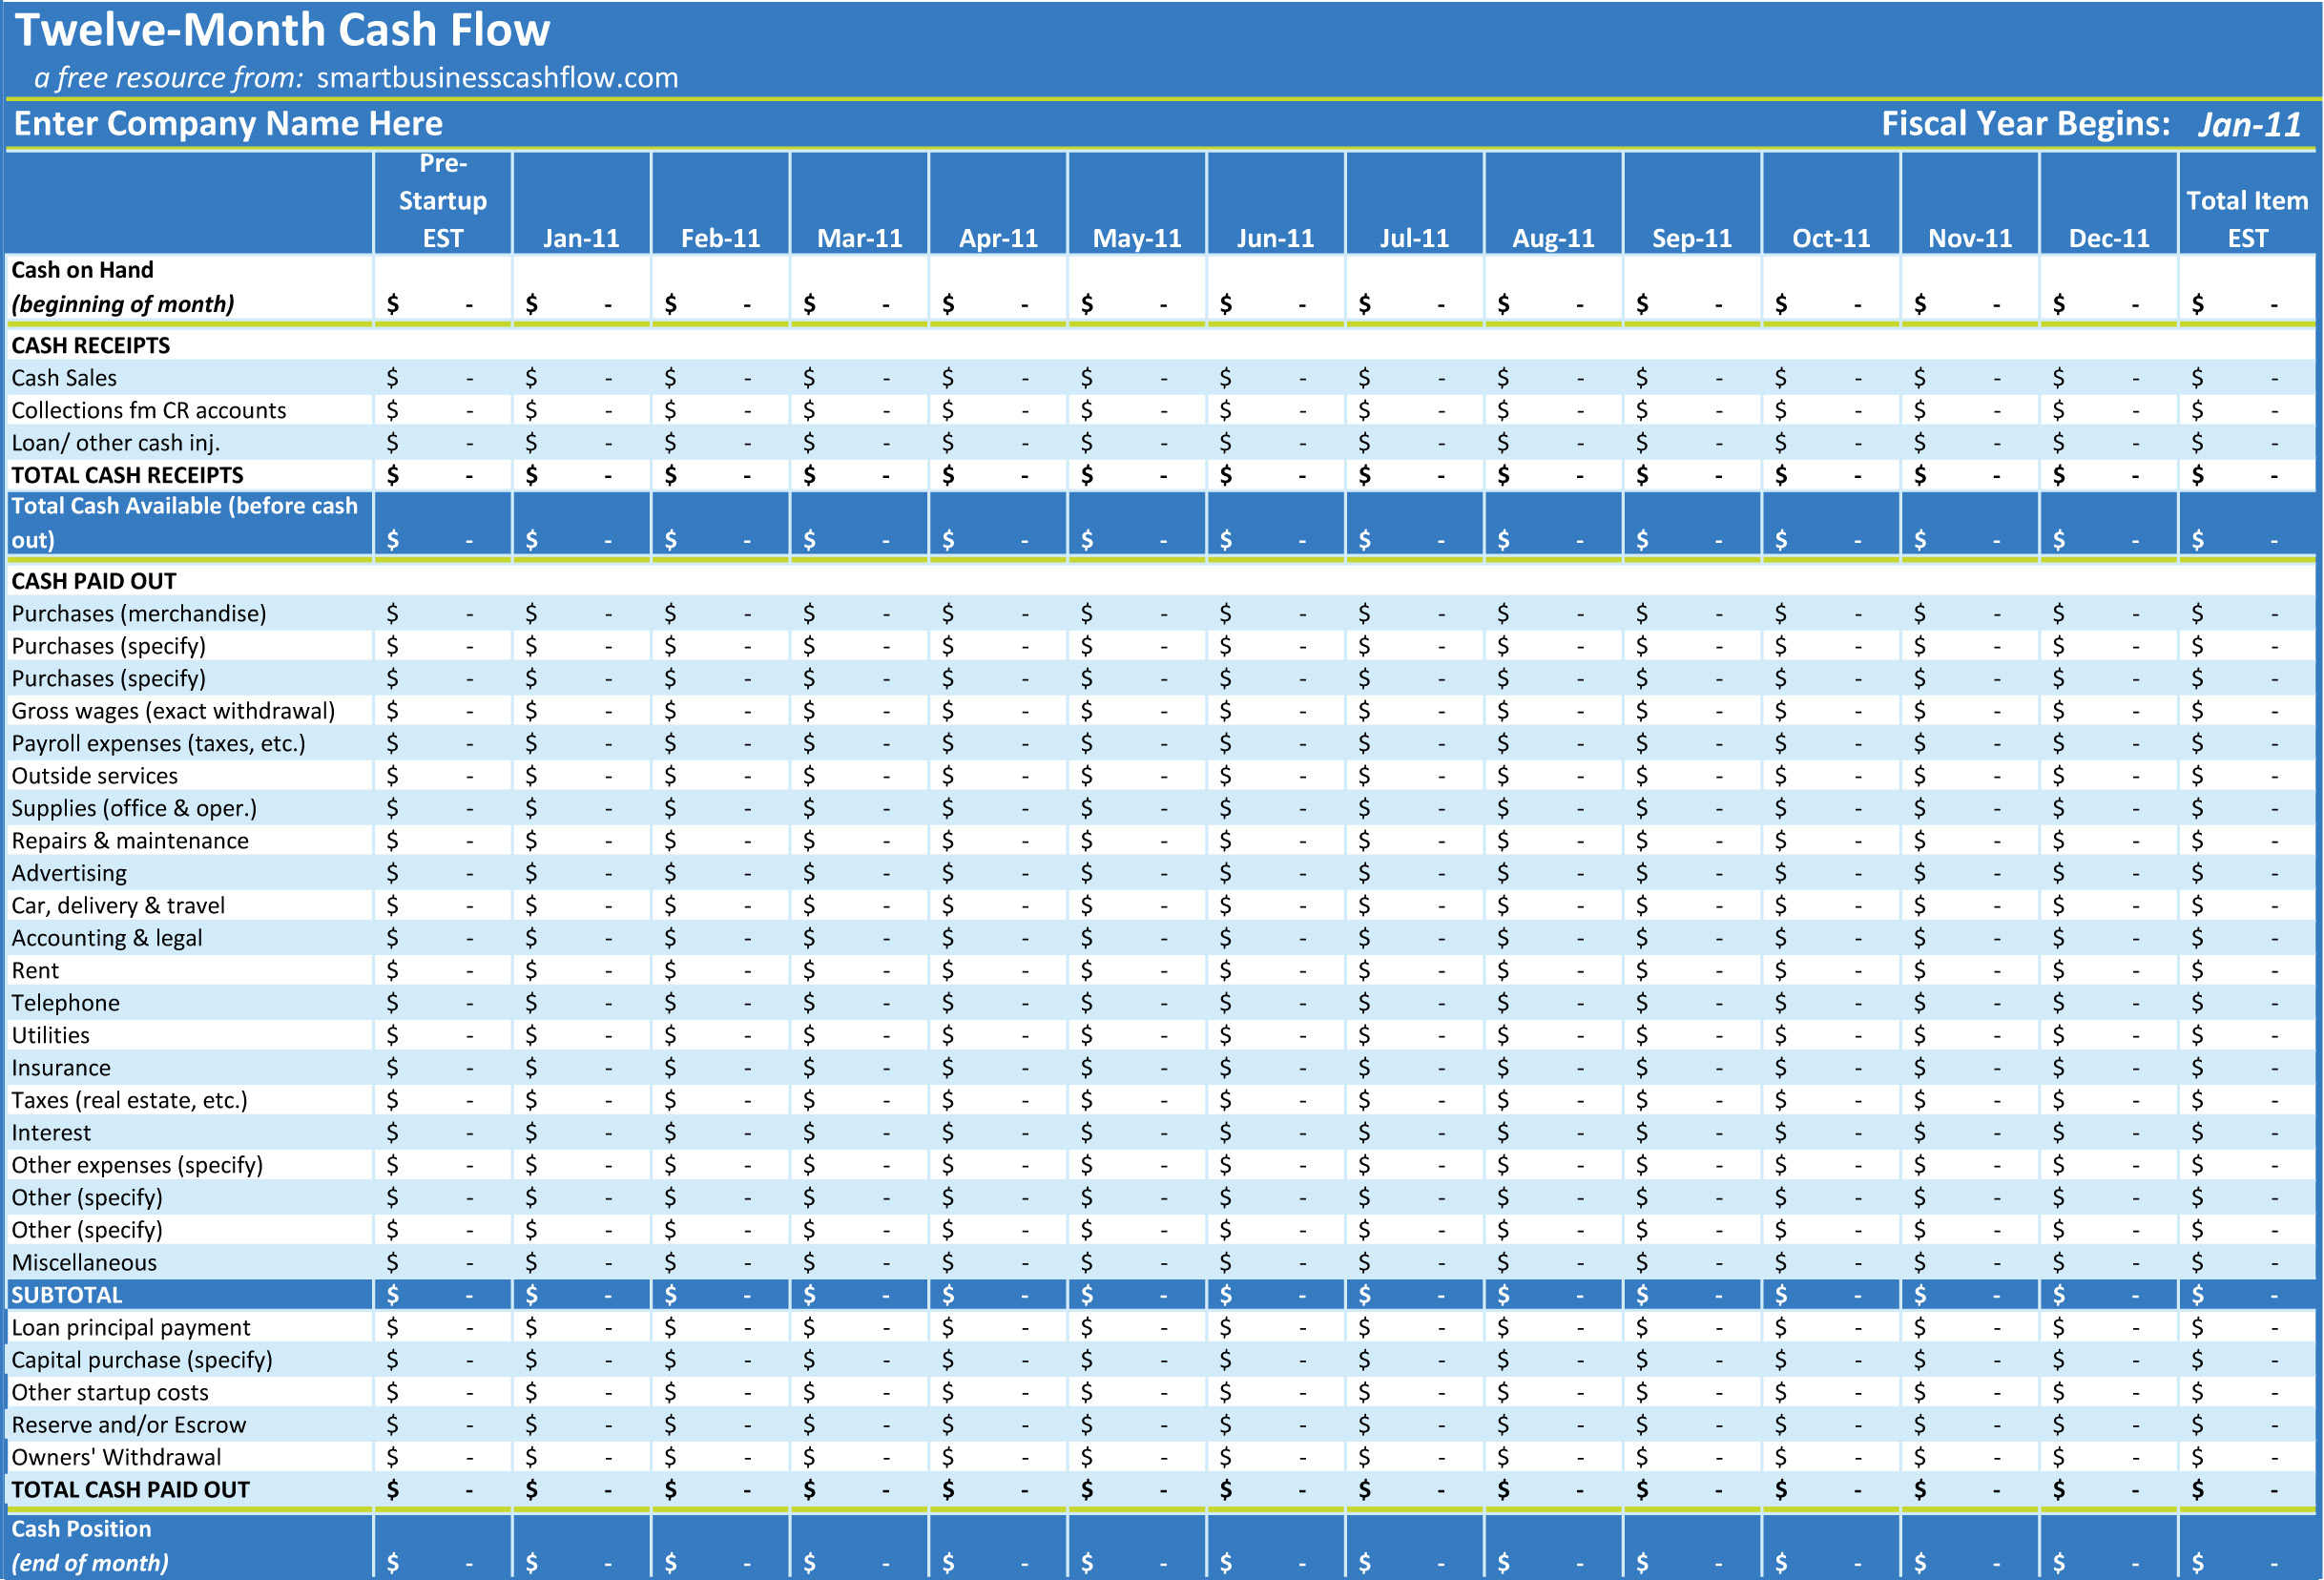
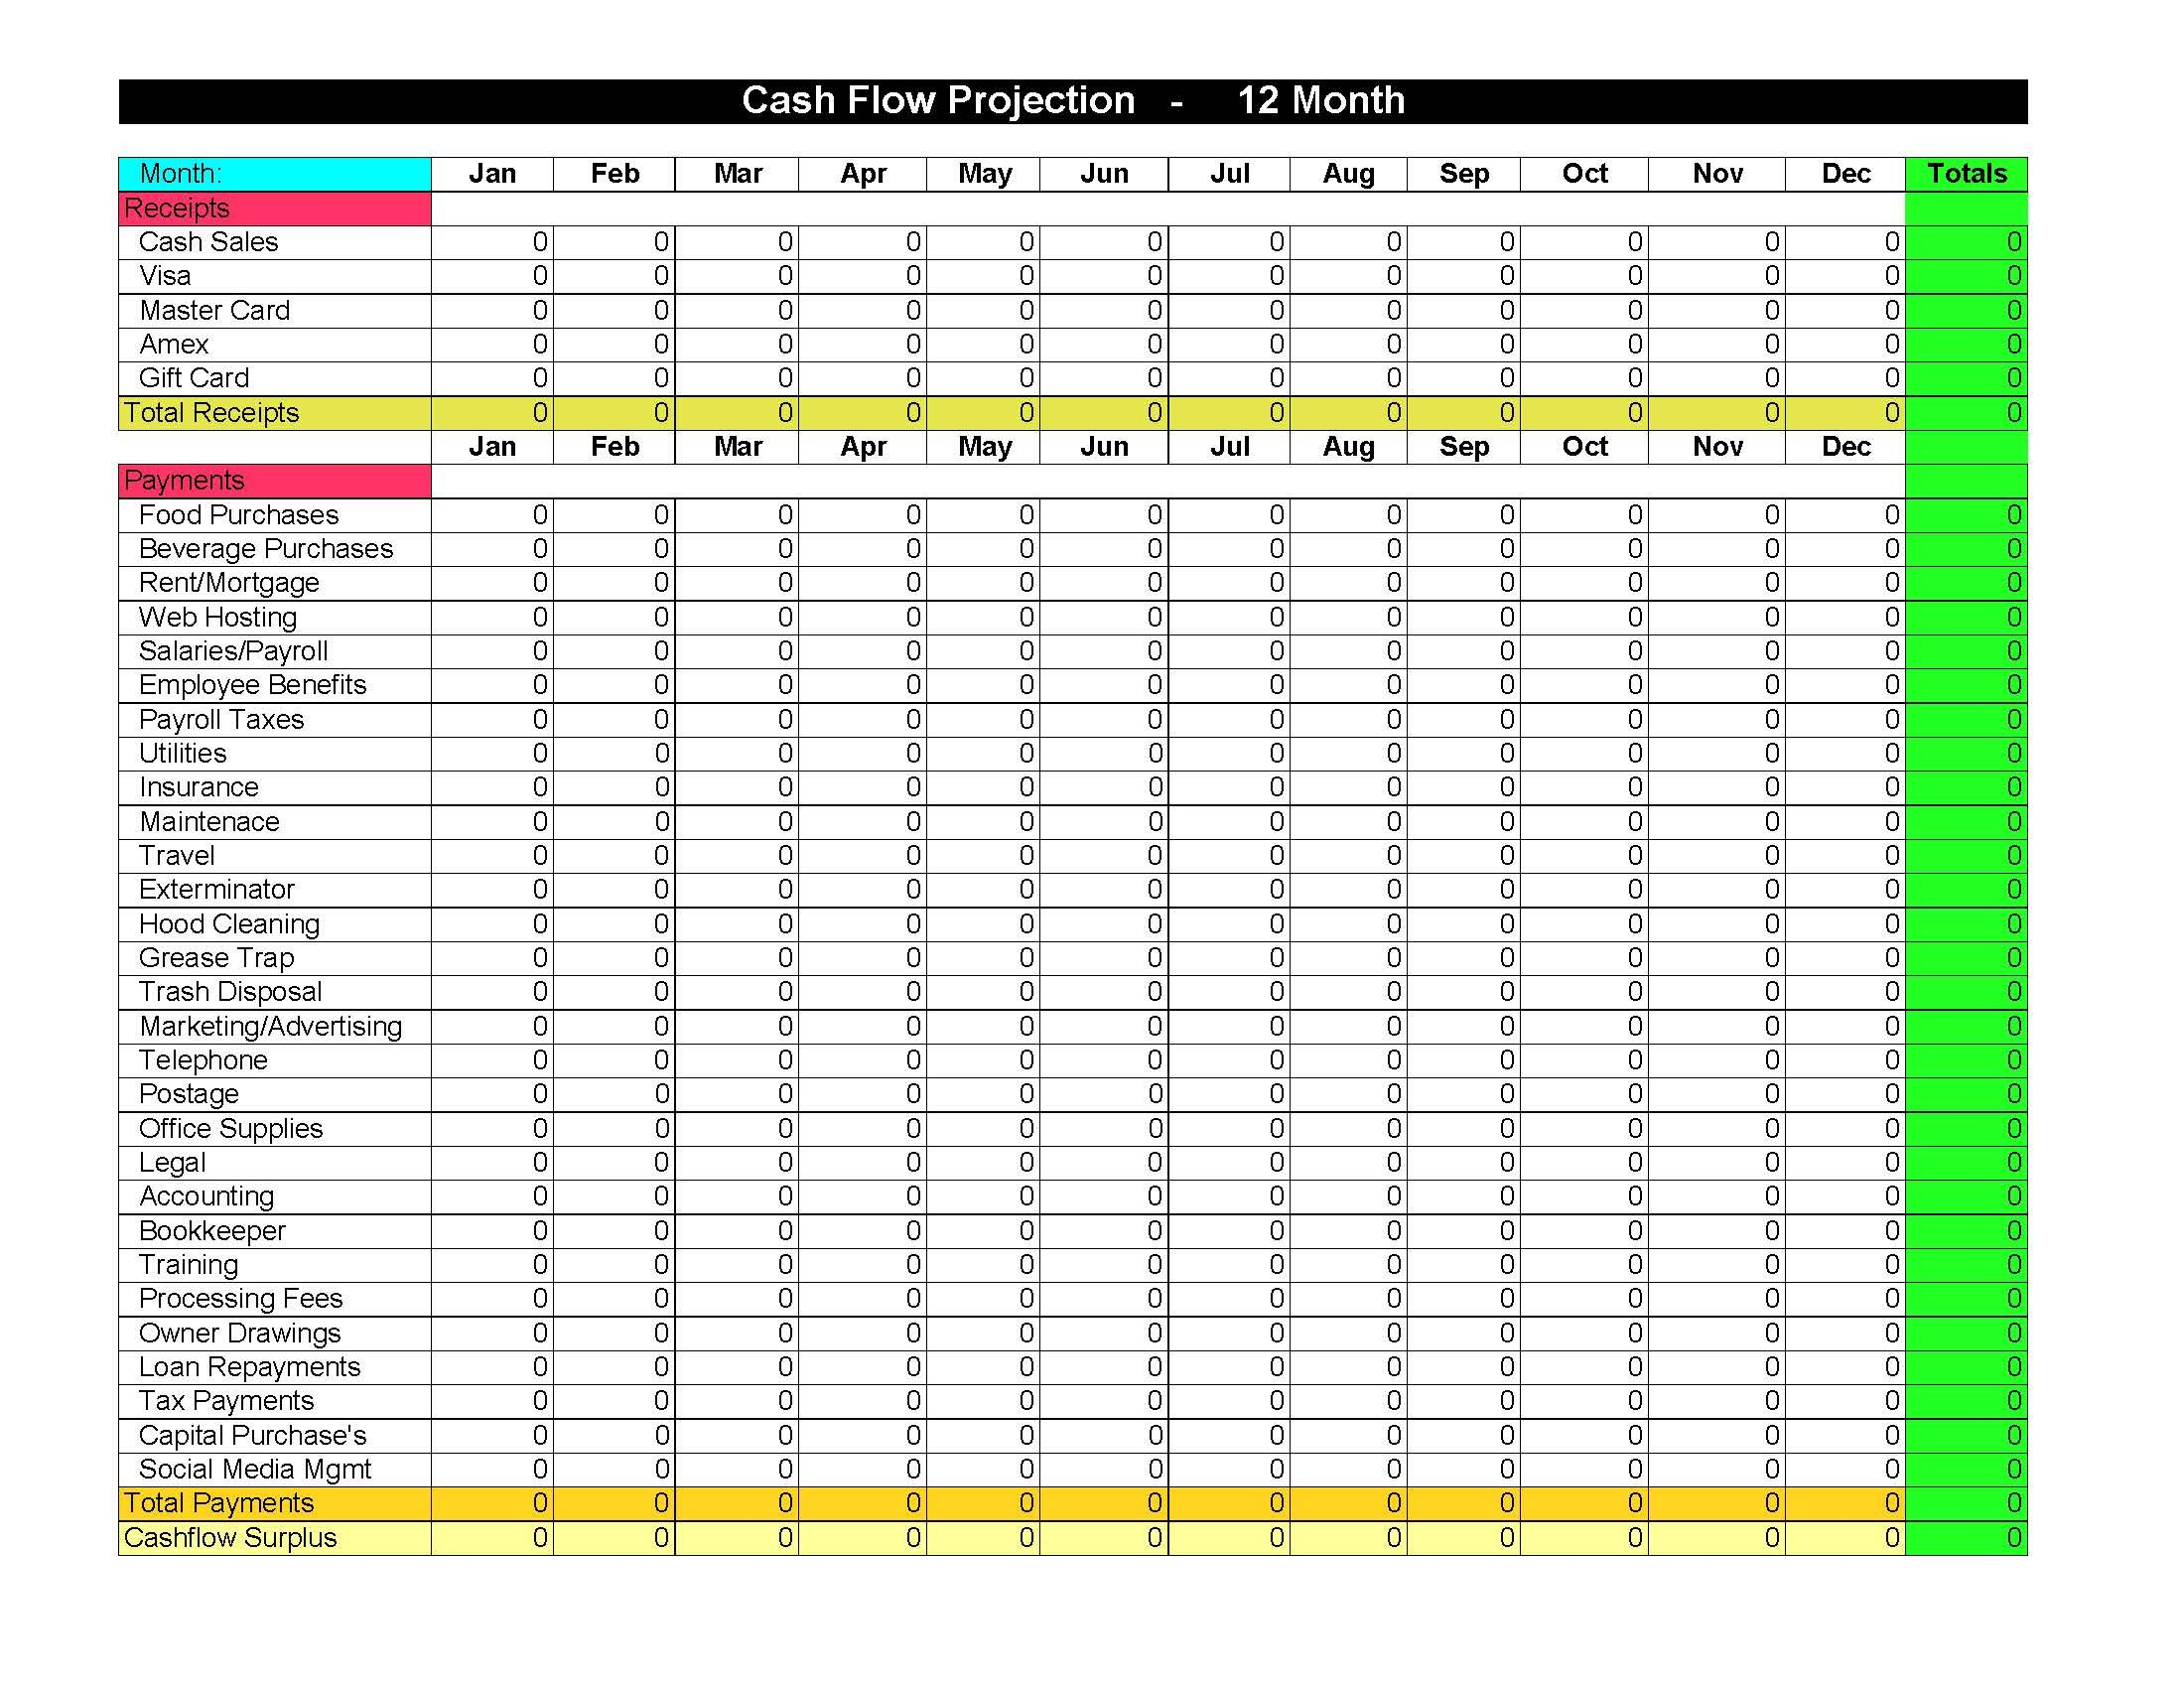
Most free cash flow templates online are built by people who've never had to reconcile one at 11pm before a board meeting. They look clean. They also fall apart the moment you feed them real data. I'm going to walk through how to build something that survives contact with actual business operations, then talk about where the whole thing breaks down. Start with a timeline. Lay out your periods across the top as columns. Monthly is standard, but if you run a seasonal business you'll want weekly for three months around your peak season and then monthly the rest of the year. Don't skip that distinction. I learned it the hard way building a template for a landscaping company that had 70 percent of its revenue between April and September. A flat monthly view made their cash position look stable when it was actually a rollercoaster. Your row structure matters more than anyone admits. Organize it in this order: beginning cash balance, operating activities, investing activities, financing activities, ending cash balance. Under operating, break it into revenue receipts, cost of goods sold, operating expenses, taxes paid, and changes in working capital. The working capital section is where most templates shortcut themselves into oblivion. Include accounts receivable, accounts payable, and inventory changes as separate line items. Do not bundle them together.
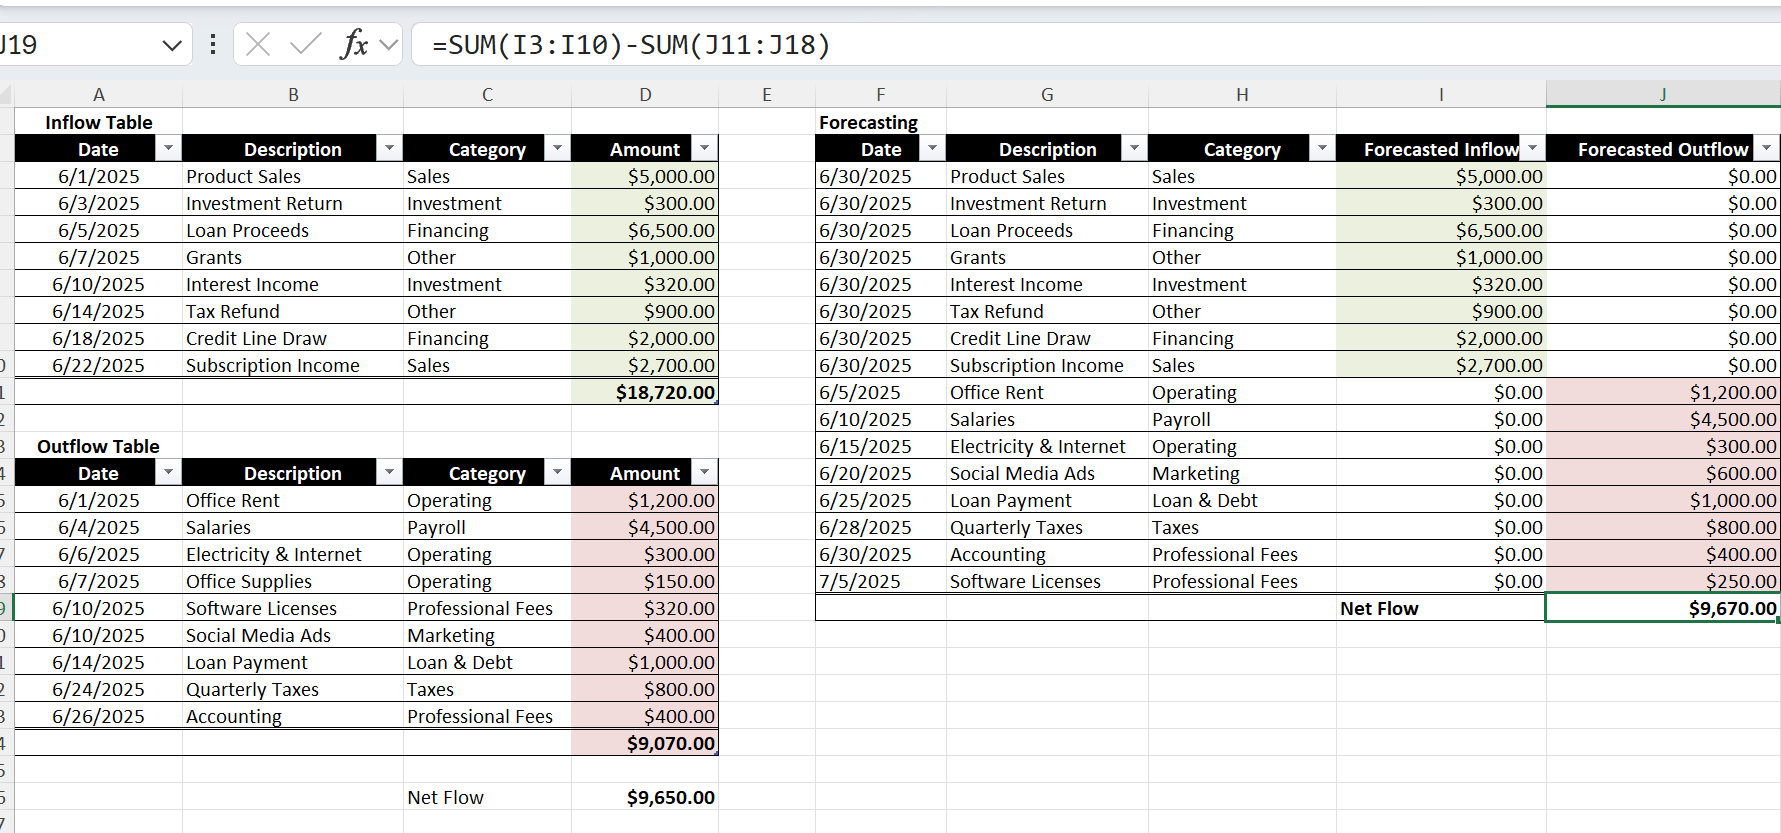
For the actual mechanics, your ending cash for one period becomes the beginning cash for the next. This linkage is non-negotiable. I've seen too many spreadsheets where each month is calculated in isolation, which means the model has no memory. That's not a cash flow model. That's a collection of unrelated summaries. Here's the formula structure I use. Beginning balance plus total operating cash flow plus total investing cash flow plus total financing cash flow equals ending balance. Each category uses SUMIF or SUMIFS pulling from your detailed transaction tables. That keeps your calculation logic separate from your data entry, which means when someone changes a number three months in, you don't have to trace it through twenty formulas to find the break. I ran into a specific problem with a manufacturing client whose cash flow model kept showing negative cash in months where they clearly had money in the bank. The issue was that their accounts receivable line was pulling from an aging report that included invoices over 90 days old, but their actual collection pattern showed those were essentially uncollectible. The model was overstating incoming cash by roughly forty thousand dollars a month. The workaround was to add a collection rate assumption to each receivable bucket rather than treating all outstanding invoices as cash inflows. I set up a separate table mapping aging buckets to historical collection percentages and referenced that with a VLOOKUP. Suddenly the model matched reality.
Where People Go Wrong
The biggest mistake is confusing accrual revenue with cash received. Your income statement says you made a sale. The bank account doesn't care. Your worksheet needs to track when money actually moves, not when invoices go out. Set up a clear separation between revenue recognition and cash collection in your data layer. A simple way is to have a transactions table that records the actual deposit date, not the invoice date. Another common error is treating debt principal payments as expenses. They're not. They're financing activities. Interest is the expense. Principal repayment is just moving money from one account to another in a structural sense. Mix them up and your operating cash flow number will be wrong, which makes your entire analysis unreliable. Seasonality adjustments are almost always handled poorly. If you have quarterly tax payments, annual insurance premiums, or bonus cycles, those need to be explicit line items in the months they actually occur. Don't smooth them across twelve months. A $12,000 insurance payment hit in March that's spread as $1,000 per month will make every month look fine and March look devastating when it actually arrives. Both are lies. Put the real number in the real month.
Get the Full Details
Advanced Nuance: The Indirect vs Direct Method Question
You'll see a lot of debate about whether to use the indirect or direct method for your Cash Flow Analysis Worksheet Excel. The indirect method starts with net income and works backward through adjustments. The direct method lists actual cash receipts and payments. For internal management use, the direct method is almost always better. It's more transparent, easier to audit, and doesn't require you to reverse-engineer your way from an accrual number. The indirect method exists primarily because external financial reporting requires it. You don't need to please an external auditor with your internal worksheet. That said, there's a practical hybrid approach that saves time. Keep your detailed direct-method transaction data for the actual cash movements, but add a reconciliation column that shows how your operating cash flow connects back to net income. This gives you both the clarity of direct tracking and the verification path of indirect reconciliation in one sheet. It catches errors that would otherwise sit undetected for quarters.
Realistic Limitations
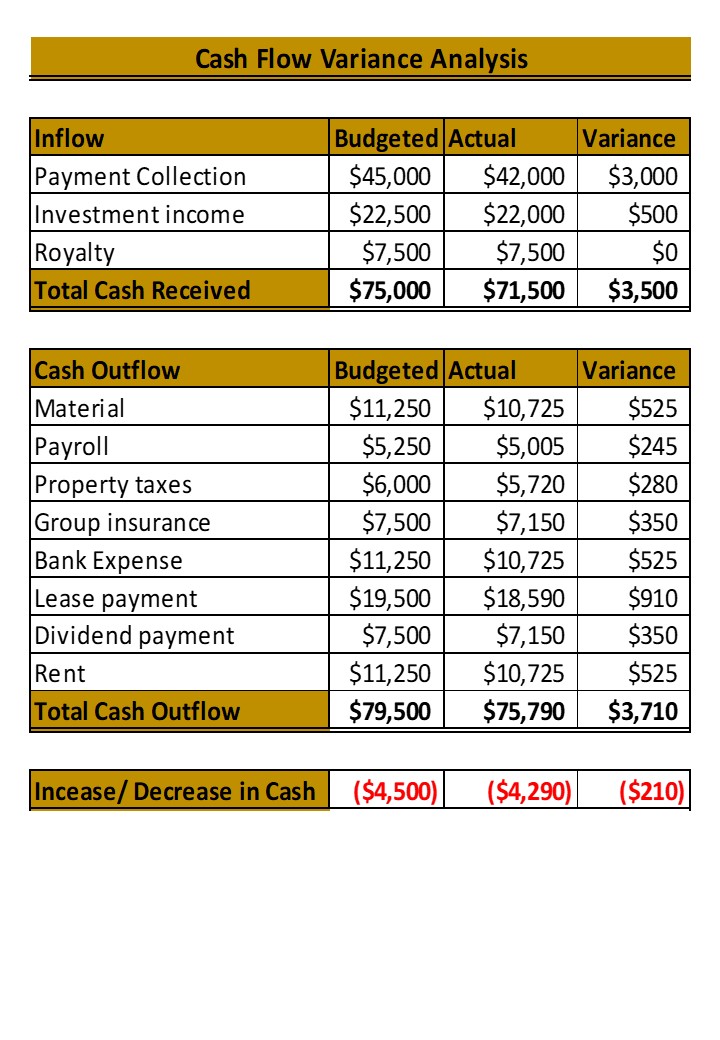
A spreadsheet-based Cash Flow Analysis Worksheet Excel will break if your transaction volume gets high. Once you're processing more than a few hundred entries per month, manual data entry becomes a liability. Excel will slow down, formulas will break, and someone will accidentally overwrite a reference. At that scale you need dedicated accounting software with automated bank feeds. No argument. The model also assumes your historical patterns continue. They won't. A cash flow worksheet is only as good as its assumptions about future collections, payments, and spending. If a major customer goes bankrupt or a supplier suddenly demands net-15 terms instead of net-60, your model doesn't know until you tell it. Build in sensitivity analysis. Add a scenario column for best case, expected, and worst case. It takes fifteen minutes to set up and prevents catastrophic surprises. There's also the human factor. Anyone can change a number in a spreadsheet. Version control is nonexistent unless you enforce it. I recommend a strict convention: keep all historical data read-only, put all assumptions in a dedicated tab with clear labeling, and lock the calculation cells. It's not foolproof but it stops the most common form of model corruption, which is someone accidentally changing a hard-coded value three months into a forecast and then wondering why the numbers don't match the previous quarter.
If you want a starting point, there are reasonably solid free templates from the major accounting software providers. But treat them as a skeleton, not a finished product. The real work is in configuring the assumptions, linking the periods correctly, and building in the error checks that prevent garbage from producing garbage with extra steps.