Getting to Grips With Cash Flow Statements
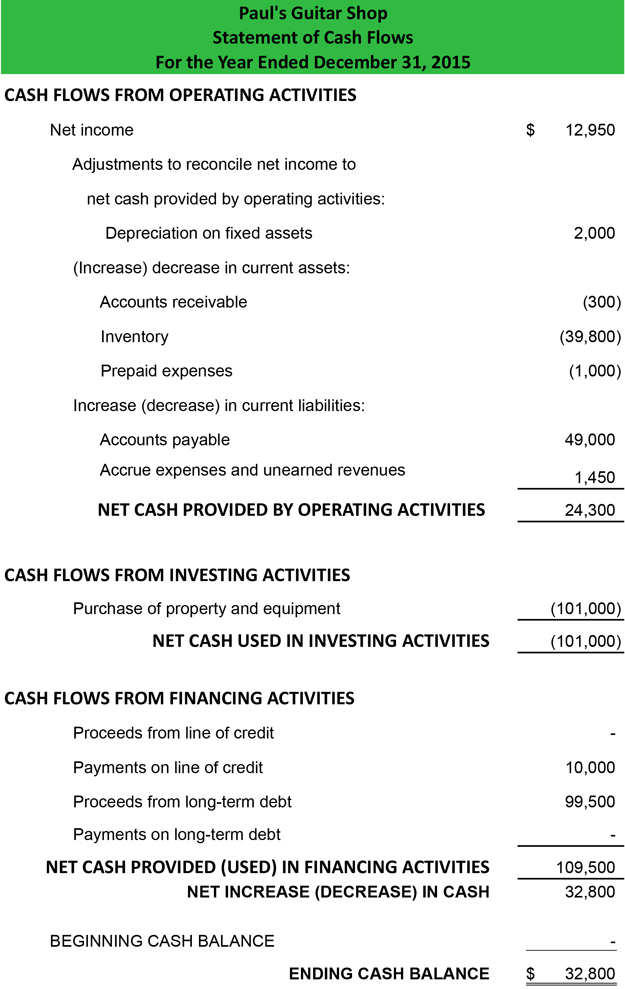
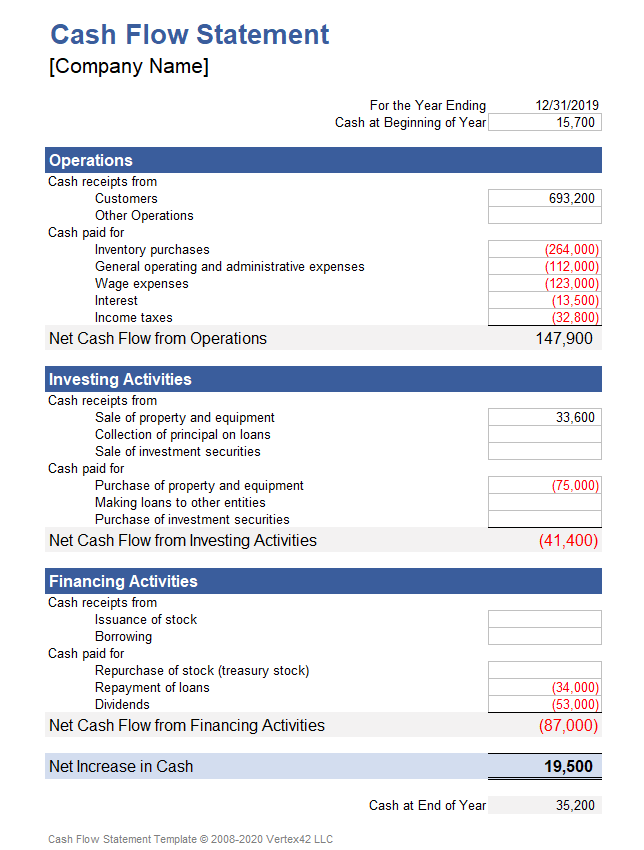
The cash flow statement tracks actual money moving in and out of a business over a set period. Most people know it has three sections — operating, investing, financing — but the real difficulty comes when you're actually building one from scratch and the numbers don't reconcile. I spent about three weeks last year trying to debug a client's operating cash flow that was consistently off by roughly $40,000. Turns out their accounts payable roll-forward was including a few non-cash accrued expense adjustments that should have been stripped out. The workaround was to pull the detailed journal entries from their sub-ledger and manually filter for anything tagged as non-cash before running the reconciliation. Here's something that doesn't come up in every course: the indirect method and direct method produce the same operating cash flow number, but they reveal completely different things about your data quality. When I train people, I always start them on the indirect method because it's easier to derive from existing general ledger data. But the indirect method hides errors. A misclassified expense can distort net income, which cascades through every adjustment line. Someone working from the direct method sees each cash receipt and payment individually, so a bad classification jumps out immediately. I recommend learning both, but if you only get one, make sure you understand how to walk backward from the indirect to the direct. The balance sheet interconnection is where things get real. Every change in a balance sheet account between two periods feeds directly into the cash flow statement. Working capital adjustments, depreciation add-backs, gains and losses on asset sales — they all sit in specific spots. Get one wrong and the whole statement won't tie to the cash balance on your balance sheet. That final number should match your actual bank and cash accounts to the penny. If it doesn't, you have a reconciliation problem, not a presentation problem.
I once had a situation where a subsidiary had currency translation adjustments flowing through other comprehensive income. Those adjustments shouldn't touch operating cash flow at all, but because they were buried in the GL without clear tagging, my initial model was pulling them into the working capital section. It took me about four hours to trace through every subsidiary's trial balance and identify which accounts had FX impacts. The fix was to build a mapping table that flagged any account with a currency-related sub-account and excluded those movements from the operating section entirely.
Building Your Own Training Model
The most effective way to learn is to build a model from real data rather than using a pre-made template. Grab any public company's financial statements — I usually recommend pulling from a company in a straightforward industry like retail or manufacturing. Start with their balance sheet and income statement, then construct the cash flow statement manually in a spreadsheet. Don't use formulas that auto-calculate everything. Type out each line item yourself so you feel the logic of each adjustment. Start with net income and work through the operating section line by line. Depreciation and amortization are straightforward add-backs since they're non-cash expenses. Stock-based compensation also gets added back — it's an expense that never touched cash. Changes in working capital are the tricky part. An increase in accounts receivable means you booked revenue but haven't collected cash yet, so you subtract it. A decrease in inventory means you sold off stock without buying new stuff, so you add it back. These relationships seem simple until you deal with a company that has multiple inventory types or unusual receivable structures. For investing activities, look at capital expenditures, acquisitions, and asset sales. The cash flow statement shows the actual cash paid or received, not the book value. If a company sells a machine that originally cost $50,000 with $30,000 in accumulated depreciation for $25,000 cash, you record $25,000 as an inflow. The $5,000 gain shows up in the operating section as a subtraction because it's included in net income but isn't an operating cash item.
Get the Full Details
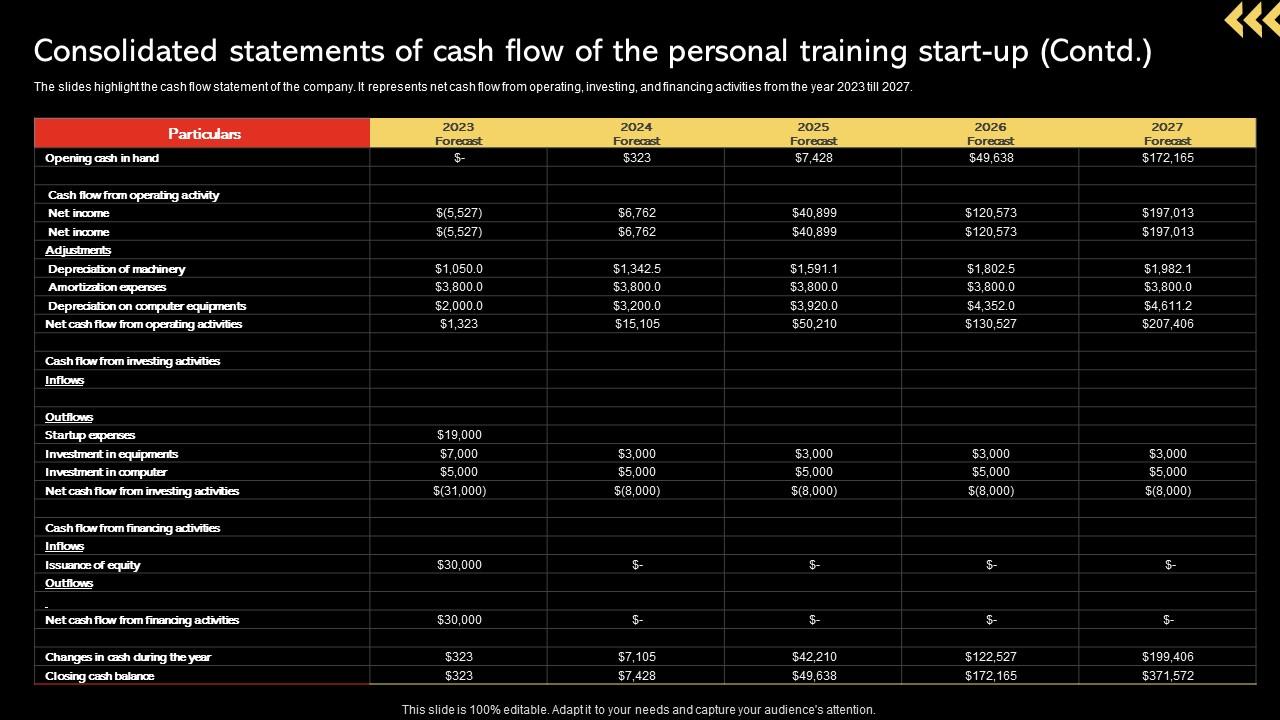
Financing activities cover debt issuances and repayments, equity transactions, and dividends. This section is usually the cleanest because these transactions are fairly explicit in the GL. But watch out for debt issuance costs that get amortized — those non-cash portions need to be removed from the operating section just like depreciation.
Pitfalls That Will Waste Your Time
One common mistake is confusing cash flow with profitability. A company can be profitable and still run out of cash. I've seen this happen with fast-growing businesses that expand inventory and receivables faster than their cash can support. The training exercise here is to take a profitable company and show exactly where cash is getting consumed. Usually it's working capital expansion or heavy capex that isn't showing up on the income statement yet. Another issue is the treatment of interest and taxes. Interest paid can appear in operating or financing depending on your accounting policy and jurisdiction. Tax payments are operating cash outflows, but deferred tax assets and liabilities create adjustments that aren't obvious. If a company has a large deferred tax liability increasing during the period, that's a non-cash expense that reduces the cash tax paid relative to the income tax expense on the P&L. You need to adjust for it in the operating section. Consolidation is where things get complicated fast. When you're training on a multi-subsidiary group, intercompany transactions can distort every section. Intercompany receivables and payables shouldn't appear in the consolidated cash flow statement, but they'll show up in individual subsidiary ledgers. You have to eliminate them before building the consolidated view. I once had a model where intercompany dividends were double-counted — once as a financing outflow in the parent and again as an operating inflow in the subsidiary. The fix was a complete elimination schedule that mapped every intercompany account and flagged its treatment in each section.
There's also the issue of segment reporting. Some companies report cash flow by segment while others don't. If you're trying to reconcile a segment-level view to the consolidated statement, missing data can make it impossible. In those cases, you have to work from the consolidated numbers and back into what you can estimate. Don't pretend you have precision where you don't.
Practical Steps for Self-Directed Training
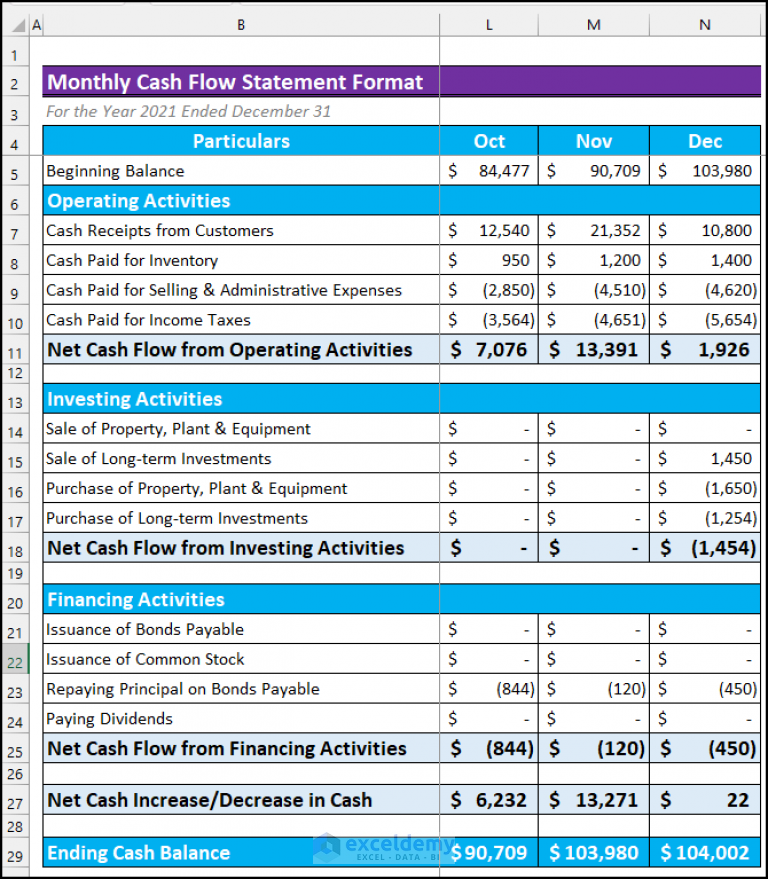
Start by studying at least five complete cash flow statements from different industries. Notice how a SaaS company's operating cash flow looks nothing like a manufacturer's. SaaS companies often have negative working capital adjustments because they collect subscription revenue upfront. Manufacturers deal with large inventory swings. The patterns matter more than the individual numbers. Then build your own spreadsheet model with dummy data. Make it self-checking by having the ending cash balance match across the cash flow statement and the balance sheet. If they don't match, your model has an error. This forces you to catch mistakes early instead of discovering them hours later when you're trying to present the statement to someone else. Use Excel or Google Sheets. Learn to structure your work so that source data sits on one sheet and the cash flow statement pulls from it using references. That way, when you change a number in the source, everything recalculates. Build in a reconciliation cell that shows the difference between your cash flow ending balance and the balance sheet cash balance. Make it turn red if there's a discrepancy. I use conditional formatting for this — it saves time when you're going through dozens of line items and need to spot errors quickly.
Find real financial data to practice with. SEC filings are free through EDGAR. Look at 10-Ks and 10-Qs from companies you find interesting. Try to reconstruct their cash flow statements from their balance sheets and income statements without looking at their reported cash flow statement first. Then compare your version to theirs. The differences will teach you more than any tutorial.
When the Standard Approach Breaks Down
Sometimes you'll encounter situations where the cash flow statement is genuinely misleading. Stock-based compensation adjustments are one example — adding it back makes operating cash flow look healthier than the underlying business generates. For companies with heavy equity compensation, the adjusted operating cash flow after removing SBC can be dramatically lower than the reported number. I've seen this differ by over 30 percent in tech companies. Another case is lease accounting under ASC 842 and IFRS 16. Right-of-use assets create depreciation and interest components that complicate the cash flow classification. The cash rent payment is a financing or operating outflow depending on the lease structure, but the depreciation and interest portions are non-cash adjustments. This gets messy quickly, especially for companies with large portfolios of mixed lease types. If your training involves modern accounting standards, make sure you understand how lease cash flows are presented under the new rules. Foreign operations add another layer. Exchange rate fluctuations can cause cash balance changes that don't correspond to any operating, investing, or financing activity. These go in a separate section called "effect of exchange rate changes on cash" and they're easy to miss if you're not looking for them. I usually recommend adding a reconciliation schedule that traces the beginning cash balance through each section to the ending balance, including the FX effect as a catch-all for any unexplained variance.

The biggest limitation of cash flow statement analysis is that it's backward-looking. It tells you what happened, not what will happen. A company can have strong operating cash flow today while carrying significant off-balance-sheet obligations or facing imminent revenue decline. Cash flow statements should be read alongside the balance sheet and income statement, and always with an eye toward what's changing from period to period. Trends matter more than any single quarter's number.