Why your cash flow reconciliation keeps breaking at 4pm on Friday
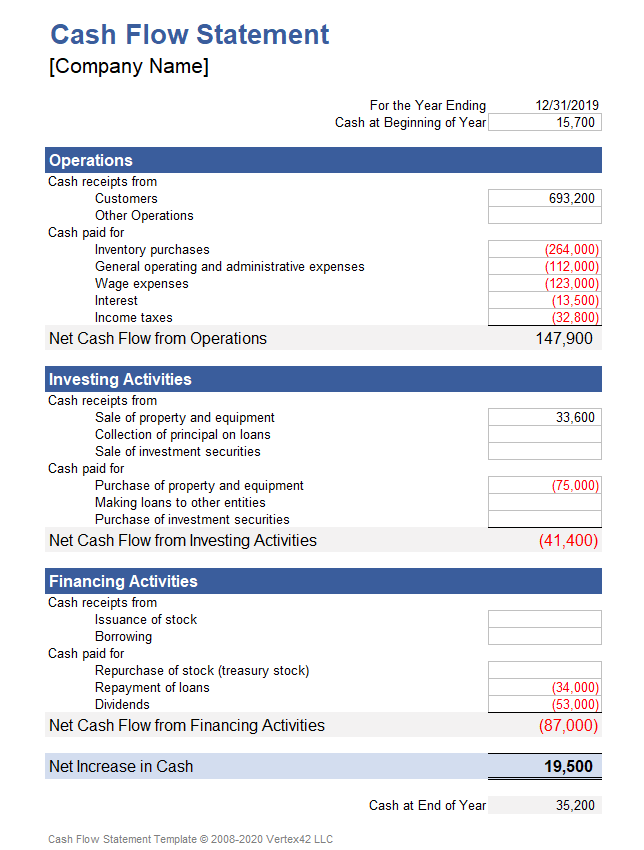
A cash flow statement worksheet is just a structured layout that helps you move from general ledger balances to the three sections of the indirect-method cash flow statement: operating, investing, and financing. It is not a fancy automated report generator. It is a working document, usually in Excel, that forces you to prove where every dollar came from and where it went before it ever touches a final filing or board deck. I built my first one in 2009 on a spreadsheet so wide it required two monitors. The version I use now still looks like that. It has been through twelve fiscal years, four audits, and one panic at 11:47pm on tax day when I realized the worksheet balance didn't match the bank statement by nine hundred dollars because a vendor rebate had been credited directly to the wrong sub-account.
Building a Cash Flow Statement Worksheet from scratch
Start with a clean trial balance. Export it from your accounting system as of each quarter end, plus year end. Do not pull live dashboard numbers. Pull the GL detail. Something like a General Ledger report with account numbers, debit columns, credit columns, and running balances, exported to CSV. Set up five main columns in your worksheet. Column A holds the account number. Column B is the account name. Column C is the Q1 ending balance. Column D is the Q2 ending balance. Column E becomes your calculated change. Columns F through H are reserved for the three cash flow sections. You will fill them out in a specific order, not alphabetically. Map every non-cash account first. These are the accounts that sit on the balance sheet but never touch cash directly. Depreciation and amortization live here. Accumulated depreciation sits opposite the asset cost. Stock-based compensation belongs here even if your company barely issues options. Changes in prepaid expenses go here. Accrued liabilities go here. The trick is recognizing that these accounts cause the gap between net income and actual cash movement, and the worksheet exists to bridge that gap.
Next, handle the working capital accounts. Accounts receivable, inventory, accounts payable, and any other short-term operational balances. When AR goes up, cash goes down. When AP goes up, cash stays put longer than it would have otherwise. Write this logic down in a small legend somewhere on the sheet. Your future self, or the auditor who shows up unannounced, will thank you. The investing section is straightforward if your company does not acquire other businesses quarterly. Equipment purchases, vehicle acquisitions, leasehold improvements, and proceeds from asset sales. Pull the fixed asset register. Match the additions against your capital expenditure approval logs. If the numbers do not align, dig into the journal entries until they do. I once found a $34,000 piece of machinery recorded as an expense rather than a capital asset because the AP clerk selected the wrong GL code. It took me three hours to reverse the entry, adjust the depreciation schedule, and update the worksheet. Worth it in the end. The financing section captures debt draws, debt repayments, equity issuances, dividend payments, and treasury stock transactions. Pull your loan schedules. Pull your shareholder ledger. Cross-reference every interest payment against the amortization table. If your company has a revolving line of credit, track the draw and repayment dates carefully. The timing matters more than people realize. A $200,000 draw in March and a $200,000 paydown in April still produces a net zero change for the quarter, but the intermediate cash position affects your liquidity reporting.
Get the Full Details

Once all sections are populated, verify the worksheet against the actual cash balance. Start with your beginning cash balance. Add the operating cash flow. Add the investing cash flow. Add the financing cash flow. The result must equal your ending cash balance per the balance sheet. If it does not, you have an unclassified transaction, a misposted journal entry, or a data extraction error. Find it. This step usually takes longer than filling out the sections themselves.
The parts that nobody tells you about upfront
One thing that trips people up constantly is the treatment of leased assets under ASC 842. Right-of-use assets and lease liabilities created massive headaches for my last few annual worksheets. The depreciation on the ROU asset goes into operating activities as a non-cash add-back. The principal portion of the lease payment goes into financing. The interest portion goes back into operating activities. Getting these split correctly required pulling the lease amortization schedule line by line, not just glancing at the total monthly payment. I learned this the hard way during a 2023 audit when the reviewer flagged a two-hundred-thousand-dollar discrepancy between my worksheet and the required footnote disclosure. Another counter-intuitive point: gains and losses on asset sales do not belong in the operating section as adjustments to net income unless they are part of your regular business operations. A manufacturing company selling off an old forklift is not conducting ordinary operations. The gain or loss goes into operating activities as a reversal, and the full proceeds go into investing. People routinely double-count this. They adjust net income for the gain and then also record the proceeds incorrectly, which inflates the operating cash flow and understates the investing cash flow by the same amount. The worksheet format itself can become a liability if you treat it as permanent documentation. I have seen finance teams spend three days perfecting the formatting, conditional formatting, color coding, and dynamic charts, only to throw the whole thing away when a new quarter introduces a different revenue recognition pattern. Build the skeleton cleanly. Use named ranges and consistent references. Keep the layout stable enough to survive a restructure but simple enough that you can rebuild the body in an afternoon if needed. The structure should support the data, not the other way around.
Where the Cash Flow Statement Worksheet fails and what to do instead
Spreadsheets fail when you have recurring transactions that do not map cleanly to a single GL account. Subscription revenue with embedded financing components, multi-element arrangements, or revenue recognized over time against cash collected in advance all create mismatches that a standard worksheet cannot resolve without becoming a monster. When those situations appear, you either expand the worksheet with additional reconciliation schedules or move to a dedicated financial reporting module. One client of mine switched to a cloud-based reporting tool after the quarterly close kept consuming five days because the worksheet required manual entries for twenty different intercompany transactions. The tool cost more, but it cut the close cycle to two days. Another failure mode is currency translation. If your company operates in multiple currencies, the worksheet must account for translation adjustments separately from actual cash movements. Mixing these two creates phantom gains and losses that distort the operating section entirely. I learned to maintain a parallel schedule for cumulative translation adjustments and link it to the worksheet only in the final reconciliation step. It adds a layer of complexity but prevents the kind of error that makes auditors ask uncomfortable questions. If you want something you can start with today, build the five-column structure I described, populate it with your last three quarters of data, and verify the ending cash balance. The moment you get that verification working, you have a functional Cash Flow Statement Worksheet. Everything after that is refinement. You can add pivot tables, dynamic charts, variance analysis, and whatever else looks impressive in a meeting. The core value is the verification step, and that does not require much more than patience and a willingness to read every journal entry that touches the cash accounts during the period.