What a Cash To Close Calculator Actually Does
Most people stare at the settlement statement and wonder where the money went. The Closing Disclosure shows line items you've never seen before—title insurance premium, lender's appraisal fee, recording charges, prepaids. Trying to add those up on a spreadsheet is a recipe for show-up surprises. A Cash To Close Calculator takes all of those figures and gives you one number: how much cash you need to wire or bring as a certified check on closing day. Start by gathering your purchase contract price, your loan amount, your estimated closing costs, and any credits the seller is offering. Most calculators ask for these inputs upfront. Fill in the fields in the order they appear. Don't skip the prepaid section—property taxes and homeowner's insurance are where people lose track. Then hit calculate. Here's what happens next. The calculator pulls your loan amount from your purchase price minus your down payment. It adds closing cost estimates, subtracts any seller concessions, then adds or subtracts proration adjustments. The result is your Cash To Close. Some tools also let you toggle between estimated and actual figures so you can see how your number shifts as real quotes come in.
I ran into a case last year where a client's Cash To Close Calculator output was $8,400 short of what they actually needed. The deal looked clean on the surface—standard 5% down, conventional loan, no obvious red flags. The problem was that the property tax proration was calculated using the prior year's assessed value, not the current year's bill, which came in 22% higher due to a reassessment. The calculator defaulted to the older figure. We caught it by pulling the current tax bill before the appraisal and manually adjusting the proration field. It was the first time I'd seen that specific bug in a widely used free calculator online. Since then I always verify the tax proration line against the most recent bill, not the assessment notice.
What Goes Into the Calculation
The core formula is straightforward, but the line items are where things get messy. Here's the breakdown most calculators use: Most free calculators omit the escrow deposit requirement entirely or lump it into closing costs without labeling it. That's a gap you need to account for manually if you're relying on a basic tool. Lender-approved calculators usually get this right because they pull from actual loan program guidelines. Say you're buying a $350,000 home with a 10% down payment on a conventional loan. Your calculator input looks like this: purchase price $350,000, down payment $35,000, loan amount $315,000. Estimated closing costs come to $6,200 based on local lender averages. Prepaids total $2,800 including three months of property taxes and six months of insurance. The seller is offering $3,000 in concessions. Escrow deposits run $1,400.
Get the Full Details
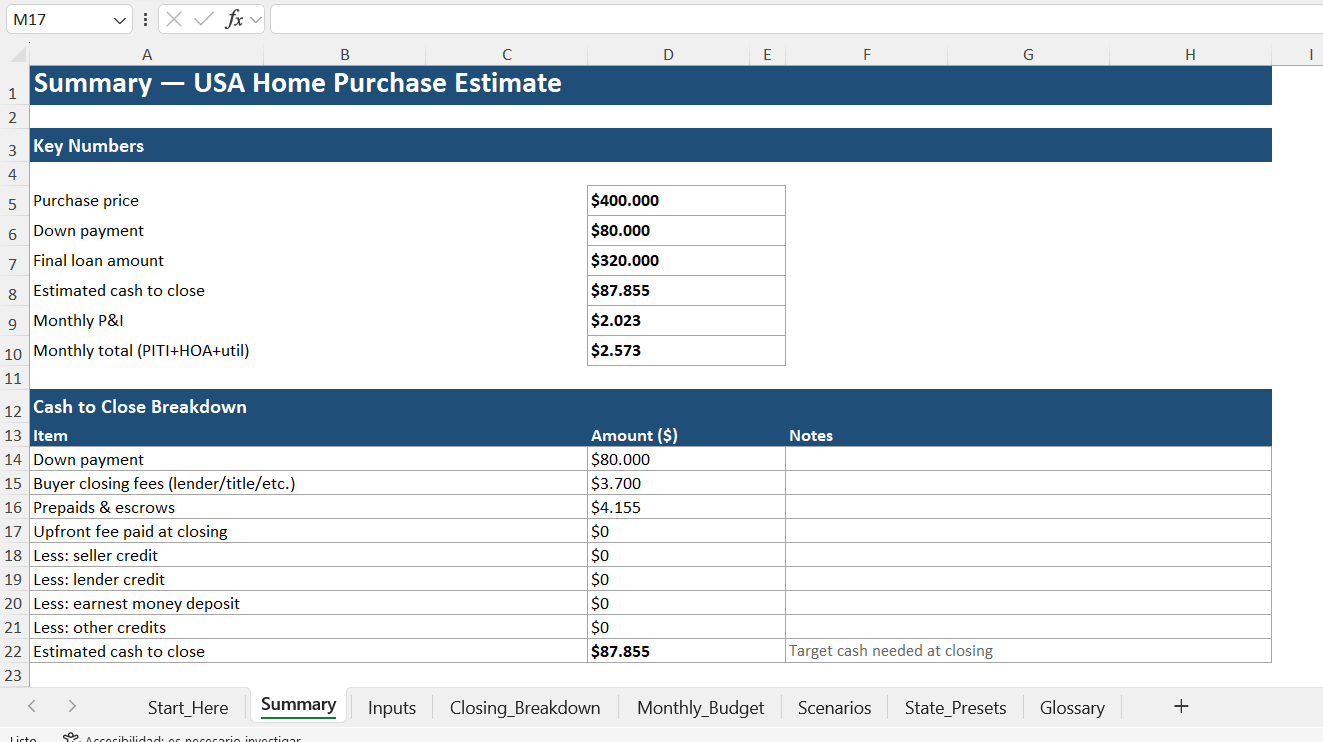
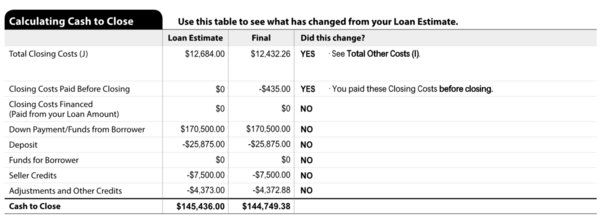
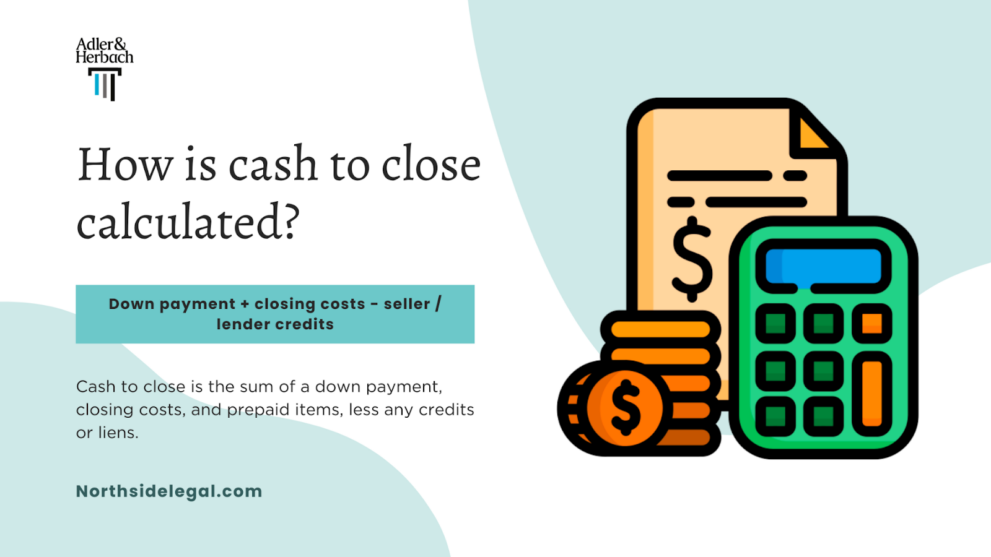
Plug those numbers in and the Cash To Close Calculator outputs $38,400. That $38,400 is your down payment plus closing costs minus seller credits plus prepaids plus escrow. Simple arithmetic, but only because someone already did the bookkeeping. Without the calculator you'd be cross-referencing the purchase contract, the Loan Estimate, the Closing Disclosure, and whatever tax bill you could find online. That walkthrough is the ideal case. Real transactions usually involve variables that throw the numbers off. A rate lock extension fee of $500 that wasn't in the original estimate. A home warranty the lender requires but the contract doesn't mention. AHOA transfer fee of $250 that only appears on the final statement. These are the kinds of things that make your Cash To Close jump by a few hundred dollars between the Loan Estimate and the actual Closing Disclosure.
Pitfalls That Trip People Up
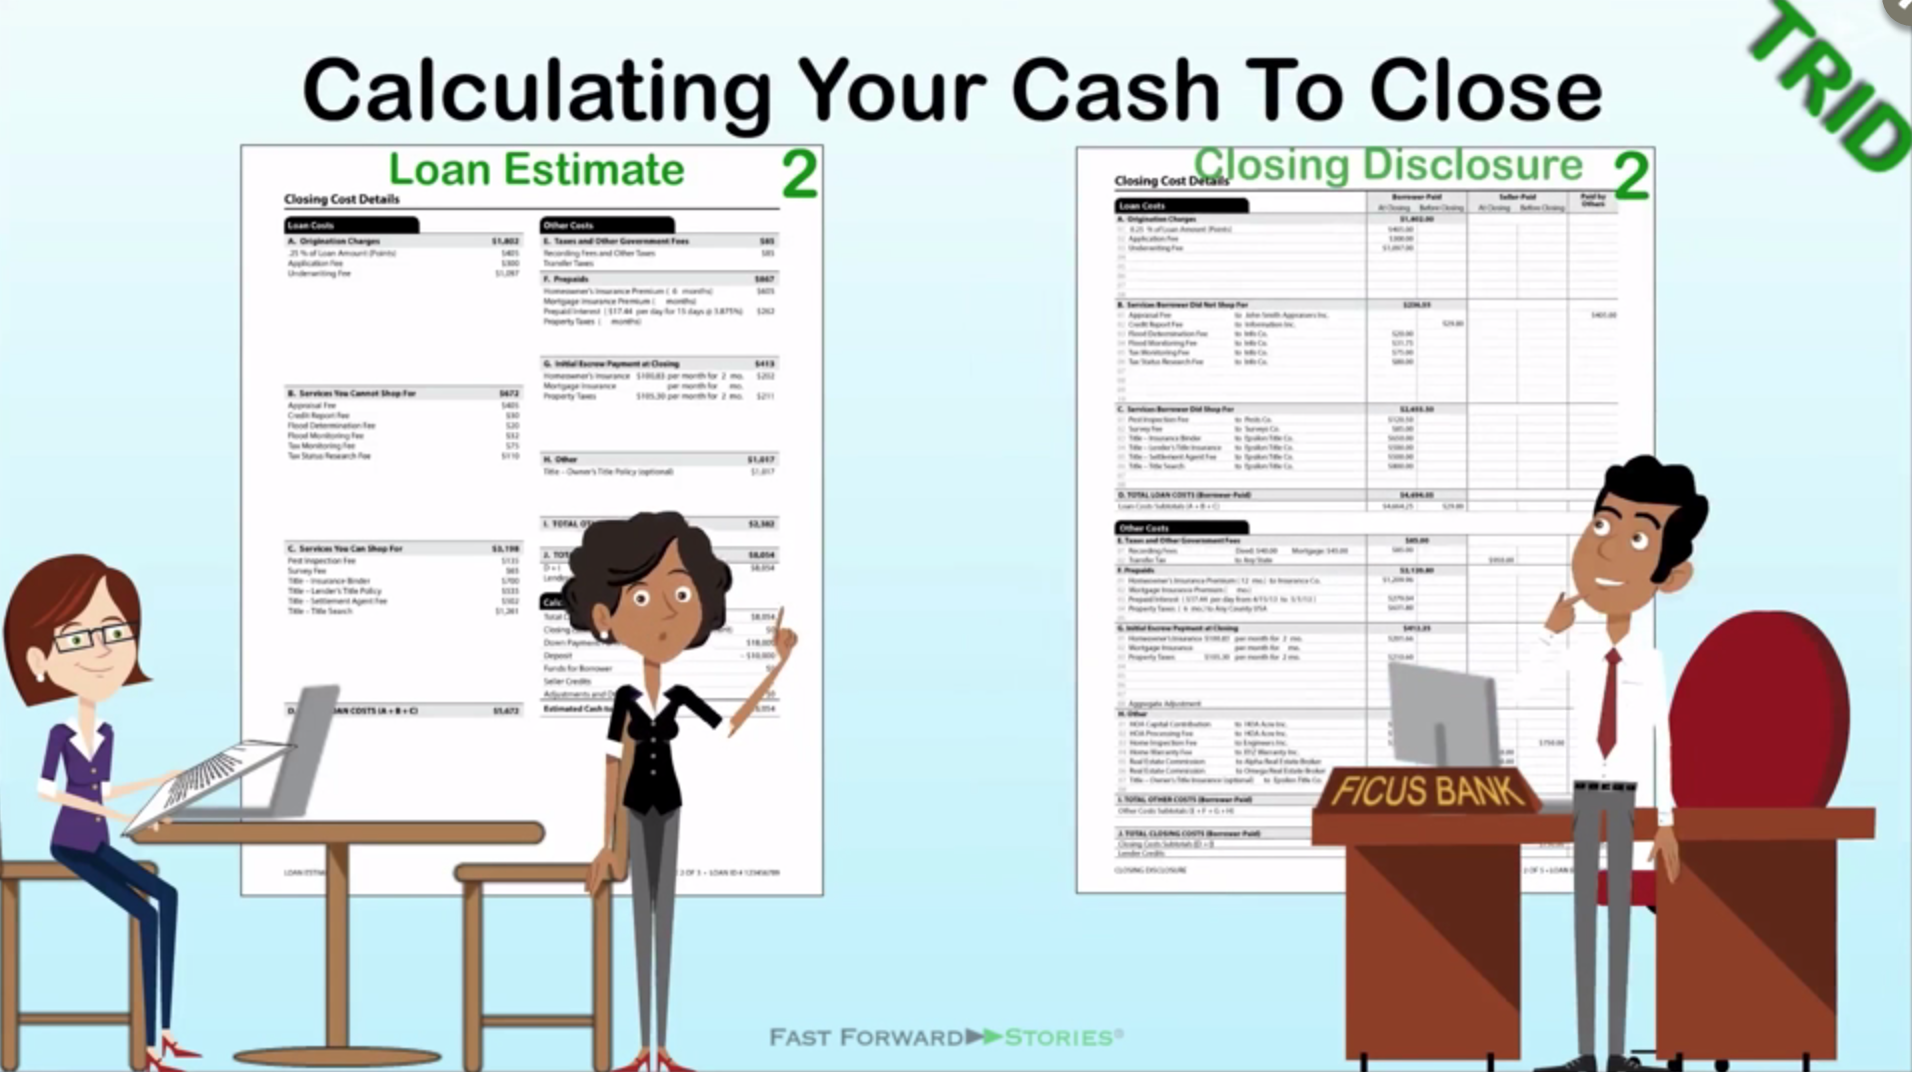
The biggest mistake I see is treating the Cash To Close number as final when it's really a snapshot. The Loan Estimate and the Closing Disclosure can differ significantly, especially on closing costs which are permitted to vary within certain tolerance bands under TRID rules. Originator charges can't increase at all, but third-party services can go up by 10% without triggering a revised disclosure. That means your calculated cash needs can shift without warning. Another common error is double-counting escrow deposits. Some calculators include escrow inside the closing cost total and then add it again in the prepaid section. The result is an inflated Cash To Close that makes you think you need more money than you actually do. Check your calculator's output against a sample Closing Disclosure to verify there's no overlap. There's also the wire fraud angle. Once you know your Cash To Close number, write it down and confirm the wiring instructions directly with your title company or settlement agent by phone, not by email. I've seen deals derailed because a buyer wired the full amount to a fraudulent account that looked identical to the legitimate one. The calculator doesn't protect you from that, but being aware of it at least keeps you from being blindsided.
When a Cash To Close Calculator Falls Short
Free online tools are fine for rough estimates, but they break down when your transaction has unusual terms. Cash-to-close calculators don't handle jumbo loans with different escrow requirements, FHA loans with MIP upfront payments, VA loans with funding fees, or reverse mortgages. They also struggle with seller-paid interest buydowns, which reduce your monthly payment but don't always adjust the cash needed at closing in the way buyers expect. If your situation involves any of those products, skip the generic calculator and use the one provided by your lender or settlement agent. Those tools are built around actual loan program manuals and will reflect the real requirements. The difference between a free calculator and a lender's internal tool is usually a matter of hours of development time and compliance review, and it shows in the accuracy.
Download and Use It
For a downloadable Cash To Close Calculator, you can use spreadsheet-based templates from reputable mortgage industry sites or build your own using the line items listed above. A basic Excel or Google Sheets version takes about 20 minutes to set up if you already understand the components. If you prefer a ready-made file, look for ones that include fields for purchase price, loan amount, closing costs, prepaids, escrow, seller credits, and adjustments. Avoid anything that doesn't show its source or formula—those are usually copied from outdated examples and will give you inaccurate numbers. The point of any Cash To Close Calculator is to give you a single actionable number before you walk into closing. You don't need perfection. You need enough visibility to know whether you're short $500 or short $5,000. That distinction changes how you plan your funds and whether you need to delay closing to cover a shortfall. That's it.