The cashflow quadrant isn't what you think it is
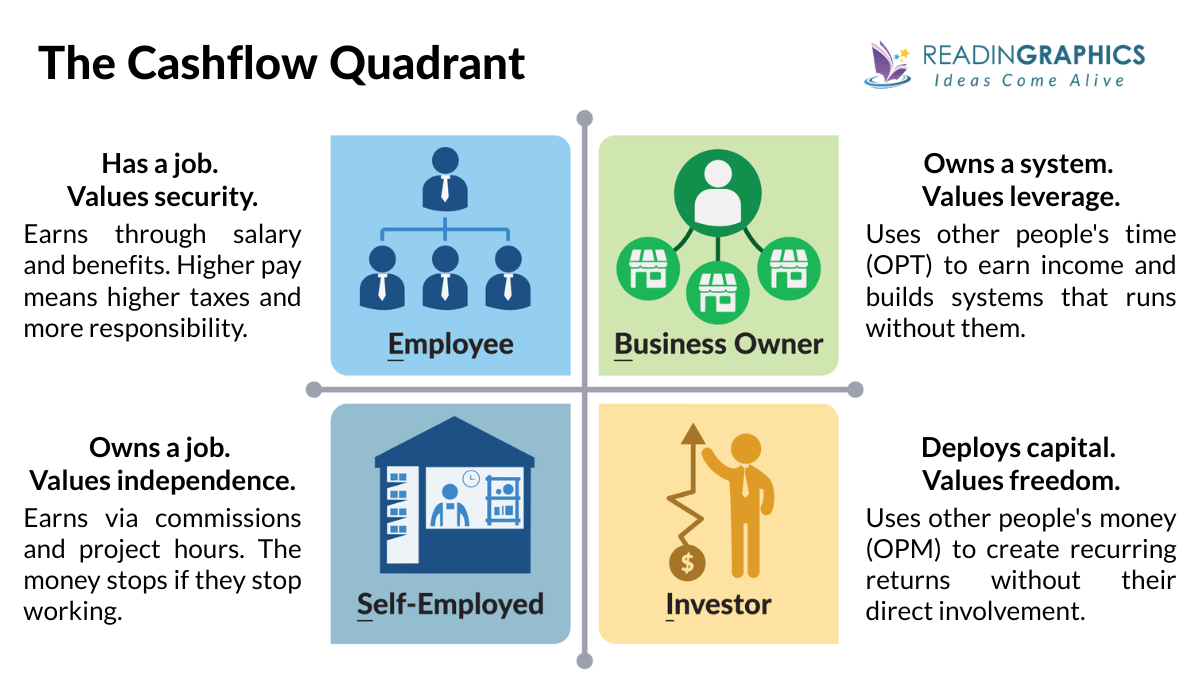
I've been coaching people through business transitions for about twelve years now, and the first thing I notice when someone pulls up the Cashflow Quadrant Book Summary is they treat it like a career map instead of what it actually is -- a behavioral taxonomy. The book's framework is elegant enough that it circulates widely in finance circles, but the real value shows up when you apply it to actual cashflow problems, not career decisions. Here's how it works in practice. The quadrant divides income sources into four categories: Employee (E), Self-Employed (S), Business Owner (B), and Investor (I). Each quadrant operates on completely different cashflow mechanics. Moving from E to S feels like a promotion to most people. It's actually a step backward in terms of cashflow sustainability, because you've traded time-based income for a business that still requires your direct involvement. That detail doesn't land until you've had a business where you're the bottleneck. I remember working with a client in 2019 who was a successful S-quadrant consultant. He made roughly $220,000 annually, felt financially secure, and wanted to read the Cashflow Quadrant Book Summary as a next-step guide. When I mapped his actual cashflow statement, I found that sixty-two percent of his revenue stopped the moment he took a week off. His books were profitable on paper, but his cashflow didn't behave like a business. It behaved like employment with a higher title. We spent three months restructuring his engagement terms and building a junior team before his cashflow curve shifted meaningfully. That's the trap the quadrant doesn't explicitly warn about: the S-to-B transition isn't a mindset shift. It's a structural overhaul.
Cashflow Quadrant Book Summary: how each quadrant actually generates money
The E quadrant is straightforward -- you trade hours for dollars, and the relationship is legally binding. Most people understand this. The S quadrant is where the confusion starts. Self-employed individuals often own their time, but they rarely own a system that produces income without them. A solo practitioner, a freelance developer, a independent contractor -- these are all S-quadrant positions regardless of income level. The income ceiling is the person's availability. The B quadrant is different because the system generates cashflow independent of the owner's daily presence. This isn't about having employees. It's about having a reproducible process that produces revenue regardless of whether you touch it. A franchise model, a SaaS product, a licensing arrangement -- these are B-quadrant structures because the cashflow mechanism exists separately from the individual. The I quadrant is the least understood and the most frequently oversimplified in popular summaries. Investing isn't just buying stocks. Real investing, as the quadrant frames it, means deploying capital into assets that generate positive cashflow on their own schedule. Dividend stocks, rental properties, private debt, business acquisitions -- these are instruments, not strategies. The strategy is the allocation framework, and most people skip that part entirely.
What most summaries miss about the quadrant
The big gap in casual Cashflow Quadrant Book Summary readings is that the framework doesn't account for cashflow velocity. Two people can sit in the same quadrant but have radically different financial outcomes based on how fast their money cycles. An S-quadrant consultant reinvesting thirty percent of income into B-quadrant assets will outpace an E-quadrant manager earning double their salary who spends everything. The quadrant measures behavior, not balance sheet health. Another thing people overlook: the quadrant assumes linear movement. You go E to S to B to I. Reality is messier. I've seen people jump from E directly to I through inheritance or lottery. I've seen B-quadrant owners liquidate and become S-quadrant consultants because the business couldn't sustain them without their direct involvement. The framework is directional advice, not a prescription. The most dangerous misconception I encounter is the assumption that the I quadrant is passive. It isn't. Managing a diversified investment portfolio that generates meaningful cashflow requires more active decision-making than most B-quadrant businesses. The difference is the time commitment per dollar managed. A B-quadrant owner might spend forty hours managing a million in revenue. An I-quadrant investor might spend twenty hours managing a million in assets under management. The work intensity is comparable. The exit options are not.
Get the Full Details

Edge case: when the quadrant breaks down
There's a scenario the original framework doesn't handle well: hybrid income streams. A software developer who writes a Python package and earns royalties while also consulting part-time sits in two quadrants simultaneously. Their W-2 income is E, their consulting is S, and their package revenue is I. Standard quadrant analysis treats each stream independently, which creates a fragmented picture. When I hit this with a client last year, I built a separate cashflow matrix tracking each income stream independently before mapping them onto the quadrant. It took two weeks of data collection but revealed that his I-quadrant revenue, while small at fourteen thousand annually, had zero marginal cost and grew eight percent year over year. Meanwhile his S-quadrant consulting revenue was growing but capped at roughly one hundred and eighty thousand based on billable hour constraints. The quadrant summary would have labeled him an S. The data showed he was functionally an I with an S-side hustle. That distinction changed how we structured his tax planning and reinvestment strategy.
Practical takeaways if you're actually using this framework
Don't read the Cashflow Quadrant Book Summary as career advice. Read it as a lens for auditing your current income structure. Pull your last twelve months of bank statements. Categorize every dollar of incoming cash into E, S, B, or I. You'll be surprised how many people who think they're building businesses are actually just self-employed with overhead. The second practical move is to measure your cashflow independence ratio: monthly passive income divided by monthly expenses. If it's below point three, you're one bad month away from financial stress regardless of which quadrant you identify with. The quadrant framework tells you where to build. It doesn't tell you how much to build before you're safe. A third thing most people skip: track your cashflow velocity within each quadrant. How quickly does money enter and leave each bucket? E-quadrant income cycles monthly by definition. S-quadrant income might cycle weekly or irregularly. B-quadrant income should cycle predictably because the system runs on schedule. I-quadrant income can cycle at any frequency depending on the asset class. When your velocity drops in a quadrant you've been in for years, that's a signal something is wrong with the structure, not just the market.
Where the framework falls short
The quadrant doesn't address tax efficiency across quadrants, which is a significant blind spot. An S-quadrant contractor and a B-quadrant business owner with identical gross income can have wildly different tax liabilities depending on structure. The book mentions this in passing but doesn't give you a practical mapping. If you're serious about quadrant transitions, you need a CPA who understands entity structuring, not just a business coach. The second shortcoming is geographic and regulatory variability. The B and I quadrants operate differently in different jurisdictions. A franchise model that works in the United States may not be viable in markets with different small business regulations. Real estate investing as an I-quadrant vehicle behaves completely differently in countries with high property transfer taxes or restricted foreign ownership. The quadrant is an American-centric framework, and that matters if you're applying it internationally. The third limitation is the implicit assumption that everyone wants or can access capital for I-quadrant moves. Building an investment portfolio that generates meaningful cashflow requires seed capital. Someone making fifty thousand annually as an E-quadrant worker has different options than someone making two hundred thousand. The quadrant treats all quadrants as equally accessible entry points, which isn't true in practice. Capital constraints are real, and they affect which quadrant transitions are feasible in a given timeframe.

Alternative frameworks worth considering
If the quadrant feels too binary for your situation, the concept of cashflow stacking -- developed more recently by a few finance practitioners -- layers income sources across quadrants simultaneously rather than treating them as sequential steps. You don't have to leave the E quadrant to start building I-quadrant assets. You don't have to scale a B-quadrant business to maintain S-quadrant income. Multiple streams operating across quadrants can create more resilient cashflow than a single dominant source, even if the dominant source sits in a "higher" quadrant. The original quadrant framework is still useful as a starting diagnostic tool. It forces you to categorize your income honestly instead of letting job titles and perceived status do the thinking for you. But it's a map, not the territory. The territory includes taxes, regulations, capital availability, market cycles, and the structural differences between quadrants that the book doesn't fully unpack. Read the book if you haven't. Then pull your actual cashflow data and see where you really sit. The answer might not match what you assumed.


