Working with Cfa Level 2 Practice Questions
Most candidates treat practice questions as a way to test whether they already know the material. That approach works fine for Level 1. Level 2 is different. The exam tests your ability to synthesize across topics under time pressure, and the question format reflects that. You are not answering a straightforward definition. You are working through vignettes that are deliberately dense, and the wrong answer often looks right until you read the second sentence of the stem. I spent three weeks going through a third-party question bank before I realized I was failing at a rate that did not match my actual knowledge. I was reading the questions too fast. I was skipping the data in the tables because I assumed the numbers would cancel out. One question on consolidated financial statements had a footnote about foreign currency translation adjustments buried in paragraph four. I missed it. The answer was literally in that footnote. I had to slow down and rework my approach.Where to Find Cfa Level 2 Practice Questions
The official CFA Institute question bank is the starting point. It is not the most polished resource, and the interface is clunky, but the questions are written by the same people who write the actual exam. Third-party providers like UWorld, Kaplan, and Mark Meldrum offer alternatives. Some of their questions are slightly harder than the real exam, which is useful. Others are harder in the wrong way, relying on trick wording rather than substantive difficulty. I found the CFAI questions the closest match in tone and structure. I recommend starting with the official Learning Extensions platform. It gives you timed exams that mirror the actual testing window. The pass rates on the practice exams tend to correlate reasonably well with performance on the real thing, though there is always a gap. Your score on a practice exam is not a reliable predictor within a five percentage point band. Treat it as a direction indicator, not a crystal ball.The Mechanics of a Level 2 Vignette
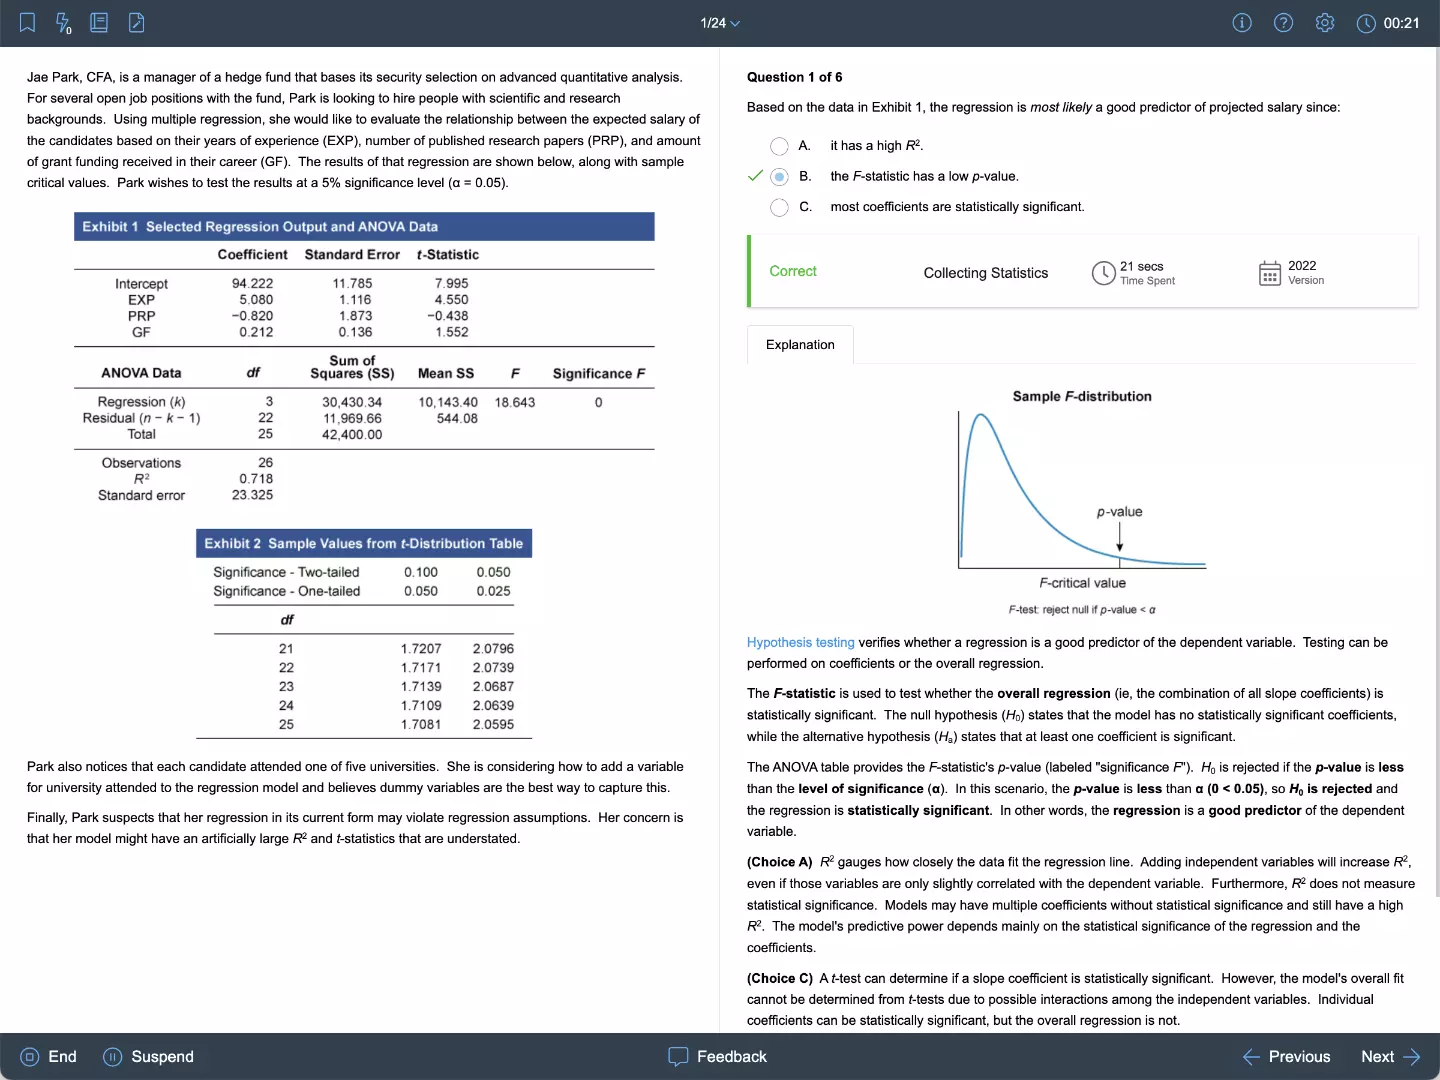
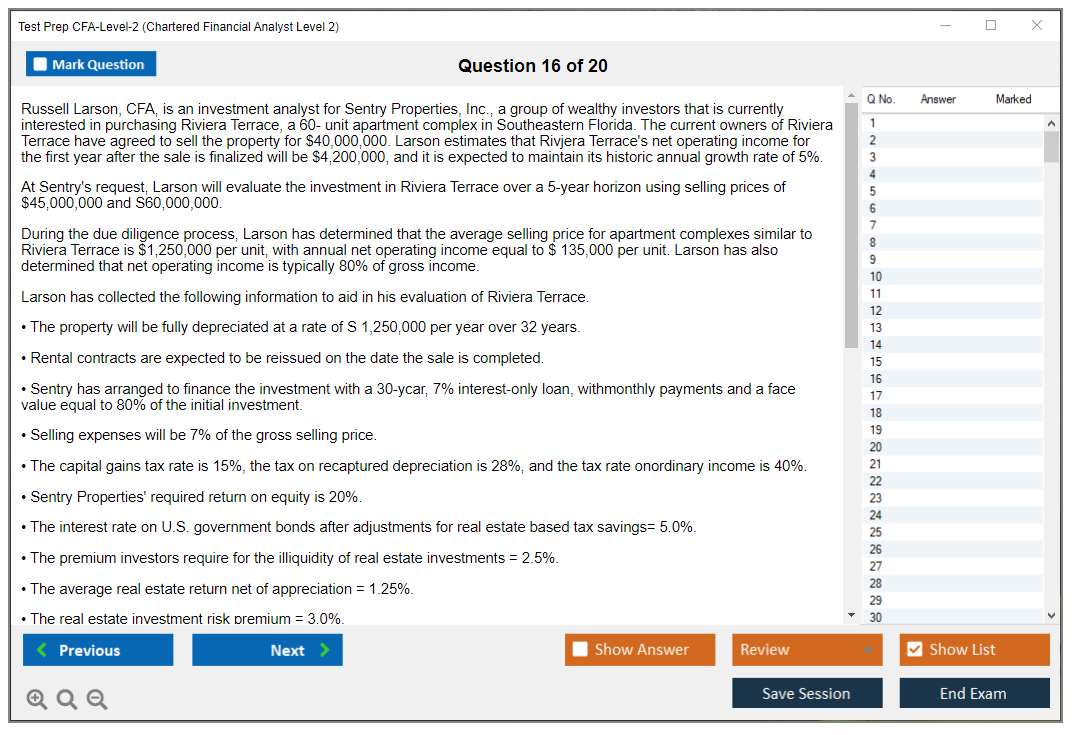
A standard vignette runs between five and seven paragraphs. It contains financial statements, tables, footnotes, and sometimes a short case study background. Each vignette feeds three to six questions. You have about nine minutes per question across the entire session. That is not a lot of time when you are pulling data from multiple sources inside the same prompt. The biggest mistake I see candidates make is treating every question inside a vignette as independent. They are not. Answering question one correctly often requires information that becomes relevant for question four. Skipping around too much causes you to lose your place in the vignette. Read the entire vignette once before touching any of the questions. Spend maybe two to three minutes on that first pass. Note down where key data lives — which table has the depreciation schedule, which footnote discusses the lease terms, which paragraph mentions the impairment trigger. This usually saves you three or four minutes later when you are cycling back.Tax provisions and deferred tax assets are the topics where candidates lose the most points unnecessarily. The calculations themselves are straightforward. The problem is that the vignette will give you temporary differences, permanent differences, and valuation allowance considerations all mixed together. I learned to separate those three categories on scratch paper before doing any math. Writing them out explicitly cuts down on errors significantly. You cannot rely on holding all of that in your head while juggling the other requirements in the same vignette.
Pension and Postretirement Benefit Questions
This is one of the areas where practice questions expose the gap between knowing the formula and applying it under exam conditions. The pension questions on Level 2 mix projected benefit obligation, plan assets, amortization of gains and losses, and service cost into a single calculation chain. A single wrong input cascades through every subsequent number. I encountered a question where the discount rate changed mid-year due to an amendment. The vignette stated the amendment occurred on July first. Most people applied the new rate to the entire year's interest cost. It should only apply to the period after the amendment. I caught this on my fourth attempt at the same question type by flagging date-sensitive changes in the footnote section before starting any calculation. That habit alone prevented a cluster of errors on my actual exam day.Equity and Fixed Income Question Patterns
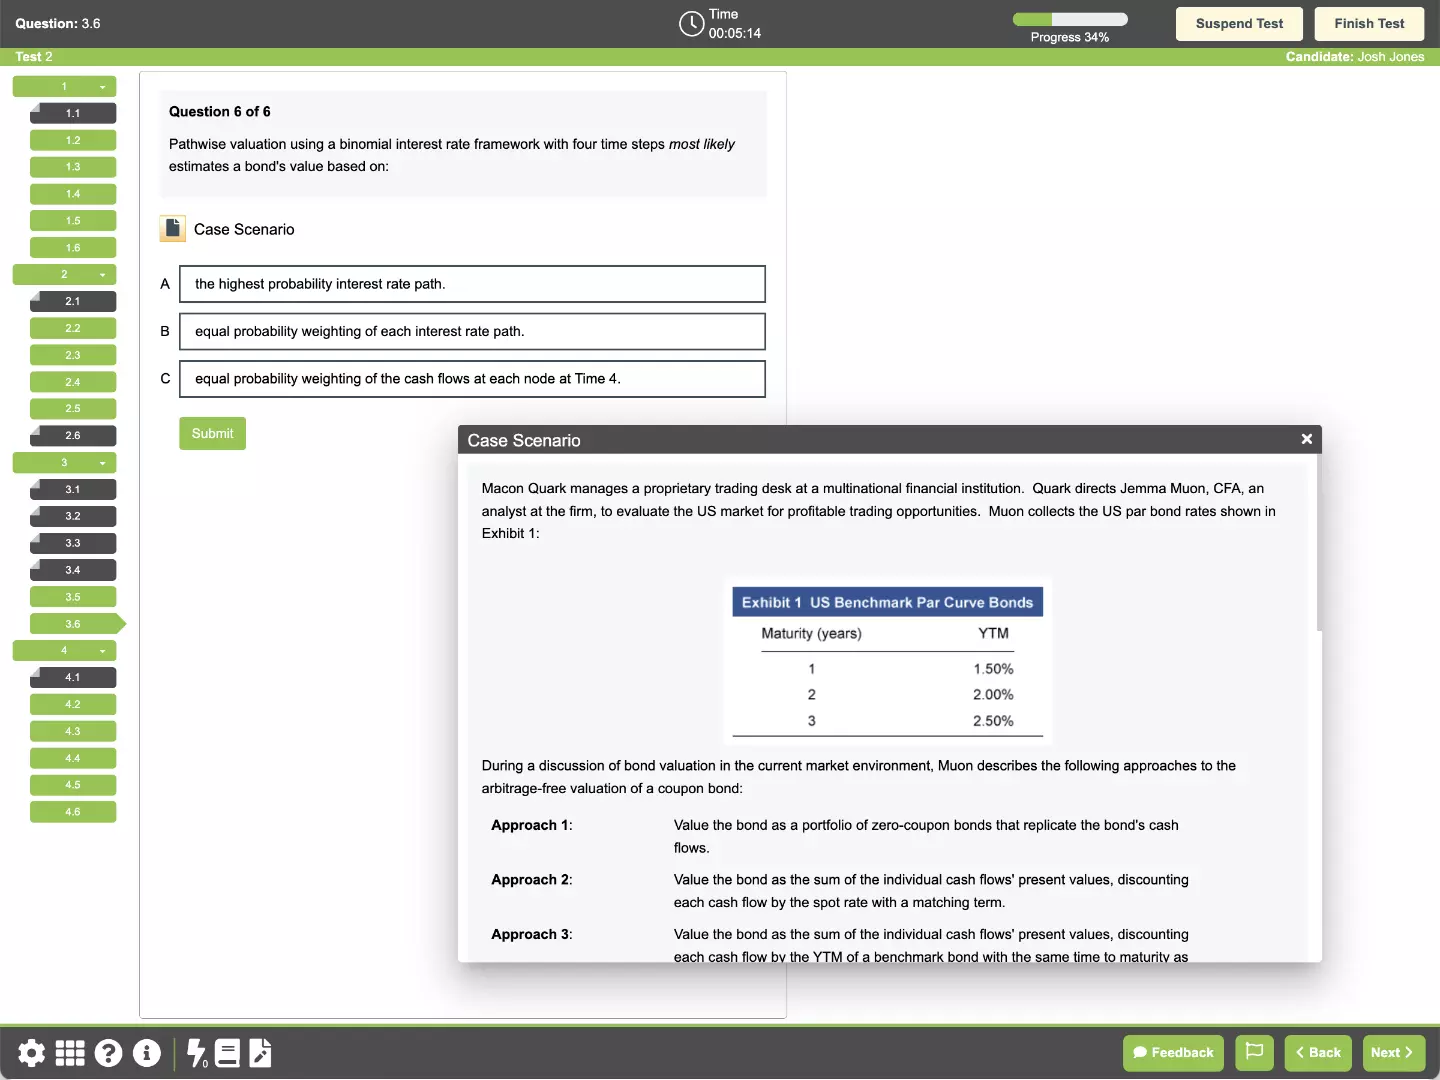
Equity questions frequently test you on dividend discount models with multiple growth phases, residual income models, and economic value added calculations. The tricky part is that the vignette will often give you more information than you need. It will include industry benchmarks, competitor data, and macroeconomic forecasts that look relevant but do not factor into the specific model you are supposed to use. Identifying the extraneous data quickly is a skill you build through repeated exposure. Fixed income questions revolve around option-adjusted spread, backward induction, and bond valuation with embedded options. The OAS calculation requires you to strip out the value of the option component from the total spread. Many candidates confuse OAS with Z-spread. The Z-spread is a constant spread added to the spot rate curve. The OAS adjusts for the optionality. Knowing the distinction matters because the question stem will ask for one or the other, and picking the wrong one gives you an answer that looks close but is definitively wrong.Financial Statement Analysis Depth
FSA carries the highest weight on the exam, and the practice questions reflect that. Revenue recognition, inventory methods, lease accounting, and income taxes are the core topics. But the advanced applications are where the real differentiation happens. Questions about LIFO liquidation effects on cash flow from operations, or the treatment of stock-based compensation in non-GAAP measures, appear regularly. One edge case that trips people up involves intercompany profit elimination in consolidation. When a parent sells inventory to a subsidiary and the subsidiary has not yet sold it externally, you must eliminate the unrealized profit from both the parent's income and the subsidiary's inventory value. If the ownership is not 100 percent, you also need to allocate the elimination between controlling and non-controlling interests. I used to skip the NCI allocation step because I assumed it was not tested that deeply. It is. A question on my exam required exactly that calculation, and I had wasted two minutes recalculating it after missing the detail the first time.Building a Practice Routine That Actually Works
Do not do questions in random order. Group them by topic until you can consistently hit above 70 percent on a given subject area. Then mix them. The exam throws topics together intentionally. If you only practice in topic blocks, you will be unprepared for the cognitive switching required on test day. Simulate the exam conditions at least once per week in the final month. Full two-hour sessions with no pauses, no phone, no reference materials beyond what is allowed. The mental fatigue sets in around question twenty-five, and that is when mistakes multiply. I noticed my error rate climb from about eight percent to nearly twenty-two percent after hour one and forty minutes on my early simulations. Once I started scheduling short mental breaks and practicing through the fatigue window, my late-session accuracy improved noticeably.Use the explain your answer for every question rule. When you get a question wrong, you should be able to articulate not just why the correct answer is right but why each of the three wrong answers is wrong. If you cannot explain the distractors, you have not truly understood the concept. This typically takes twice as long per question, but it compresses your learning curve significantly over a four to six week period.