What CFP Exam Example Questions Actually Look Like in Practice
Most people approaching the CFP certification don't realize the exam isn't testing whether they can memorize formulas. It's testing whether they can apply them under time pressure when the numbers are messy and the scenario is deliberately ambiguous. I've seen candidates who knew their time value of money cold freeze up on question types that required prioritizing incomplete information. The CFP Board designs the exam around competency-based scenarios, not trivia. This means the questions present you with a client situation, a set of financial data, and a specific request. Your job is to identify what matters, do the calculation or analysis, and select the best answer from four options. Each question has a single correct choice, though some answer options are designed to trap people who jump to conclusions too quickly.
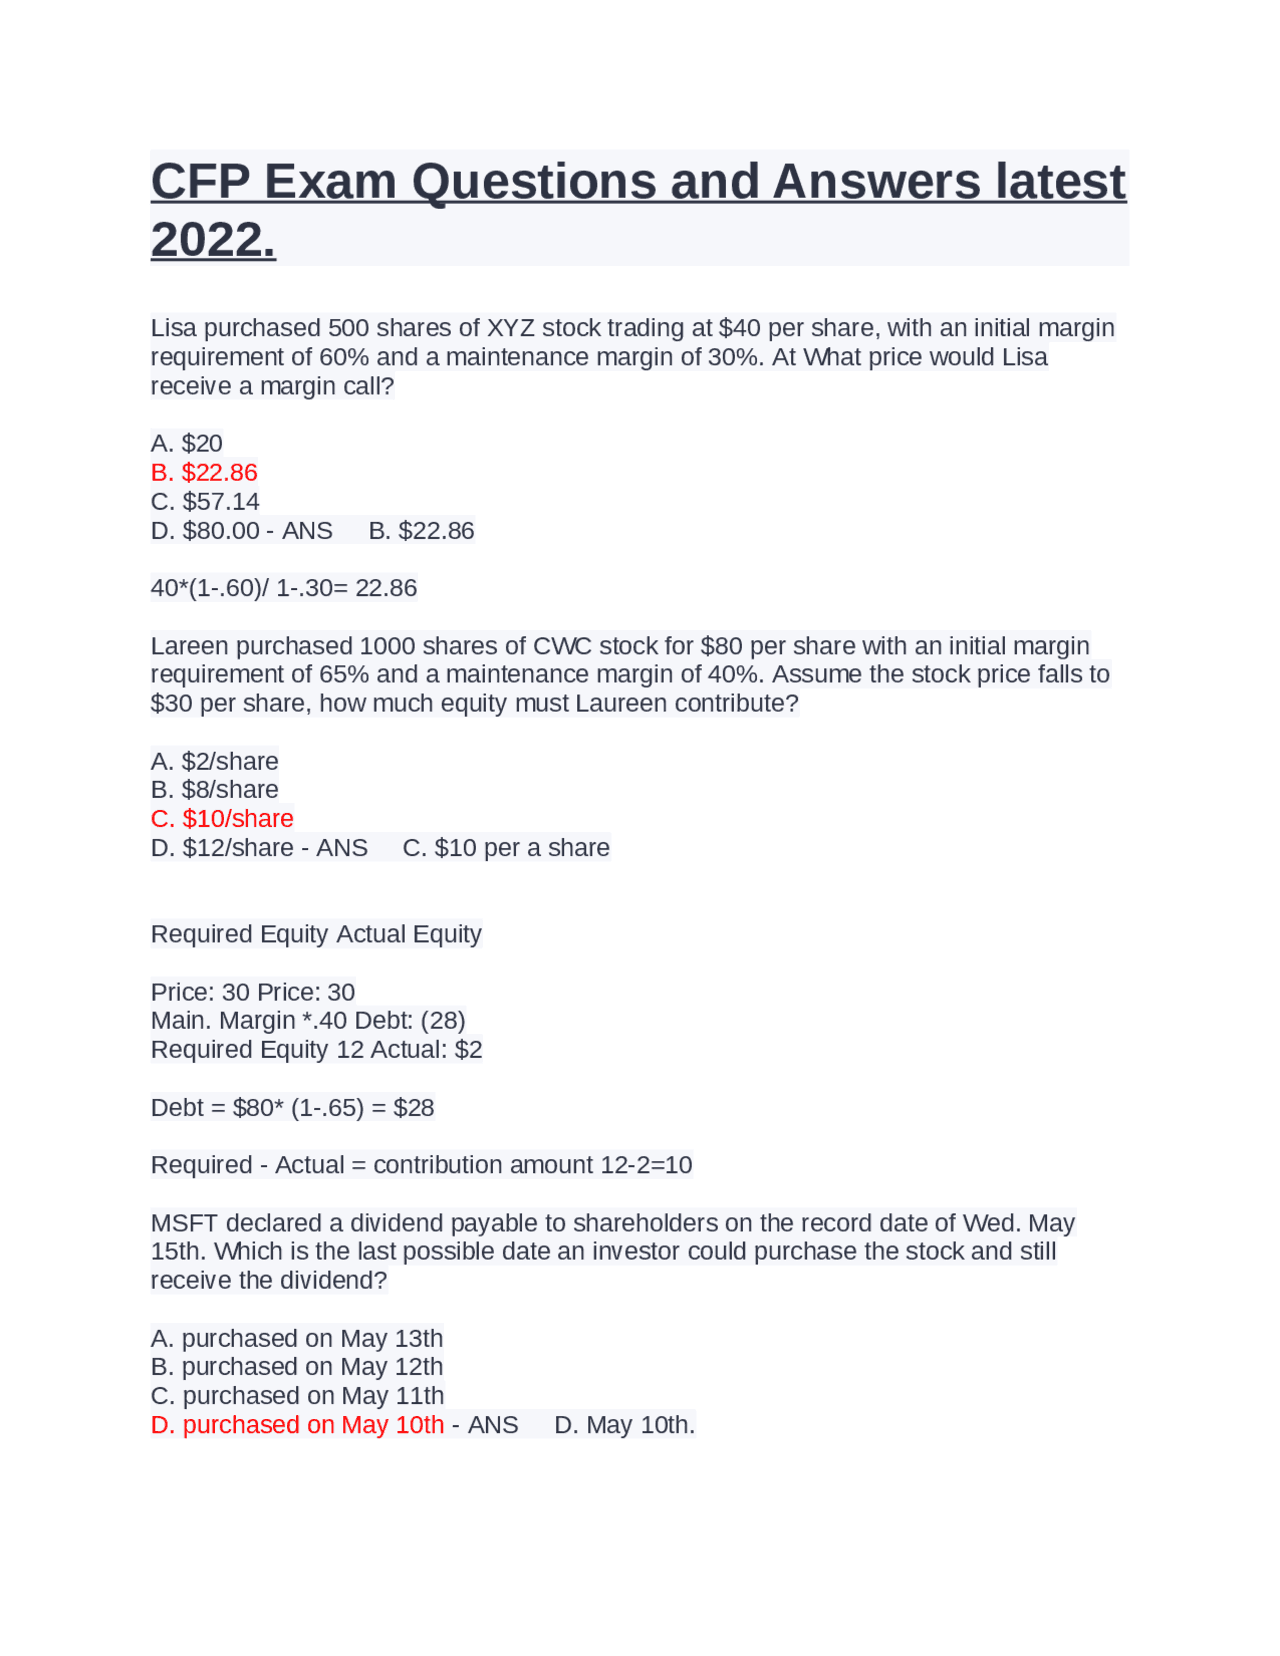
Cfp Exam Example Questions That Reveal How the Test Really Works
Here's a straightforward example you might encounter: A client, age 42, has a current portfolio worth $385,000. They plan to retire at 65 and expect to live until 90. They want to maintain an annual after-tax income of $65,000 throughout retirement. Their portfolio earns a 7% annual return before retirement and 5% during retirement. Inflation averages 2.5% annually. What is the minimum amount they need to save each year starting today to meet this goal? This is a two-phase calculation. First, you determine the retirement nest egg required by calculating the present value of the retirement income stream, adjusted for inflation. Then you work backward to find the annual contribution needed to reach that nest egg. The trap here is forgetting to adjust for inflation during both phases. Several answer choices reflect common mistakes like using nominal dollars without adjustment or mixing pre-retirement and post-retirement rates incorrectly.
The actual steps look like this: calculate the real rate of return during retirement using the Fisher equation, find the number of retirement years (90 minus 65 equals 25), compute the present value of an annuity due for the retirement phase, then compute the future value needed at retirement, and finally solve for the annual payment using the future value of an ordinary annuity formula for the accumulation phase. You'd arrive at an approximate annual savings requirement of roughly $18,000 to $20,000 depending on rounding choices and whether you treat contributions as beginning or end of period.
Get the Full Details

How to Approach the Exam Without Losing Your Mind
The CFP exam gives you about 100 to 120 situational questions across multiple disci plines: general principles, retirement planning, tax planning, estate planning, investment planning, employee benefits, insurance planning, and psychology of financial planning. You have roughly three hours. That's about 90 seconds per question if you're keeping even pace. Here's what actually works, based on watching hundreds of candidates prepare and take this exam over the years. Practice with full-length timed simulations. Not individual topic quizzes. The real exam switches contexts every few questions, and your brain needs to build the stamina for that pattern. If you only study one topic at a time, you'll be disoriented when you sit for the actual test. A full mock exam takes about two and a half hours to complete and about another hour to review thoroughly. Do at least five of these before the real thing. Your score shouldn't matter during practice, but your time management absolutely should.
Learn to eliminate wrong answers fast. Two of the four choices on every question are usually clearly wrong if you know the material. The other two will be close. Identifying the clearly wrong ones first gives you a mental break and improves your odds even if you guess between the remaining pair. I once had a candidate who told me she consistently got her lowest scores on questions involving the difference between gross versus net present value in capital budgeting scenarios. She started eliminating the answer choices that used the wrong discount rate or failed to account for tax shields, and her accuracy on that topic improved noticeably within two weeks of targeted practice. Don't get stuck. If a question requires multiple calculation steps and you realize halfway through that you're burning more than three minutes, mark it and move on. You can come back if time allows. Spending six minutes on one hard question means you probably rushed three easier ones you could have nailed in two minutes each. That trade-off hurts your score more than you'd expect.
The Hidden Complexity Most People Miss
The exam has a subtle layer that most study guides don't emphasize enough. The scenarios often include irrelevant information designed to distract you. A client profile might mention their occupation, their children's education plans, their charitable giving, and their health status when the question only asks about one specific aspect. Recognizing what to ignore is as important as knowing what to use. I encountered this repeatedly during my own exam preparation and later when coaching others. One specific edge case that caused real trouble involved a question about Roth conversion timing for a client in a non-standard tax situation. The scenario described a client with substantial traditional IRA balances, variable income year to year, and a planned early retirement before age 59 and a half. The question asked about the optimal conversion strategy. Multiple answer choices looked reasonable on the surface. The correct approach required calculating the marginal tax rate impact in each scenario year, factoring in the phase-out of certain deductions, and considering the five-year rule for Roth conversions alongside the early withdrawal penalty exceptions. The distractor answers each contained one plausible element but missed a compounding consequence somewhere in the chain. I learned to map out the decision tree on scratch paper rather than holding it all in my head, which cut my error rate on these multi-step questions significantly. Another common pitfall involves the interaction between Social Security optimization and retirement withdrawal strategy. The exam frequently tests whether you understand that withdrawing from tax-deferred accounts first can push you into a higher tax bracket and increase your taxable Social Security benefits. Candidates who treat these as independent decisions get the question wrong. The correct answer usually involves coordinating the withdrawal sequence with bracket management.
Building Your Study Plan Around the Right Material
Use official CFP Board study materials as your foundation. The sample questions they provide reflect the actual question structure and difficulty level more accurately than third-party materials typically do. Supplement with commercial prep courses if you need structured content delivery, but don't rely exclusively on them for practice exams. Their questions sometimes skew too theoretical compared to the applied nature of the real exam. Focus your study on the task domains the exam actually covers. The CFP Board publishes a detailed task and ethics inventory that maps each exam question to a specific competency area. Investment planning and retirement planning carry the heaviest weighting. Tax planning and estate planning are also significant. Insurance and employee benefits round out the core areas. Psychology of financial planning appears less frequently but still shows up in ways that test your ability to recognize behavioral biases in client scenarios. Study groups can help if they're well-run. Someone explaining a concept out loud often reveals gaps in their own understanding that passive reading never surfaces. But don't form a group where people just read answers to each other. The value comes from working through the reasoning, not from getting the right answer handed to you.
The exam format changed recently to a computer-based delivery with a more adaptive feel. Some question types now present a case study followed by multiple sub-questions that build on each other. This means your answer to question three might affect your calculation for question four. Practicing with these linked scenarios beforehand is essential because the format itself adds cognitive load on top of the content difficulty. One practical tip: the exam provides a formula sheet, but memorizing the key formulas anyway saves time. Looking up a standard TVM formula during the test costs you seconds you can't afford when you're already behind. The formula sheet is useful for the less common equations, not for the ones you use constantly. There's no shortcut that replaces solid preparation. The exam is difficult by design because the certification carries real weight in the financial planning industry. Candidates who treat it as a manageable challenge rather than an insurmountable hurdle tend to perform better than those who approach it with anxiety or overconfidence. Both attitudes produce the same result: inadequate preparation time for the actual material depth required.