What You Actually Need When Preparing for the CFP Exam
The CFP certification exam is brutal. It tests knowledge across retirement planning, estate planning, taxes, insurance, investments, and ethics. Most people underestimate how much material there is. The official course covers roughly 100 topics, and you are expected to apply them, not just recognize them. That means your study resources need to simulate real exam conditions as closely as possible. I spent about six months prepping for my own exam while working full-time. The main bottleneck was never the content itself. It was figuring out which practice materials actually mirrored the difficulty and format of the real thing. A lot of third-party question banks are too easy, or they test recall instead of application. That gap between what the practice questions look like and what the actual exam looks like will cost you points.
Where to Find Cfp Practice Exam Questions
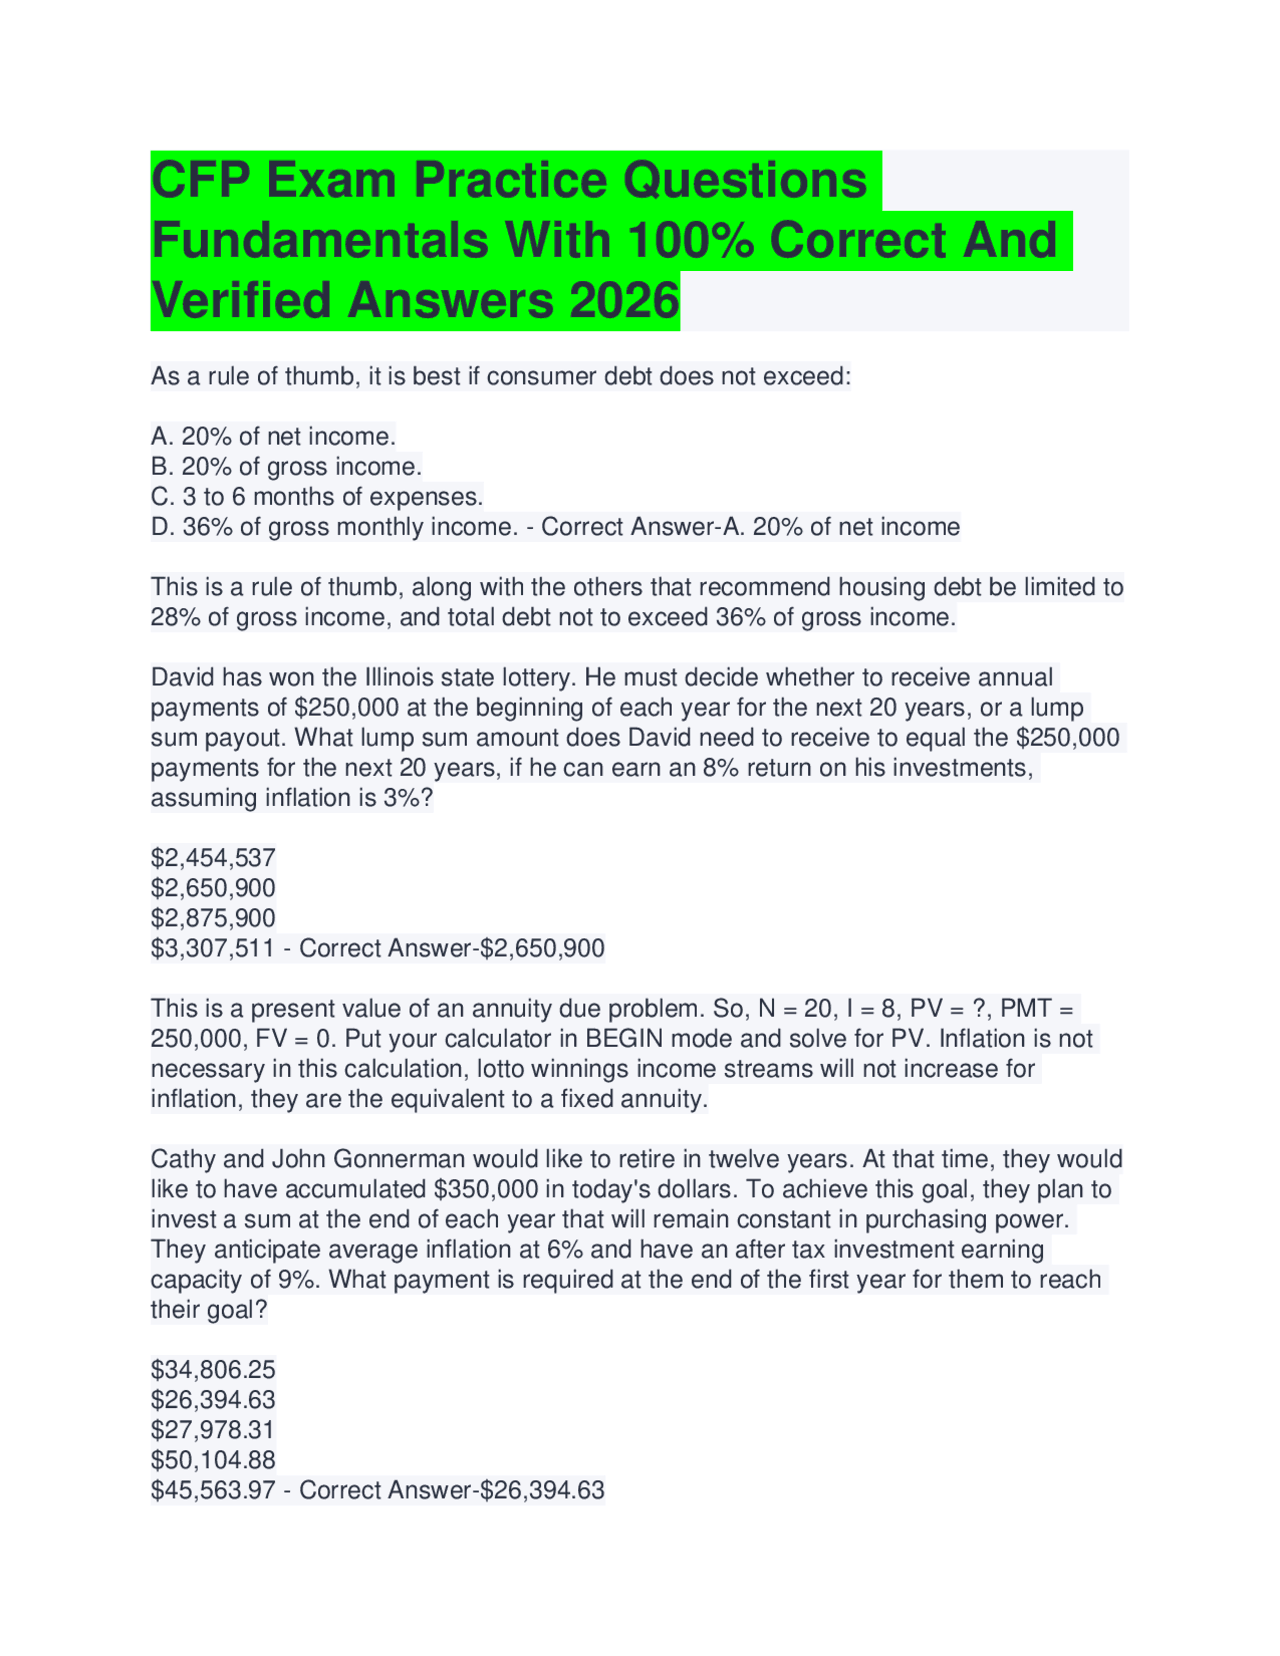
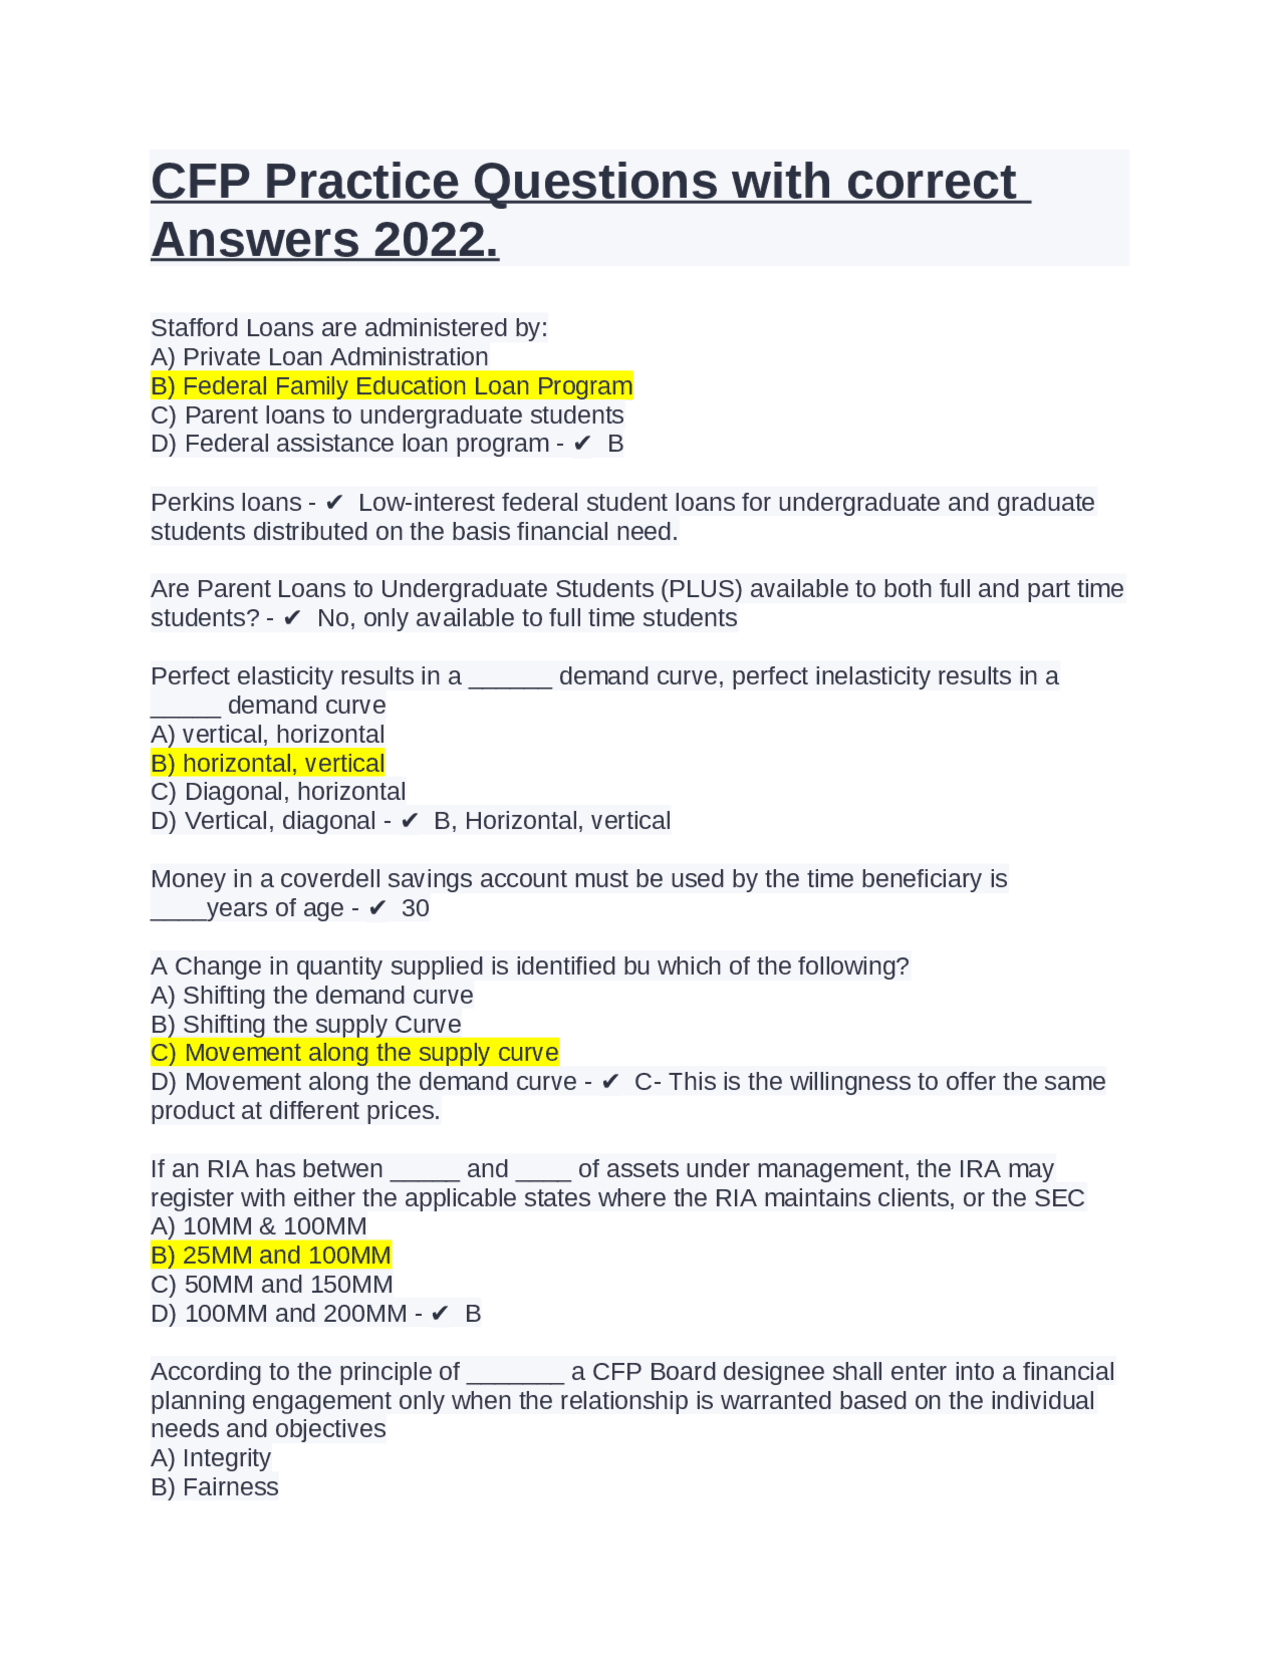
The CFP Board itself publishes a sample exam, but it only has 150 questions. That is not enough for serious prep. The most useful options are the official study program questions that come with the CFP Board Registered Education Program, plus a few commercial question banks from providers like Kaplan, Gleim, and Anheuser. Kaplan's question bank tends to be closest to the real exam in terms of wording and difficulty curve. Gleim is cheaper but more straightforward. Anheuser has good explanations but fewer total questions. Here is the direct path to the official sample exam: the CFP Board website at cfpboard.org lists it under the certification section. Their registered education program partners also give you access to their internal question banks. Kaplan and Gleim sell theirs directly through their own sites.
How to Actually Use Practice Questions Effectively
Most people use practice questions wrong. They do a block of 30 questions, check their score, move on. That approach barely works. Here is what I ended up doing instead, and it cut my study time down meaningfully compared to what I saw other people doing. First, do questions in mixed topic order. The real exam does not group questions by subject. If you study by chapter, you will be set up for failure on test day. Randomize your question sets so you are constantly switching between estate planning, tax, and retirement calculations. This forces your brain to retrieve the right framework faster, which is what the timed exam actually demands. Second, write out why each wrong answer is wrong. I know that sounds tedious, but it is the difference between memorizing an answer and understanding the concept. I kept a notebook where I noted every question I got wrong and the specific reason. After three weeks of that, I stopped making the same mistakes twice. That habit alone probably saved me five or six points on the actual exam, maybe more.
Get the Full Details
Third, simulate real conditions at least twice before the exam. Set a timer. No notes. No pauses. Sit in a chair, not on your bed. The real exam is four hours long, and your attention drops significantly after the first two hours. If you have only ever done twenty-question blocks, your stamina will not be there when you hit question eighty and your brain is already fogged out. There is one specific edge case I ran into that I want to flag because it caught me off guard. The CFP exam occasionally includes questions where two answers seem equally correct, but one is more correct based on the client's specific facts. I got tripped up on a question about whether to recommend a Roth conversion or a traditional contribution for a client near retirement with high current marginal tax rates. Both answers were defensible depending on how you read the scenario. What I should have done was look for the answer that tied back most directly to the client's stated goal in the first sentence. The exam rewards matching the recommendation to the client's primary objective, not picking the technically superior financial outcome in a vacuum. I started underlining the client's stated goal in every question that had a client scenario. It changed my accuracy rate on those types of questions from about sixty percent to around eighty-five percent.
The Counter-Intuitive Parts Nobody Talks About
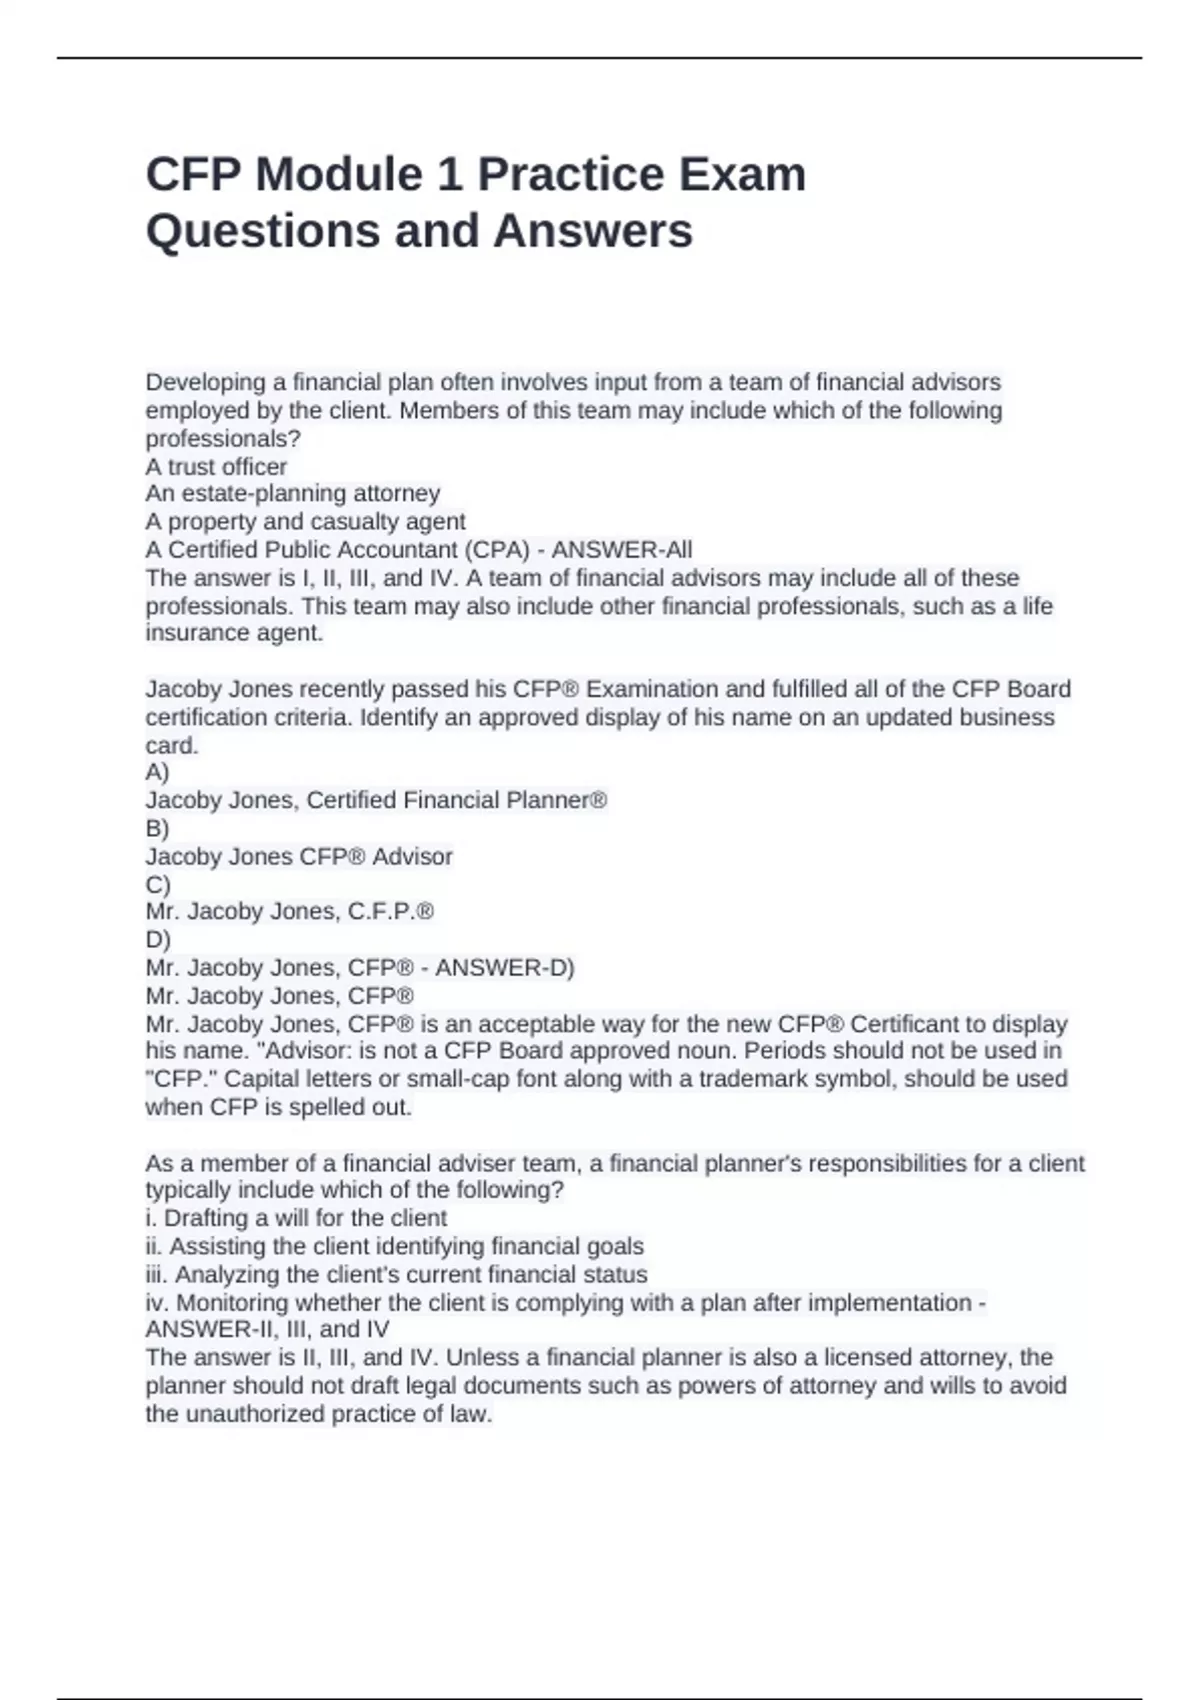
Most people think they need to memorize formulas. They do not. You need to understand when to use which formula and, more importantly, when not to use it. The exam gives you a formula sheet. Memorizing it is useless. What matters is recognizing the scenario that calls for a specific calculation. I spent way too much time early on re-deriving time value of money formulas and not enough time practicing identifying which formula applied to a given word problem. Another thing: ethics questions are not soft points. People assume they can guess on ethics and save time for the harder stuff. The ethics section is roughly twelve percent of the exam, and the questions are deceptively complex. They often involve a conflict between two ethical principles rather than a clear right versus wrong. You need to know the CFP Board's Code of Conduct and Principles cold, not just the general concepts. I skimmed the ethics material twice before the exam and failed to internalize it properly. I wish I had read it cover to cover and done every ethics question in my question bank at least once.
What Practice Exams Do Not Cover Well
They rarely test the stamina required. The real exam is long and mentally exhausting. You will see questions that look straightforward at first glance but require three or four steps to solve. You will also see questions where the answer choices are numerically close, forcing you to calculate precisely instead of estimating. A lot of practice exams give you answer choices that are far apart, which makes estimation work. On the real exam, you need to be comfortable doing the full calculation under time pressure. Practice exams also tend to be less nuanced on client interaction questions. The real exam embeds softer skills questions within technical scenarios. You might be solving a retirement cash flow problem, but the correct answer depends on how the client communicated their risk tolerance, not just the math. Commercial question banks are slowly getting better at this, but the official CFP Board questions still set the standard. If you are struggling with a particular section, my recommendation is to go back to the official CFP Board study materials for that topic. Their explanations are tighter and more aligned with what the exam actually tests. Third-party resources are fine for volume, but the official content is where the nuance lives. I used Kaplan for the bulk of my practice questions but switched to the CFP Board's own materials for my final two weeks of review, specifically for ethics and the client communication questions I was getting wrong.
Numbers That Actually Matter
The passing score is a scaled score, which means the raw number of questions you get right is not directly comparable from one exam sitting to the next. You need somewhere in the ballpark of 70 to 75 percent of the questions correct, depending on the difficulty calibration of your specific exam form. That means if the exam is slightly easier, you need a higher raw percentage. If it is harder, the scaling adjusts. This is why practice exams with a consistent difficulty level can be misleading. Doing well on an easy question bank does not guarantee you will pass the scaled version. I targeted around 80 percent on my practice exams before scheduling the actual test. That gave me enough buffer for the scaling effect and the fatigue factor on exam day. If your practice scores are consistently below 70 percent, you are not ready. Pushing through without fixing the gap is just delaying the problem. The whole process is manageable if you treat the practice questions as the core of your study plan rather than an add-on. Most people make the mistake of studying content first and practice questions later. Flip that. Start with practice questions early, identify your weak spots, then study the content with those weak spots in mind. It is faster and it sticks better because you are studying with a specific problem in front of you instead of absorbing material blindly.