How the CFPB actually uses the UDAAP exam manual
The CFPB Udaap Exam Manual isn't something you memorize. It's something you read once and then keep open on your second monitor while you work. The Bureau publishes examination procedures that tell field staff how to look for unfair, deceptive, or abusive acts or practices at banks, credit unions, and non-bank financial companies. Most people treat it like a checklist. That's the wrong way to use it. I spent three years reviewing UDAAP examination files before I ever saw one actually result in an enforcement action. What I learned is that the manual is really a framework for thinking, not a set of instructions for compliance. You can follow every item on the list and still miss the real problem. Here's how that works in practice.
Where to get the Cfpb Udaap Exam Manual and what to do once you have it
The document lives on the CFPB website under their examination procedures section. It's free. You don't need permission to download it. The URL changes occasionally, so if a link stops working just search for "CFPB examination procedures UDAAP" and the current page should come up. Some firms pay third-party services to host the document and add commentary on top. That's fine if you want someone else to do the reading, but the raw manual is available without spending anything. Once you have it, don't start with the definitions. Start with the examination methodology section. The manual's actual value is in how the examiners structure their investigation, not in what they define UDAAP to mean. The definitions are already well established through case law. The methodology is where people get tripped up.
The methodology is where most people get this wrong
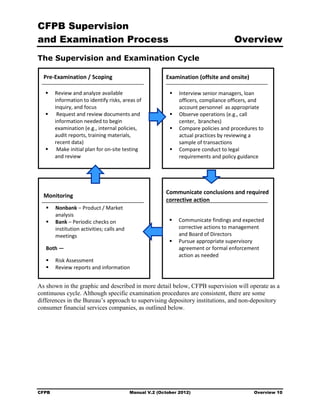
Examiners don't walk into an institution and ask "do you engage in UDAAP." They follow a multi-step process that starts with gathering data, moves through pattern identification, and ends with whether a violation is more likely than not. The manual lays this out in what looks like a standard exam workflow. In reality the steps overlap in ways the document doesn't make clear. Here's an edge case I ran into. During an exam I was reviewing a lender's marketing materials for deceptive practices. The manual says to examine advertising, disclosures, and customer communications separately. But the misleading effect came from the combination of three documents that were individually accurate. The loan estimate had correct numbers. The marketing brochure had correct numbers. The sales script had correct numbers. Taken together they created a false impression that no single document produced. The examiner on the other side of the desk told me we couldn't pursue it because each piece was technically compliant. I pointed to the manual's own language about the totality of circumstances. We eventually built the case. It took six months longer than it should have. This is the kind of thing the manual implies but doesn't emphasize enough. Examiners are human. They want clean lines. Your job as someone navigating this process is to force the holistic view earlier.
Get the Full Details

What the manual gets right and what it leaves out
The manual is strong on process. It tells you how to interview staff, how to select transaction samples, how to document findings. Those sections are practical and mostly accurate. The weakness is in the guidance on abusive practices. The CFPB's definition of "abusive" has always been the squishiest part of UDAAP, and the manual reflects that ambiguity without fully acknowledging it. One counter-intuitive point that beginners miss: UDAAP violations don't require proof of intent. The CFPB has brought cases against institutions that had no knowledge of the problem and no reckless disregard. Negligence is enough in many contexts. I've seen compliance teams waste weeks trying to establish subjective intent when the examiner's burden is lower than they thought. That misalignment costs time and sometimes costs the case. Another point the manual understates: the importance of customer complaint data. The CFPB publishes a consumer complaint database. Institutions frequently ignore it during self-assessment. Examiners don't. If your complaint patterns show repeated issues around a specific product or practice, that data is essentially pre-building the examiner's case for them. The manual mentions complaints as a sourcing tool. It doesn't make clear how weighty that evidence becomes once you've already flagged the problem in your own records.
How long this actually takes
Running a proper UDAAP self-assessment using the manual's methodology takes between 40 and 80 hours for a mid-size institution. Larger companies run into the hundreds. The bottleneck is almost always data collection, not analysis. The manual assumes you can pull transaction records, marketing materials, and complaint files quickly. In practice that's rarely true. Budget extra time for that phase. If you're doing this for the first time, start with your highest-risk product line. Don't try to cover everything at once. The manual doesn't say this explicitly, but examiners prioritize by risk anyway. Match that approach and you'll get more useful results faster.
When the manual doesn't help
There are scenarios where the UDAAP exam manual provides limited guidance. Emerging fintech models, for example. The Bureau wrote these procedures around traditional lending and banking products. When you're dealing with buy-now-pay-later arrangements, crypto-adjacent services, or subscription models with automatic renewal, the manual's examples don't map cleanly. You still apply the same legal standards, but the examination framework needs adaptation. Another limitation: the manual is designed for supervised institutions. If you're an independent consultant or a smaller company working without regular CFPB oversight, you'll find gaps. The procedural detail assumes an institutional relationship that doesn't exist everywhere. Supplement it with the CFPB's enforcement orders and consent agreements. Those show how the Bureau applies the manual in real cases. They're more useful than the manual itself for understanding where the enforcement boundary actually sits.
Practical next steps
Download the current version from the CFPB's official site. Read the methodology sections twice before touching the definitions. Map your product lineup against the manual's examination areas. Flag where your operations don't fit the examples cleanly. Build your assessment around those gaps first. Keep the enforcement order database bookmarked alongside the manual. The combination gives you both the process and the outcome data that the standalone document lacks. I keep the manual open next to a folder of recent CFPB consent orders. That's the setup that actually works. Everything else is just reading.