Working Through Net Income Chapter 2 Problems
If you're studying financial accounting, Chapter 2 on net income is where most students hit their first real wall. The material covers revenues, expenses, accruals, deferrals, and adjustments—stuff that sounds simple until the problems get stacked together. You end up with a worksheet that looks like a mess of debits and credits, and you have no idea whether you actually solved it right or just made it look convincing. The Chapter 2 Net Income Answer Key is what most students grab at that point. It's not a replacement for understanding the mechanics. It's a checkpoint. You work through the problem, then check your numbers against it to see where your logic broke down. The real value isn't in matching final digits. It's in seeing what step you diverged from and why. I've been grading these assignments for years. The answers themselves are straightforward in most textbooks, but the path students take to get there is where things fall apart. A lot of people miss adjusting entries. They treat revenues and expenses as cash inflows and outflows instead of recognizing when the economic event actually happened. That mistake cascades through everything—gross profit becomes wrong, operating income becomes wrong, and net income ends up nowhere near the right number.
Here's a practical example. A common Chapter 2 problem involves prepaid insurance. The company pays $12,000 for a 12-month policy in January. By the end of the month, you need to recognize one month of expense. Simple enough. But the next part of the problem might include unearned revenue where the company collected $5,000 in advance for services not yet performed. If you don't make the adjusting entry to defer that amount, your revenue is overstated and so is your net income. I've seen students lose half the points on this type of problem just because they forgot the second adjustment.
Chapter 2 Net Income Answer Key: How to Use It Without Cheating Yourself
Most answer keys at this level follow the same structure. They show the adjusted trial balance, the income statement, and sometimes the journal entries. What they often don't show is the thinking behind the entries. That's where you need to work. Start by attempting every problem before looking at the key. Even if your answer is completely wrong, the attempt forces you to confront where your gaps are. Then open the key and compare line by line. Don't just glance at the final net income number. Look at each adjusting entry and ask yourself whether your logic matched the key's logic or just happened to produce the same result by accident. Coincidental correctness is the most dangerous outcome because it gives you false confidence. One specific workaround I use with my own material is to write out the T-accounts before touching journal entries. When a problem involves multiple adjustments—like depreciation, accrued salaries, and supplies expense—T-accounts keep everything visible in one place. You can see the unadjusted balance, the adjustment, and the adjusted balance without juggling numbers in your head. I've found this cuts down errors significantly compared to just writing journal entries directly.
Get the Full Details
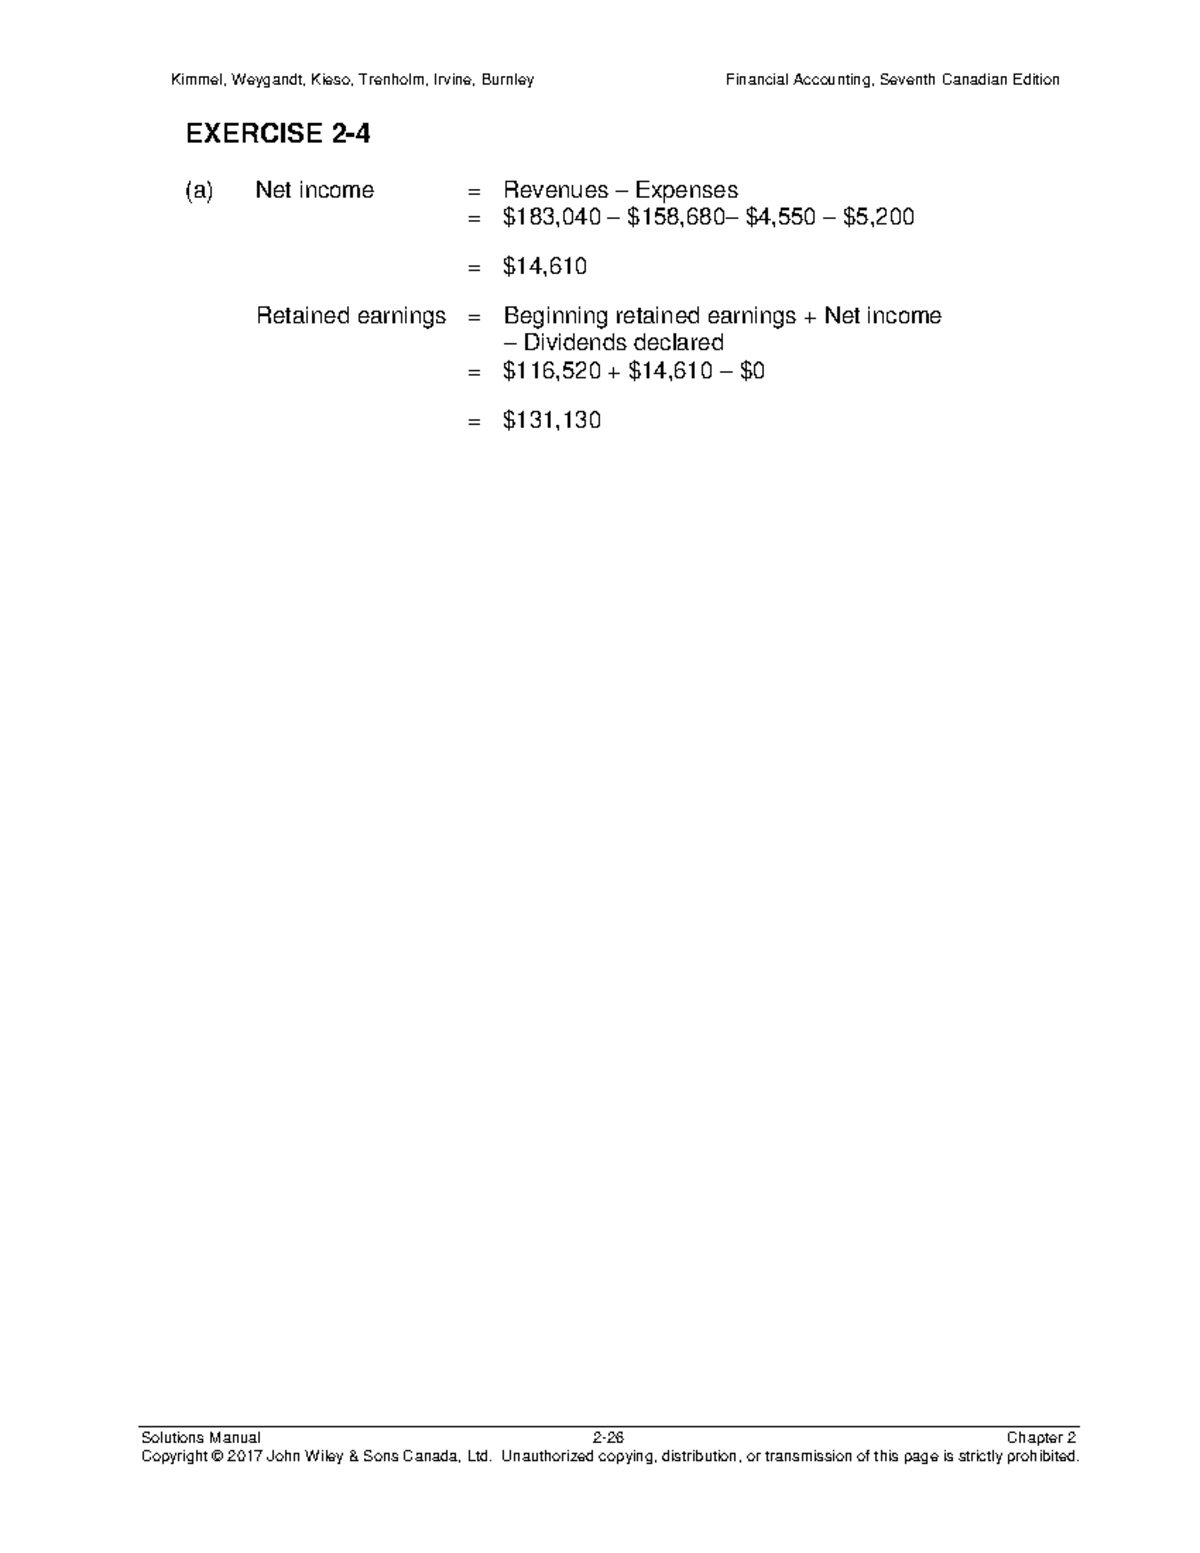
Here's something most students don't realize: net income in Chapter 2 isn't just revenue minus expenses. The classification matters. Operating versus non-operating items, gains versus losses, recurring versus one-time events—these distinctions affect how the number is interpreted. A problem might include a gain on sale of equipment alongside regular sales revenue. If you lump them together without separating them, your net income figure is technically correct but your income statement presentation is wrong. Some professors deduct points for that. Others build bonus questions around it. Another counter-intuitive point involves the relationship between the balance sheet and the income statement at this stage. Net income flows into retained earnings. If your net income is wrong, your equity section is wrong too. When you check your answer key, verify that your balance sheet balances. If assets equal liabilities plus equity, you've probably got the net income number right. If it doesn't balance, you've made an error somewhere, and it's usually traceable back to a missed adjustment. There are limitations to relying on answer keys. They won't help you if your fundamental misunderstanding is about the accrual basis itself. I had a student once who got every adjusting entry backward. He was reducing asset accounts when he should have been increasing them, and vice versa. The answer key showed the right numbers, but he couldn't figure out why his debits and credits were flipped until we went through the T-account method together. If you're stuck in that position, comparing your work to the key alone won't unstick you. You need to go back to the source material and re-read the section on accrual accounting before the key becomes useful.
Some answer keys also simplify problems in ways that don't reflect real exams. They might present a single adjustment per problem when the actual test has three or four combined. If you only practice with the simplified version, you'll be caught off guard by the complexity. Look for answer keys that show full adjusting journal entries, the adjusted trial balance, the income statement, and the statement of retained earnings in sequence. That sequence mirrors what exam questions usually require. If you're working through this chapter right now, here's a practical routine that takes about 45 minutes per problem set. Attempt the problems without the key. Check your work. Open the key. Identify where you diverged. Redo the problems you got wrong, this time writing out the T-accounts. Then attempt one extra problem from the textbook that wasn't in the original set. This process usually gives you a clearer picture of your weak spots than re-reading the textbook alone. The answer key is a tool, not a crutch. Use it to calibrate your understanding, not to validate your effort without doing the work. The problems in Chapter 2 build directly on whatever comes next in the chapter sequence, and the gaps you leave now tend to show up as confusion later.