Why Chapter 2 Tests Feel Harder Than They Should Be
Chapter 2 in most introductory accounting courses covers the accounting equation, journal entries, T-accounts, and the basic flow of transactions through the ledger. It sounds simple on paper. The test itself is where students usually get tripped up. Not because the concepts are difficult, but because the questions are written to exploit gaps in how people actually understand debits and credits beyond memorization. I've watched students who could recite "debits equal credits" all day fail a single question that asked them to record a purchase of supplies on account. The problem isn't the rule. The problem is they never learned to visualize what actually happens to each account when a transaction occurs.
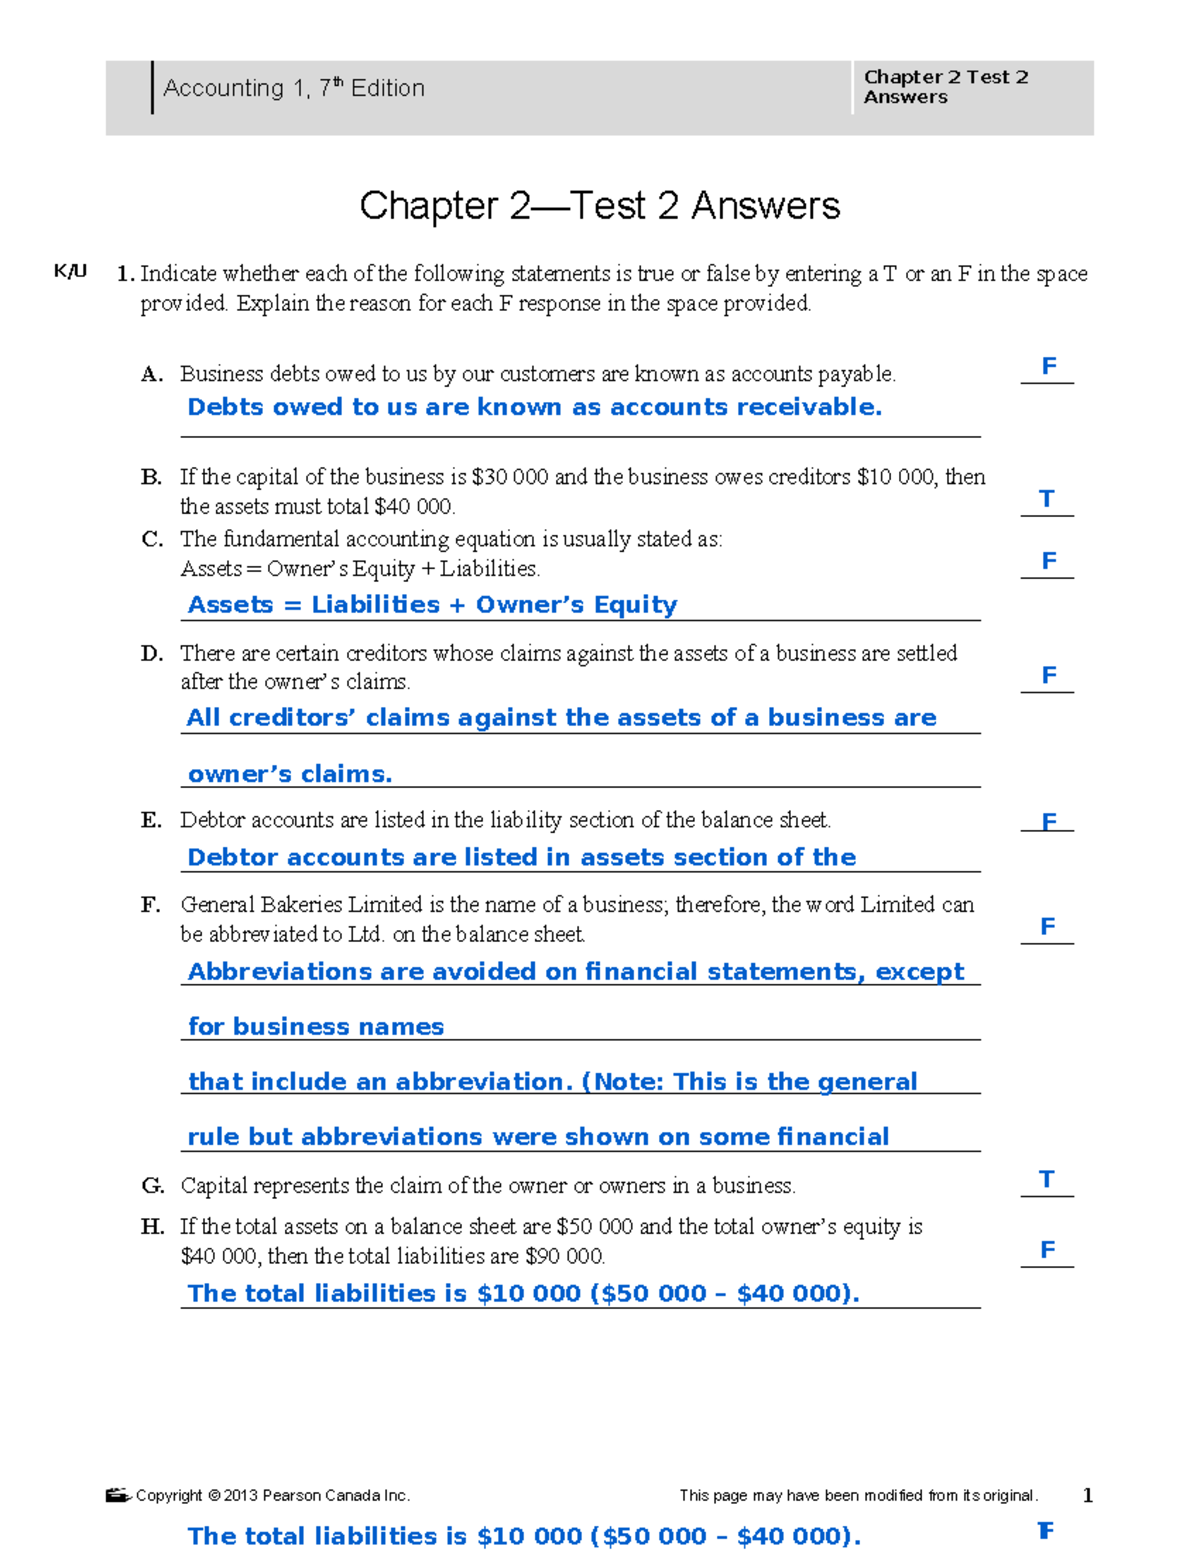
Chapter 2 Test A Accounting Answer Key
If you're looking for an answer key for your Chapter 2 Test A, the standard ones typically cover these topic areas: identifying increases and decreases in assets, liabilities, and owner's equity; recording journal entries from transactions; posting to T-accounts; preparing a trial balance; and sometimes basic adjusting entries depending on the textbook edition. Common question formats include multiple choice on account classification, journal entry exercises with transactions like owner investments, revenue earned on account, expenses paid in advance, and cash withdrawals by the owner. Here's what most answer keys won't tell you. The trial balance section is where the real filtering happens. Professors love to include one transaction that looks like it belongs in the cash column but actually affects an accounts receivable or prepaid account. Students who just match numbers without reading the full transaction description lose points there every semester. I remember one student, about three years ago, lost two full points on a test because he recorded a $500 payment to a supplier as a debit to Cash instead of Accounts Payable. The transaction said "paid on account." He saw the word "paid" and his brain auto-filled Cash. It's a real pattern. I started having students read every transaction aloud before writing a single entry, and the error rate dropped significantly. The second counter-intuitive thing most beginners miss is the direction of the entry. People memorize that assets increase with debits and liabilities increase with credits. But they don't internalize that the opposite side of every transaction carries the mirror entry. If you debit Supplies $300, you have to credit something $300. If you can't identify what gets credited within five seconds, you're guessing, not solving. I had a rule in my sessions: if you can't name both sides of the entry before picking up a pencil, you don't start writing. It feels slow at first. It saves more time than you'd think once you're under test pressure.
Another edge case that shows up on Chapter 2 tests involves transactions that affect more than two accounts. A single journal entry might require one debit and two credits, or vice versa. The textbook examples in the chapter are almost always simple two-account transactions, but the test will include at least one compound entry. I encountered this repeatedly. Students would split it into two separate entries instead of one compound entry, and while the net effect on the accounts is technically the same, professors mark it down because the instructions specify "record each transaction as a journal entry," singular. The workaround is straightforward. Count the number of accounts affected before you write anything. If it's three or more, it's a compound entry. You don't need a special rule for it. You just need to write it as one entry with the appropriate debits and credits balancing to the same total. There's also the issue of adjusting entries that some editions sneak into Chapter 2. If your version covers prepaid expenses or accrued revenues at the end of the chapter, you need to understand that these aren't regular transactions. They're corrections made at period end to bring account balances up to date. The adjusting entry for prepaid rent, for example, moves the portion of rent that has been used from an asset account to an expense account. Students routinely credit the expense instead of the asset. The logic is backwards because they're thinking about what they "used up" rather than what remains. I found that framing it as "what's left on the balance sheet drives the adjustment" instead of "what was spent" reduces errors noticeably. If you're using this answer key to check your work, don't just look at whether your final numbers match. Look at the account titles, the order of debits and credits, and whether compound entries are structured correctly. The difference between a partially correct answer and a fully correct one often comes down to formatting details that automated grading systems catch but human graders might overlook. On a practice test I set up, I deliberately included an answer that had the right numbers but swapped the debit and credit columns. It looked perfect at a glance and failed the moment you checked the mechanics.
Get the Full Details

The main limitation of relying on an answer key alone is that it doesn't teach you to catch your own mistakes. When you check your work against the key, you tend to skim and assume you got things right unless a number is clearly wrong. That means you miss structural errors like reversing debits and credits that still balance mathematically. I recommend covering the answer key and redoing each problem from scratch after checking your first attempt. It takes longer, but it actually reveals what you know versus what you guessed. For those preparing for the test, focus your practice on transactions involving owner's equity, especially drawings and capital contributions. Those are the ones students consistently mess up because they forget that the owner's equity section has its own debit-credit rules that operate differently from assets. A withdrawal by the owner is a debit to the Drawing account, not a credit. It reduces equity, which means it behaves like an expense in terms of the debit side, even though it's not technically an expense. That distinction matters on the exam. When you put together your study session, don't rush through the journal entries. Write each one out fully. Then post them to T-accounts. Then build the trial balance from the T-accounts. If your trial balance doesn't balance, go back and trace the error account by account. This sequence mimics what the test actually expects and builds the muscle memory you'll need when time is tight.
The Chapter 2 Test A Accounting Answer Key you find online or in your course materials will vary slightly depending on the textbook edition and the professor's customization. The core problems stay the same, but the dollar amounts and transaction details change. Make sure the key you're using matches your version. Using a mismatched key will waste more time than it saves because you'll be checking answers against wrong numbers and confusing yourself. If you're stuck on a particular problem, the most effective approach is to write out the accounting equation with the transaction written above it. Assets = Liabilities + Owner's Equity. Then ask yourself which side of the equation the transaction affects and by how much. From there, the debit and credit follow naturally instead of requiring you to remember a rule by heart. This method works consistently across all the standard Chapter 2 question types and is especially useful for the trickier compound entries and adjusting transactions.