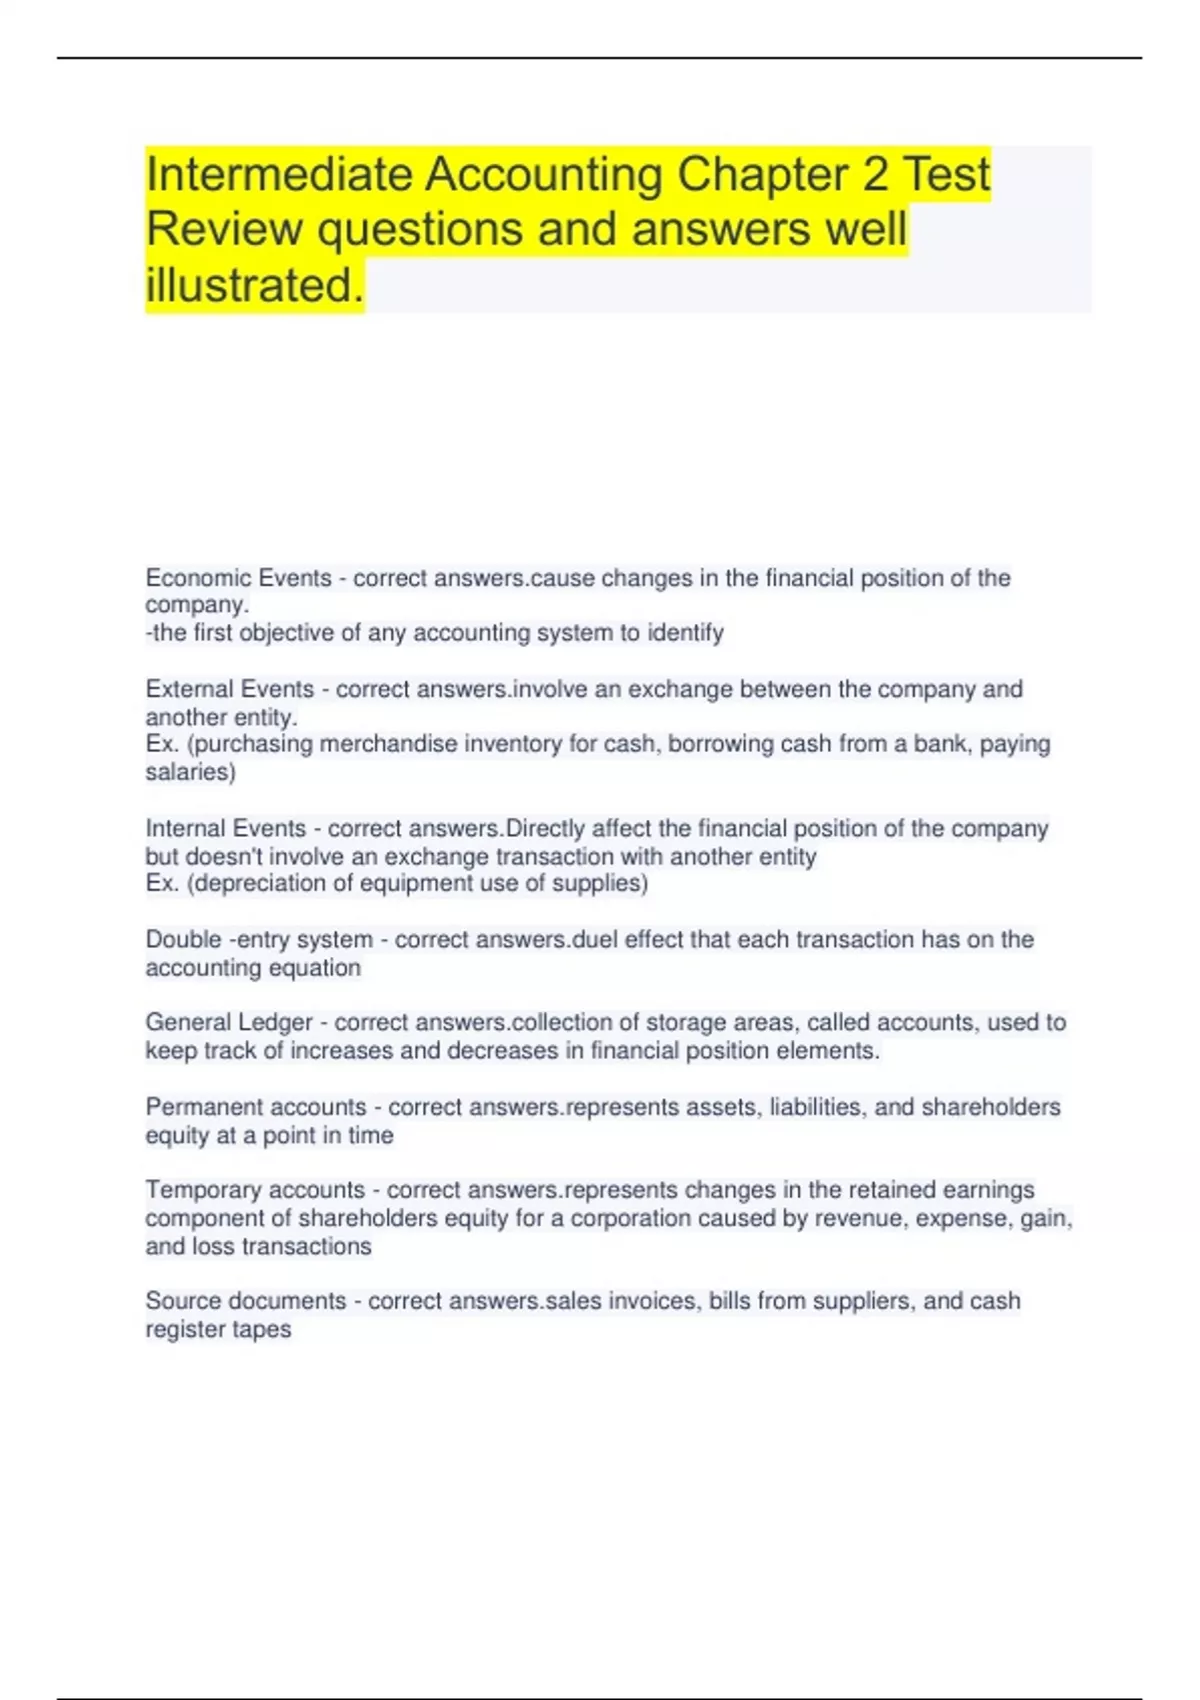
What This Chapter Actually Covers
The second chapter in most introductory accounting courses deals with the adjustment process and the preparation of financial statements. That means you will encounter adjusting entries for prepaid expenses, unearned revenues, depreciation, accrued wages, and accrued revenues. After those entries are made, you build an adjusted trial balance, then move on to the income statement, retained earnings statement, and balance sheet. Test B versions of these exams typically mix computational problems with conceptual multiple-choice questions. You need to know both how to make an entry and why it goes where it does. I have graded enough of these midterms to know where students consistently lose points. The biggest one is mixing up which account gets debited and which gets credited when recording the expiration of a prepaid asset. Another common failure is forgetting that the income statement must be completed before you can finish retained earnings. The numbers depend on each other in sequence.
Where to Find the Chapter 2 Test B Accounting Answer Key
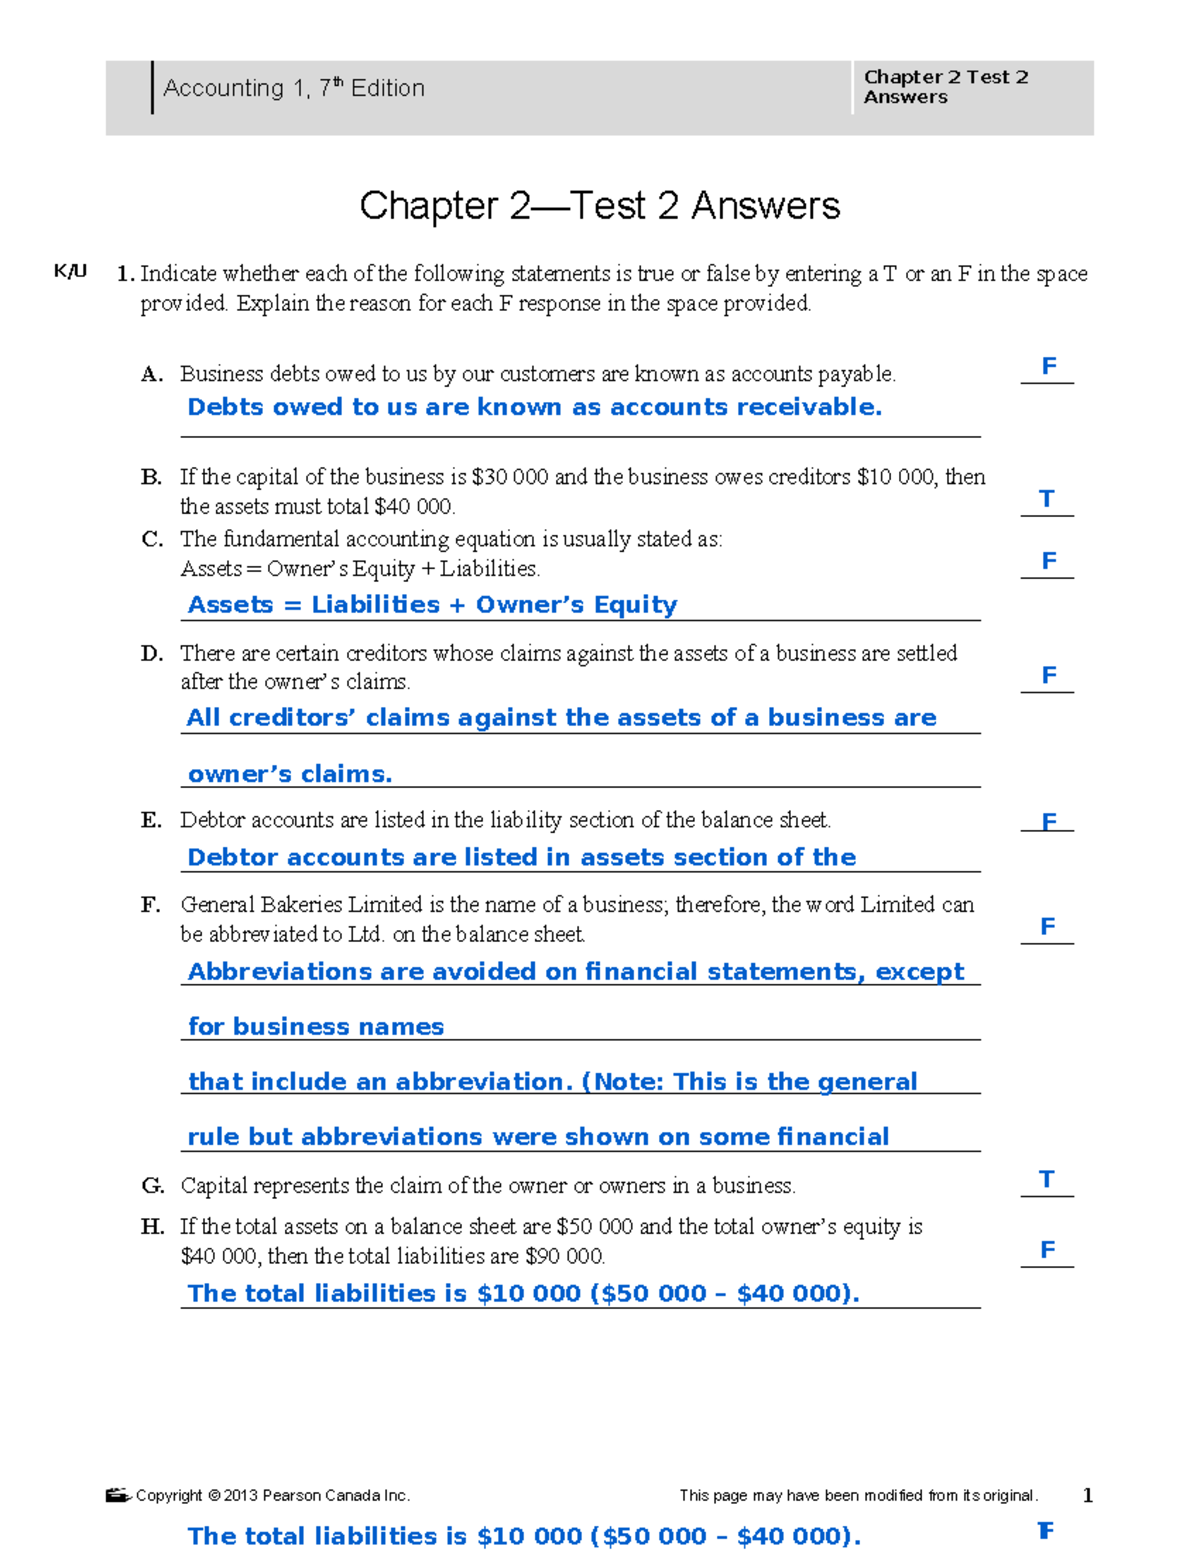
The official answer key for Chapter 2 Test B depends entirely on which textbook your professor is using. If your course follows Financial Accounting by Libby, Libby, and Hodge, the Test Bank for Chapter 2 includes a set B with its own solution guide distributed through the publisher's instructor resources. McGraw-Hill's Connect platform also provides access to completed problem solutions for chapter two quizzes and exams. Cengage has a similar structure through its MindTap system. None of these are freely available to students without proper credentials. If your professor posts the answer key on Canvas or Blackboard, check there first. Many instructors include the solutions after the test deadline passes so students can review their mistakes. A few do not post them at all and instead share a scanned PDF through an external link on the course syllabus. When I ran a study group last semester, we compiled answers from the textbook's solution manual alongside what our professor released, and that combined document was the most accurate resource we had.
How to Work Through Adjustment Problems Correctly
Start by identifying whether the transaction involves a deferral or an accrual. Deferrals mean cash was exchanged before the economic event occurred. Accruals mean the economic event happened before cash changed hands. Prepaid insurance, supplies, and rent are deferrals on the asset side. Unearned revenue is a deferral on the liability side. Depreciation is technically a separate category but functions like an asset deferral because you allocate a cost over time rather than recognizing it all at once. When you calculate the adjustment amount, always work from the data given in the problem, not from assumptions. For example, if a company paid $3,600 for a twelve-month insurance policy on October 1st and the test date is December 31st, you recognize three months of expense. That is $900. The adjusting entry debits Insurance Expense and credits Prepaid Insurance. Students often reverse these two accounts or miscalculate the monthly portion. I once caught a student who divided the total by four quarters instead of twelve months and arrived at $2,700 instead of $900. The root error was treating quarterly reporting as the basis for the calculation rather than the actual time passed. Depreciation problems follow a straightforward formula: (Cost minus Salvage Value) divided by Useful Life. Straight-line method is what appears most often on Chapter 2 tests. If the problem states a van costs $42,000 with a residual value of $6,000 and a five-year life, the annual depreciation is $7,200. For partial years, prorate by the fraction of the year the asset was in service. A machine purchased on April 1st receives nine-twelfths of the annual amount, which comes to $5,400.
Get the Full Details
Common Pitfalls in Test B Format
Test B versions are usually designed to prevent cheating by varying the numbers while keeping the same structure as Test A. This means you cannot memorize answers from someone who took the earlier version. The conceptual questions may look identical, but the numerical problems will have different figures. You need to understand the underlying mechanics, not recall specific dollar amounts. One tricky edge case that shows up with some frequency involves the allowance for doubtful accounts. Students sometimes record the adjustment as a debit to Accounts Receivable and a credit to Allowance for Doubtful Accounts, which is backwards. The correct entry under the allowance method is a debit to Bad Debt Expense and a credit to Allowance for Doubtful Accounts. I saw a professor try this exact variation on a recent exam and roughly forty percent of the class got it wrong. The confusion comes from mixing up the write-off entry, which does involve Accounts Receivable, with the adjustment entry, which does not. Another frequent trap is the accrued revenue adjustment. When a company has performed services but has not yet billed the customer, the entry is a debit to Accounts Receivable and a credit to Service Revenue. Students frequently skip the receivable and credit directly to cash, which violates the accrual basis. Cash has not been received, so no cash account should appear in the entry.
Building the Financial Statements in the Right Order
Once all adjustments are posted, you move through the statements in a fixed sequence. The income statement comes first because net income calculated there feeds into retained earnings. The retained earnings statement then updates the ending balance, which flows into the balance sheet. The balance sheet must balance, and if it does not, the error is usually traced back to one of the prior statements rather than introduced during the balance sheet itself. When you prepare these from a trial balance, list your accounts in liquidity order for the balance sheet: assets from most liquid to least, then liabilities, then equity. On the income statement, follow the conventional format with revenues listed first, then expenses, then net income or net loss at the bottom. Keep your working papers neat. I have lost track of a correct solution before because I transferred a number from my scratch work to the final statement with a transcription error. Writing clearly matters more than it seems on a timed exam. If you are struggling with a particular problem type, go back to the basic journal entry form and walk through the transaction step by step. Do not jump straight to the financial statement. The adjustment entries are the bridge, and skipping that step guarantees mistakes downstream.