
What actually happens when you plan an audit using Chapter 8
Audit planning and analytical procedures aren't theoretical exercises. You sit down with a client's financials, spot the material misstatement risk before the fieldwork starts, and build an approach that targets where it actually matters. The chapter walks through risk assessment, materiality thresholds, and how to design analytical procedures that either confirm normal patterns or flag something worth investigating. Most people treat this like a checklist. It isn't. I remember working on a mid-market manufacturing client where the standard materiality calculation suggested a 5% threshold on revenue. That's textbook Chapter 8 stuff. But their revenue was lumpy — three large contracts drove sixty percent of annual sales. Running analytical procedures on total revenue masked everything. I switched to quarterly revenue by contract, compared year-over-year against shipping logs, and found a single contract that was recorded twice in Q4. A blind materiality application would have missed it entirely.
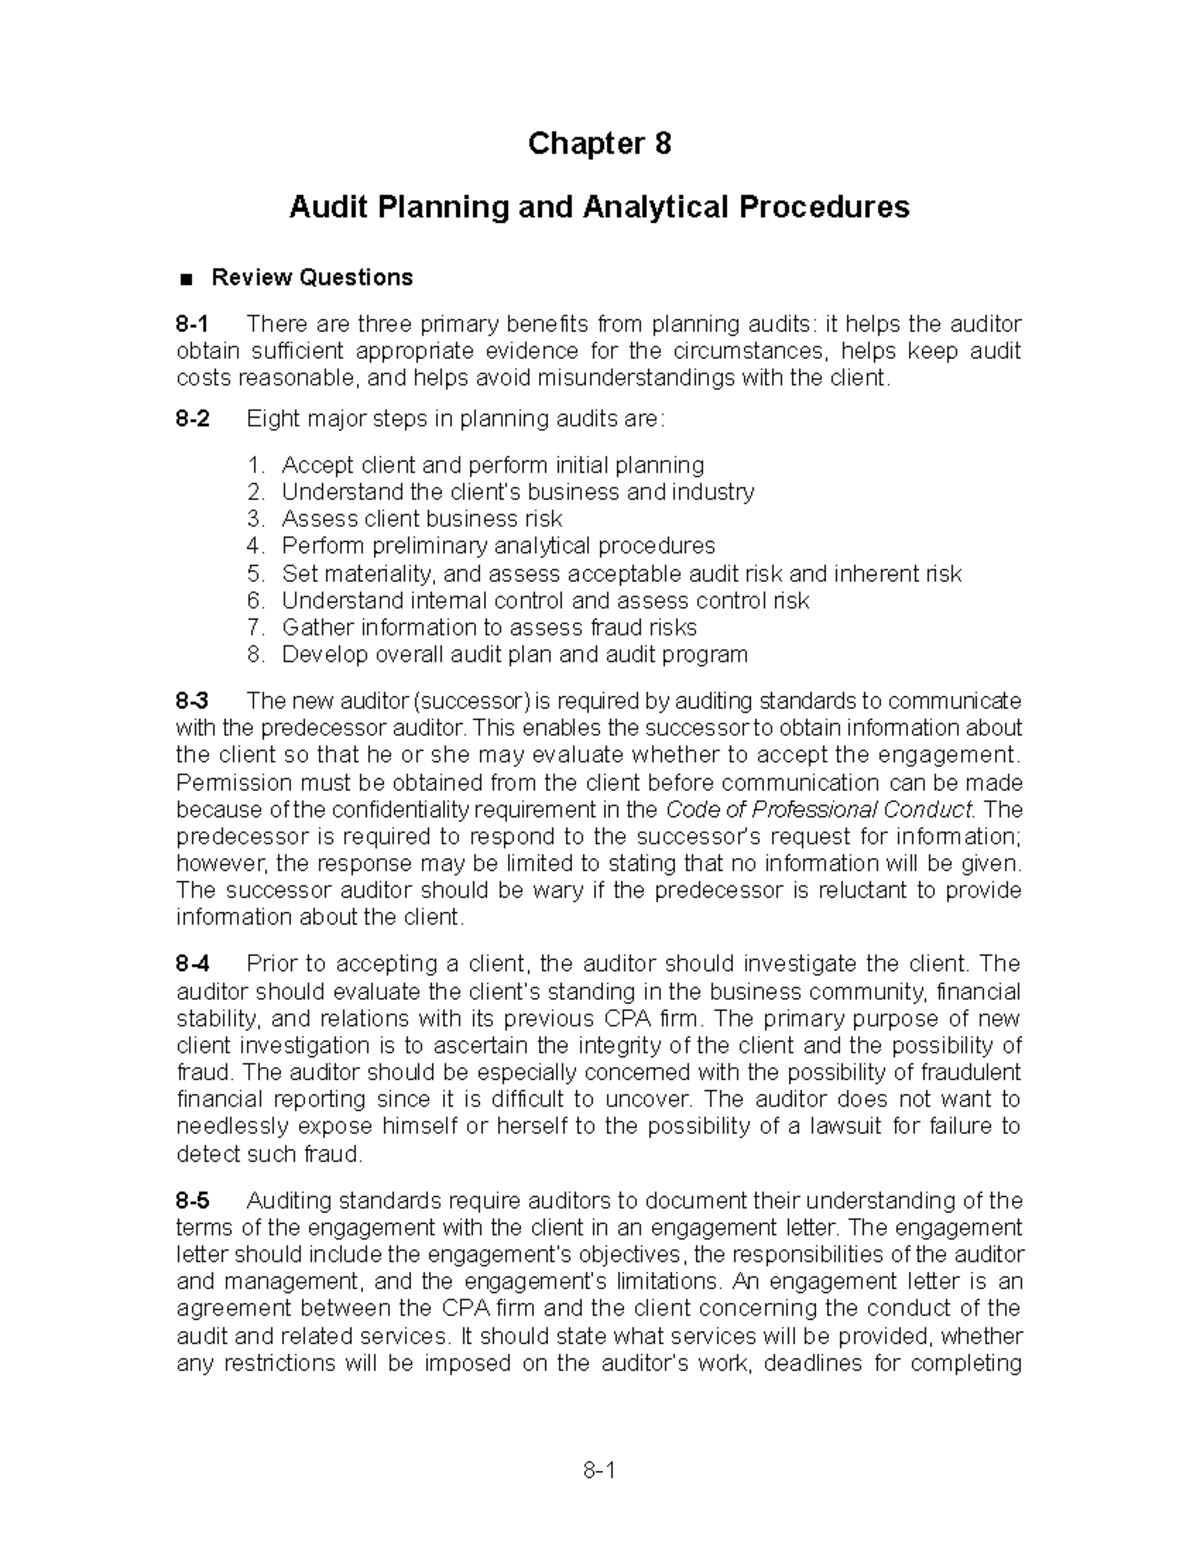
Chapter 8 Audit Planning And Analytical Procedures Solutions
Materiality needs to be set at two levels. Overall materiality drives the scope of the entire engagement. Performance materiality is the buffer you apply to individual accounts and transactions. Beginners often set them at the same number. That leaves almost no room for undetected misstatements. A typical performance materiality sits between 50 and 75 percent of overall materiality. The exact percentage depends on your prior year findings, the control environment, and whether management has a history of pushing estimates toward favorable outcomes. Analytical procedures belong in three distinct phases. Planning, substantive testing, and final review. Each phase uses them differently. During planning, you're looking for unusual relationships that suggest risk areas. During substantive testing, they serve as evidence. During final review, you're confirming that the financial statements as a whole make sense. I've seen auditors run detailed analytical procedures during substantive testing but skip the review stage entirely because they ran out of time. That's a gap. The review step catches aggregation errors that individual account testing never surfaces. The most useful analytical techniques are ratio analysis, trend analysis, and reasonableness tests. Ratio analysis compares relationships between accounts. Trend analysis looks at fluctuations over time. Reasonableness tests estimate what a figure should be and compare it to the recorded amount. A reasonableness test for depreciation might multiply the average fixed asset balance by the estimated useful life and the historical depreciation rate. If the resulting figure is off by more than your tolerable misstatement, you dig deeper.
Prior year comparatives matter more than most auditors use them. If an account balance shifted twenty percent year-over-year and management can't point to a specific transaction or event that caused it, that's a red flag. But the inverse is also true — stability can be a red flag. If revenue grew steadily for five years and then flatlined exactly when management's bonus structure kicked in, the pattern itself is suspicious. I once flagged a client's inventory balance because it hadn't moved in eighteen months despite a stated shift in product lines. Turns out the warehouse manager had stopped updating the perpetual system. Here's a nuance beginners consistently miss. Analytical procedures don't require perfect data. They require data that's relevant and reliable enough for the purpose. If you're using a high-level trend to identify risk areas, approximate figures are fine. If you're using analytics as substantive evidence, the underlying data needs to be more carefully validated. The standard distinguishes between these two uses, and the precision you apply should match the reliance you place on the results. There are real limitations to analytical procedures. They detect anomalies, not fraud directly. A well-executed fraud scheme will look analytically normal because the fraudster adjusts multiple accounts to maintain believable relationships. Analytical procedures are also sensitive to the quality of the client's financial data. Garbage in, garbage out applies here just as much as anywhere else. If the client's ERP system reclassifies expenses monthly or has duplicate entries baked into the general ledger, your ratios will look wrong even when everything is fine.
Get the Full Details
When analytical procedures produce unexpected results, the standard expectation is that you investigate. But investigation doesn't mean opening every transaction. It means narrowing the scope to high-risk items and then drilling down only where the evidence points. In practice, I typically respond to an unexpected variation by first confirming the data integrity, then comparing the variation to non-financial information, and only then moving to transaction-level testing. Each step eliminates a category of possible causes without diving into the ledger immediately. Documentation is where most Chapter 8 compliance fails. You need to record what you expected, what you actually found, and why the difference matters. Not just the conclusion, but the reasoning. I've had review partners send engagements back because the analytical procedure documentation showed only the final number and a checkmark. There was no explanation of the expectation, no basis for the tolerance range, and no discussion of the investigation when the numbers diverged. That documentation doesn't hold up under review. The most practical approach I've found combines a preliminary analytical procedure at the planning stage with a final review analytical procedure at the reporting stage. The first identifies risk areas and shapes your substantive testing strategy. The second provides a reality check before you sign off. Between those two, you can run supplementary analytical procedures on specific accounts that need additional evidence. This three-layer structure keeps the engagement efficient without cutting corners on coverage.
For anyone looking for worked examples or a structured approach, there are resources available that walk through Chapter 8 requirements with actual financial data. These can be useful for building your own analytical framework or understanding how the procedures translate into fieldwork. The solutions you find online should supplement your professional judgment, not replace it. Each engagement has its own risk profile, and no template accounts for that.


