
Getting the Most Out of the Charlie Rose Interview Warren Buffett
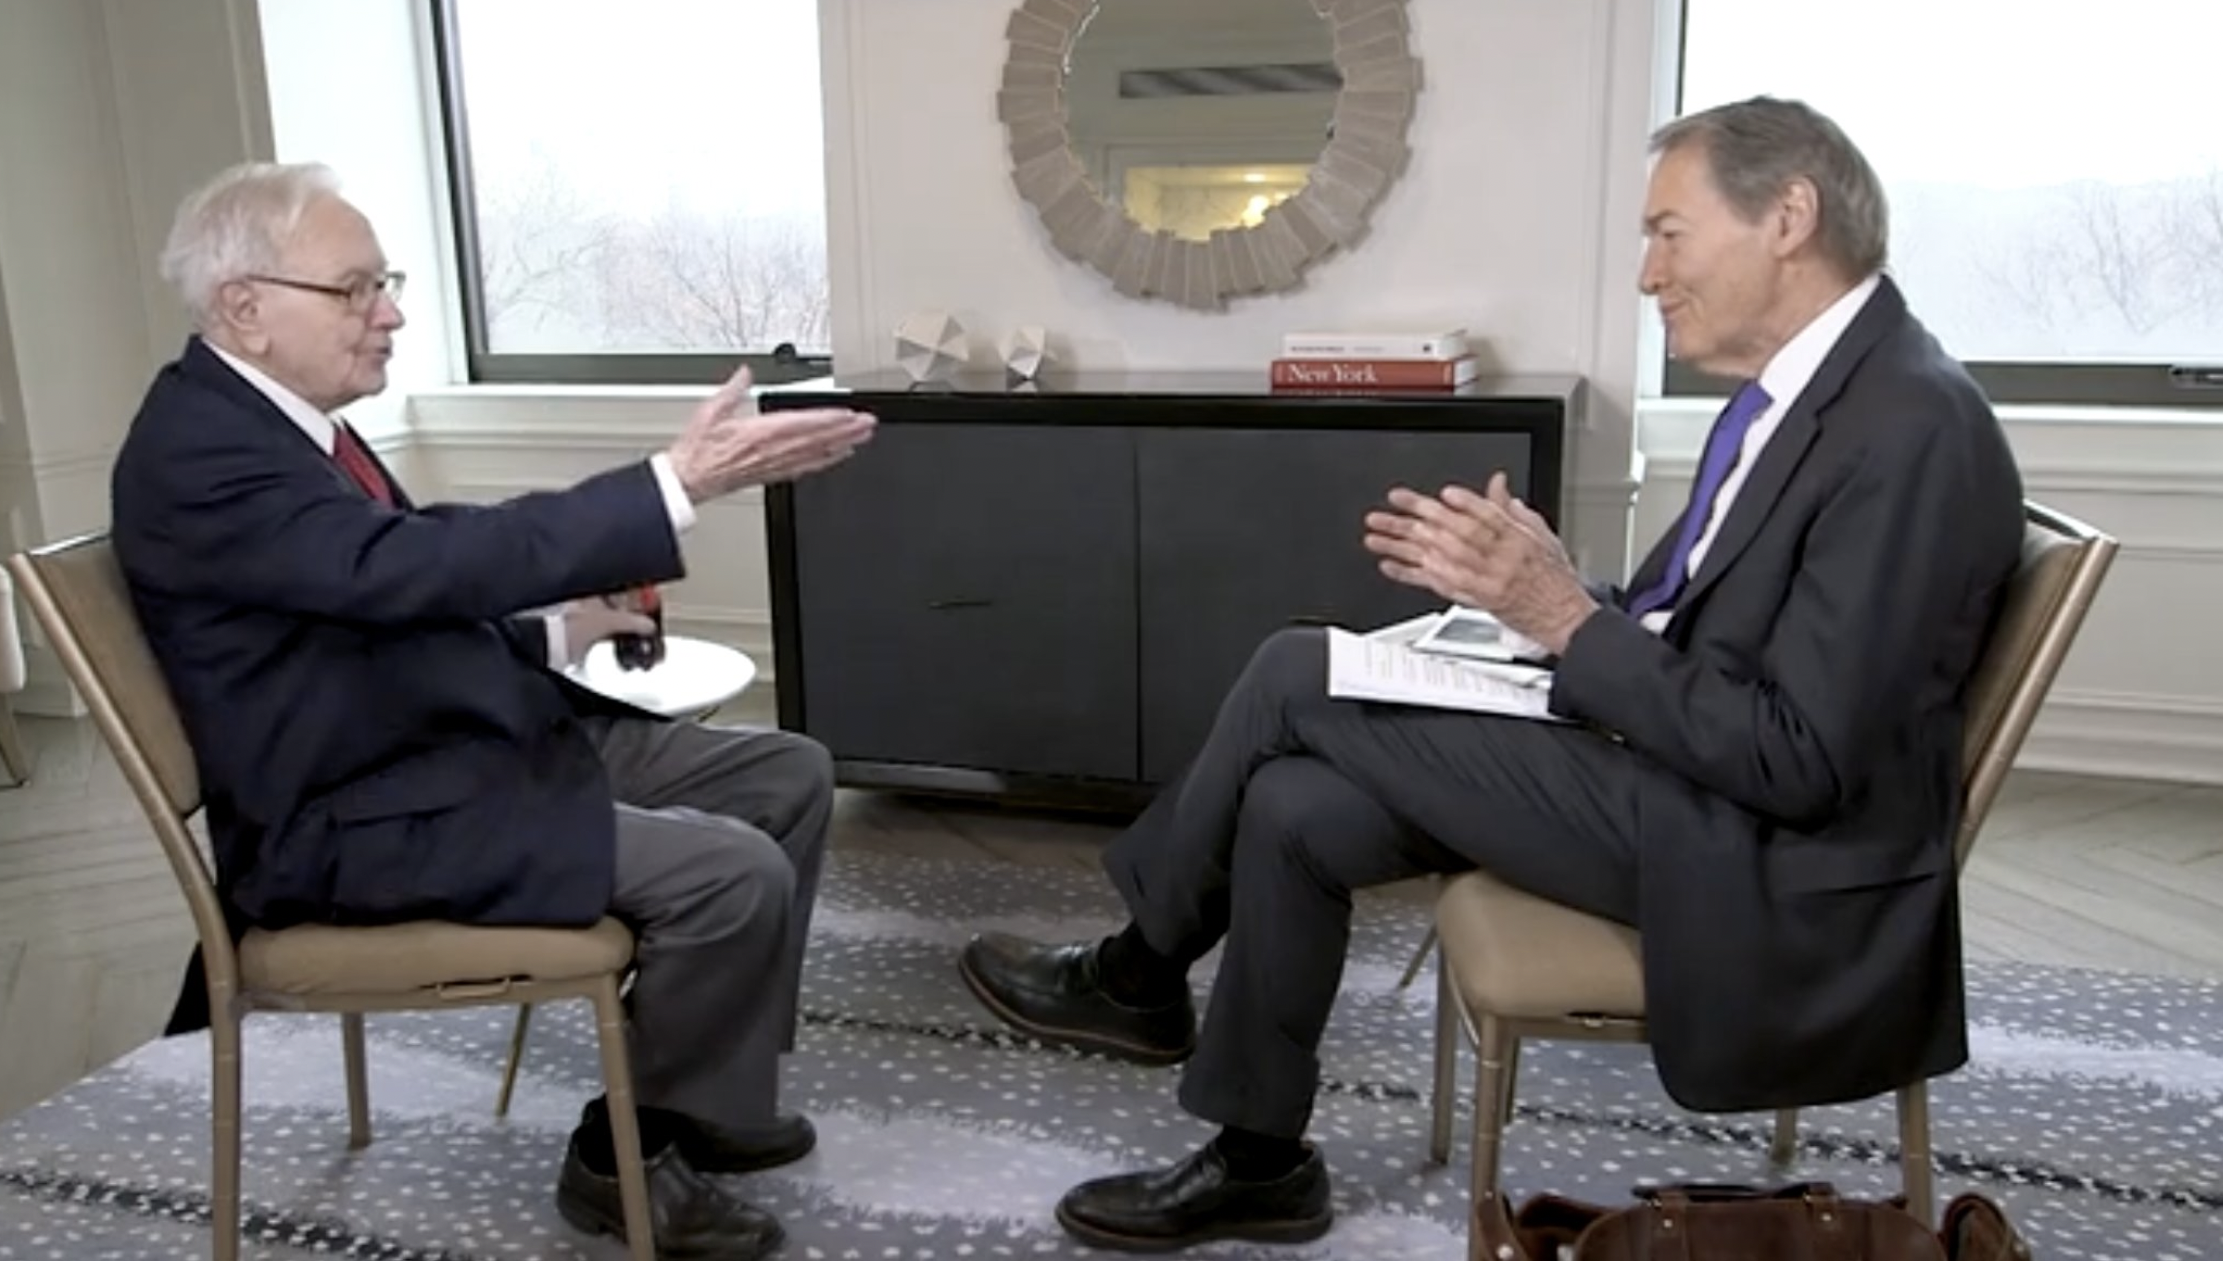
The 2007 Charlie Rose interview with Warren Buffett remains one of the clearest windows into how a lifetime investor actually thinks about capital allocation, competitive moats, and behavioral discipline. I have watched it repeatedly over the years and still pull specific talking points from it during deal evaluations. The raw footage runs about two hours, but the useful material is concentrated in three segments. I will walk through what to watch, how to take notes, and where people usually waste time.Where to Find the Charlie Rose Interview Warren Buffett Full episodes are archived on the Charlie Rose channel on YouTube. CBS also holds clips on their website. Search for "Charlie Rose Warren Buffett 2007" or use the direct archive URL if you already have it. There are shorter edited versions online, but they strip out the Q&A about hedging and insurance float. Watch the complete uncut episode.
I once spent an afternoon trying to transcribe the insurance discussion because I needed a specific quote about combined ratio targets. The YouTube comments had a few partial transcripts floating around, but they were wrong on the numbers. I just rewound and paused every thirty seconds. It took about forty minutes to get a clean copy. I keep my own notes in a simple text file with timestamps.
What the Interview Actually Covers
Buffett does not present a formal lecture. He answers questions and digresses when something catches his attention. The structure is loose. The content is dense.He talks about buying businesses, not stocks. He explains the difference between a circle of competence and stubbornness. He gets blunt about index funds for most people. He describes how he evaluates management teams. He touches on market crashes without romanticizing them. He also gives away almost nothing about specific tickers.
The Moats Section
The part about economic moats is the most quoted segment. Buffett lists pricing power, switch costs, and network effects as the main structural advantages. He says most companies have soft moats that erode quietly. I have seen this play out in industrials where a customer contract looked stable until a single line item in the renewal terms shifted the balance. The interview does not go that deep, but the principle is the same.You should note his distinction between durable and temporary advantages. Durable means the business can raise prices above inflation without losing volume. Temporary means the advantage exists today but requires constant capital reinvestment just to stay in place. He uses examples like See's Candies and Berkshire Hathaway's railroads.
Get the Full Details
The Management Test
Buffett describes a simple test for whether a manager is trustworthy. He asks what they would do if they suddenly owned the entire business and could not sell it. If the answer sounds like a person who would cut research or defer maintenance, you have your answer. I use this filter when reading annual letters from mid-cap companies. It catches more spin than the actual numbers sometimes.The interview shows Buffett applying this casually. He does not build a whole framework around it. He treats it as basic hygiene. That is why the section feels almost too simple. It is. Most investors skip hygiene.
How to Study the Interview Efficiently
Do not watch it like a movie. Watch it like a reference. Here is the process I use.First, run the episode while listening without pausing. You will get the general shape. Take no notes yet. Second, go back through the three key sections: moats, management, and capital allocation. Pause every few sentences. Write down the timestamp and the core idea in one line. Third, pull a blank sheet and rewrite each idea in your own words. If you cannot explain it without using Buffett's exact phrases, you have not internalized it yet.
Timestamps That Matter
The moat discussion starts around the forty-minute mark. The management segment begins near hour one. The capital allocation portion runs from about one hour ten minutes to one hour forty minutes. I skip the jokes in the middle because they do not transfer to your work. I also skip the repeated index fund endorsement because he already made the point clearly.One practical tip: use the YouTube playback speed slider. Set it to 0.75x for the first pass. It slows him down enough that you can catch the hedging discussion without losing the flow. I know some people hate speed adjustments, but this is one case where it helps.

Common Pitfalls When Reading the Interview
Most people treat Buffett's answers as universal truth. They are not. They are reflections of a specific balance sheet, a specific time period, and a specific organizational structure. Berkshire Hathaway can buy a whole railroad and hold it for a century. A retail investor cannot. The lesson is about thinking in decades, not about copying the moves.Another trap is focusing on the tickers he mentions. He names a few companies, but the point is the business model, not the symbol. I have seen too many people memorize See's Candies and forget the pricing power mechanism. That is backward.
What the Interview Does Not Tell You
Buffett does not discuss derivatives in detail during this conversation. He hints at them. He does not give a tutorial on credit default swaps. If you need that, look elsewhere. He also avoids talking about macro timing. He says he does not predict rates or GDP. The interview will not save you from a bad entry price. It will only help you pick better businesses.I learned this the hard way during the 2008 stress. I tried to apply the interview's logic to a financial name that looked cheap. It was cheap for a reason. The moat was a regulatory convenience, not an economic one. The interview would have helped me avoid that mistake if I had focused on the durability test instead of the price.
Practical Exercises to Lock in the Material
After the first full watch, pick one public company you already understand well. Write a two-paragraph moat assessment using only ideas from the interview. Do not add outside frameworks. If you cannot find a clear answer to the pricing power question, note that as a risk. Then rewatch the moat segment and check your work. Most people miss something on the first pass.I do this once a quarter. It takes about an hour. It keeps me from drifting into buzzword compliance. The interview is not a substitute for actual analysis. It is a lens.
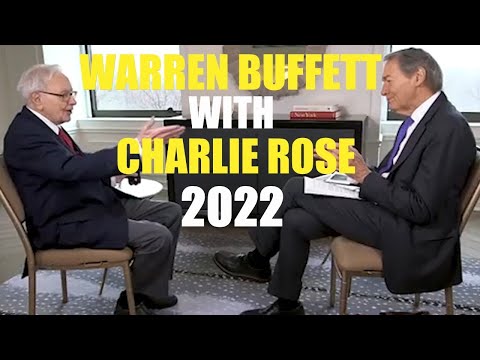
Downloading and Saving the Episode You can download the full episode through the Charlie Rose archive. Some mirrors are unreliable. I prefer the official YouTube VOD or the CBS archive link. Save the video in your local drive if you watch it often. I keep mine in an MP4 folder with a simple naming convention: date-interviewee-topic.mp4. This prevents the "where did I put that file" problem.
If you need subtitles, YouTube's auto-captions are decent for this episode. I use them to double-check quotes, not to replace listening. The captions miss some of Buffett's softer murmurs. Pausing is still the best method for those lines.
Why This Interview Still Matters
It matters because Buffett is unusually clear about things most investors never discuss. He does not dress up the answers with jargon. He says what he means. The interview captures that tone. I return to it when I feel pressure to overcomplicate a simple decision. It grounds me.That is the main takeaway. The interview will not hand you a checklist for stock picks. It will give you a clearer standard for evaluating businesses. If you apply that standard consistently, you will make fewer mistakes. Mistakes are the real cost. The upside tends to take care of itself.


