The accounting side of a landscaping business is where most guys quietly lose money
You've got a great crew, reliable customers, and you're good at what you do on the job site. That's half the battle. The other half is whether your books actually tell you where your profit is going, or whether you're flying blind until tax season hits and you have no idea if you're running a profitable business or just working really hard for no money. I set up my first Chart Of Accounts For Landscaping Business back when I was running a six-crew operation, mostly because our bookkeeper quit in the middle of a fiscal year and we spent three weeks trying to reconstruct expenses from receipt photos. Since then I've built out these charts for a dozen other operators. Here's how it actually works in practice, not the sanitized version from the textbooks.
Chart Of Accounts For Landscaping Business: What You Actually Need
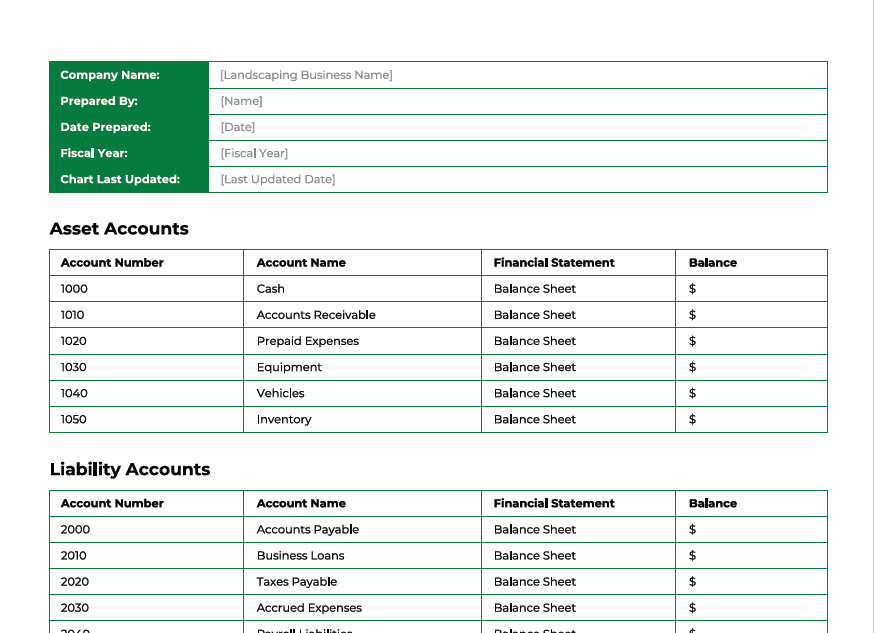
Let me walk through the structure before anything else, since that's what people usually mess up. Most landscapers either throw everything into generic buckets or create way too many accounts they never use. Both are wrong. Assets (What you own) Current assets include checking and savings accounts, accounts receivable from commercial contracts, and fuel cards. Equipment inventory goes as a fixed asset, including trucks, trailers, mowers, trimmers, blowers, and dump trucks. Each piece of heavy equipment should have its own account with a separate accumulated depreciation line. I don't recommend lumping all equipment into one account because when you're pulling a P&L for a specific job, you need to know exactly how much machine cost went into it.
Liabilities (What you owe) Accounts payable from suppliers, credit cards, and any lines of credit. Equipment loans and vehicle loans are separate accounts — not combined. Sales tax payable is its own account too. If you carry payroll taxes, that's another distinct liability. I've seen operators combine sales tax and payroll into one line and then wonder why their quarterly filings never match their records. Equity (Your ownership stake)
Get the Full Details
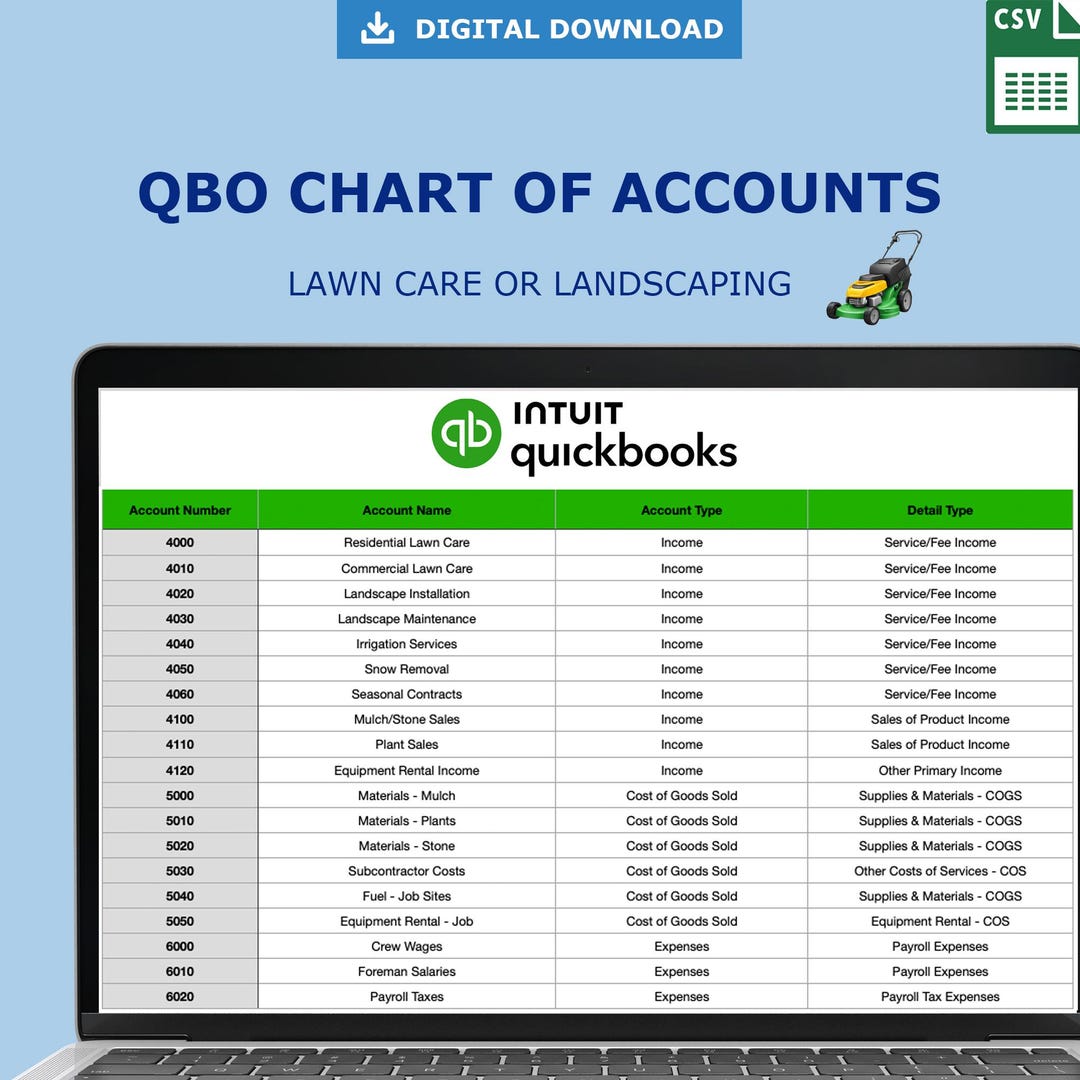
Owner capital contributions, owner draws or distributions, and retained earnings. If you have partners, each gets their own capital account. Don't skip this — it matters when you're doing anything more complicated than a sole proprietorship filing. Revenue (Money coming in) This is where people get sloppy. Split your revenue into at least five accounts: Lawn maintenance, hardscaping, seasonal cleanups, tree services, and design/consulting fees. Commercial contracts should be tracked separately from residential because the margin profile is completely different. Residential lawn care might net 25%. Hardscaping can run 40 to 50 percent if you're doing it right. If you roll everything into one revenue line, you literally cannot tell which service makes you money and which one is losing you money on every job.
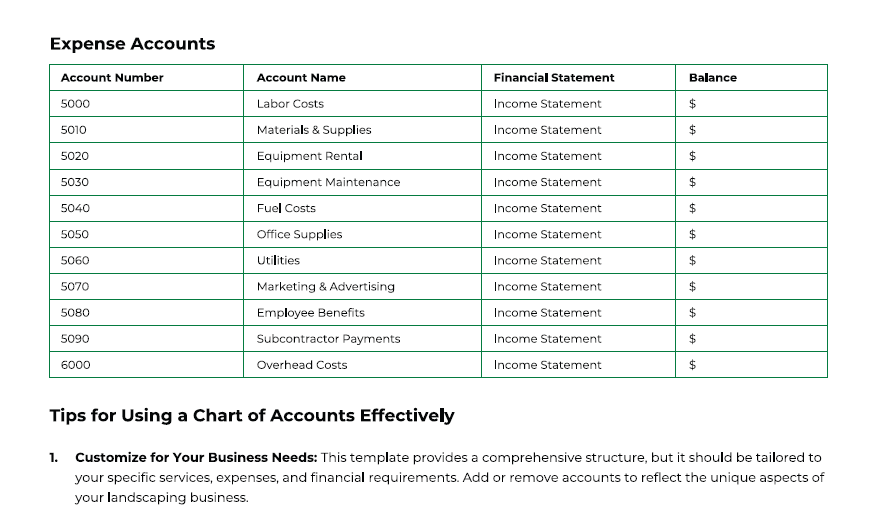
Cost of Goods Sold This is the section that actually determines your gross margin. Materials — mulch, stone, sod, plants, pavers, lumber. Labor — hourly wages for field crews, loaded with burden. Subcontractor costs. Equipment fuel and oil, which belongs in COGS, not overhead. Permits and disposal fees if they're job-specific. Every direct cost tied to a deliverable goes here. If you're not tracking COGS by job, you're operating a landscaping business at best and a hobby at worst. Operating Expenses
Office salaries, insurance, software and accounting, vehicle repairs, marketing and advertising, permits and licenses, professional fees, rent or lease on yard space, and cell phones. These are your periodic expenses that don't tie directly to a single job. The distinction between COGS and operating expenses is important for tax purposes and for understanding your true gross margin. Here's a concrete example of what I mean. I had a guy last year who was asking why his net profit was 8 percent when he thought he was making 25. His problem was that he was putting all his equipment repair costs into operating expenses instead of allocating them to the jobs that used the machines. He'd mow a $4,000 hardscape project with a $600 mower repair in the same month but expense it to the general bucket. When I traced it back and moved those repairs to the right job codes, his actual gross margin on hardscaping dropped from 42 percent to 28 percent. He was giving away 14 points of margin without knowing it.
How to Set This Up in Practice
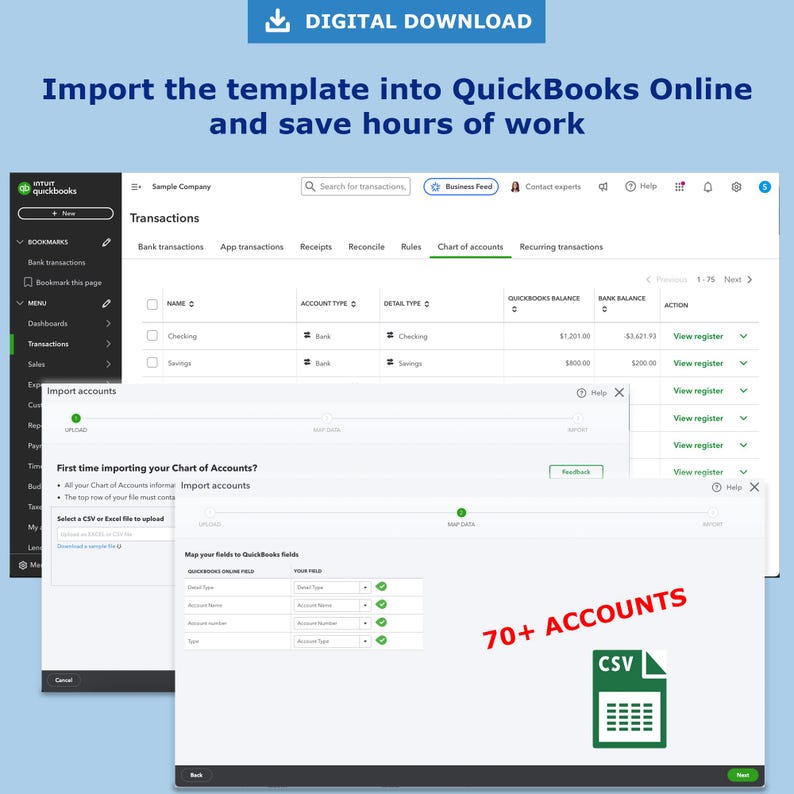
Start by opening your accounting software and creating the account structure from top to bottom. I use QuickBooks Online for most of my operations, Enterprise tier if we're tracking more than three service lines simultaneously. QuickBooks is fine for basic needs but lacks real job costing without a plugin or upgrade. If you're doing more than 50 jobs a year, the standard version will frustrate you within three months. Create the revenue accounts first, then COGS, then the asset and liability sections, and finish with operating expenses. That order matters because it forces you to think about where money comes in before you start categorizing where it goes out. Your chart of accounts isn't just a filing system. It's the skeleton of your entire financial operation. Use classes or locations if your software supports them. I run one class per service line — lawn care, hardscaping, seasonal cleanup, tree work. This doesn't replace proper job costing but it gives you a quick secondary view of profitability across service types. A lot of operators think classes are optional. They're not. Classes are what let you answer the question "did we make money on tree work last quarter?" in under ten seconds instead of digging through hundreds of transactions.
Here's the detail that most people miss: create sub-accounts under your main categories rather than listing everything at the top level. Under equipment, instead of one account called "Equipment," create individual accounts for trucks, mowers, trimmers, and blowers. You will not believe how useful this becomes when you're depreciating assets and comparing replacement cycles. In my experience, mowers get replaced every four years, trucks every seven to ten, and trimmers every three. Knowing the difference requires separate accounts, not a lump sum. I ran into a specific problem about two years ago with a landscaping client who had a fleet of twelve trucks. We'd been tracking all vehicle costs in a single account called "Trucks and Trailers." When the state audited us on a property tax assessment, they wanted depreciation schedules for each individual vehicle. We didn't have them because we'd never separated the accounts. It took me a full weekend to reconstruct the purchase history and allocate costs to the right vehicles. Never let that happen to you. Track every vehicle separately from day one. One more thing about labor accounting. Your field labor should be split into direct labor and indirect labor. Direct labor is what you pay the crew working on a specific job. Indirect labor is what you pay for estimating, project management, cleanup crews, and admin time. Put both in COGS but keep them separate so you can see whether your overhead is creeping up on a per-job basis. I've seen small landscaping companies where indirect labor grew from 12 percent to 34 percent of total labor cost over two years and nobody noticed because the accounts were merged.
When This Breaks Down
A chart of accounts is only as good as your discipline in using it. If you're receiving cash payments and not recording them daily, or if your crew receipts are getting lost in a shoebox, the most beautiful chart of accounts in the world won't save you. The system fails when you don't log transactions within 48 hours of the expense or sale. After that, you're working from memory and memory is unreliable. Also, this approach assumes you're doing job costing. If you're not tracking costs to individual jobs, most of these account subdivisions are noise. You'll end up with a P&L that tells you total revenue and total expenses but nothing about which jobs are profitable. In that case, a simpler chart of accounts with fewer subdivisions is actually better than a complex one you're not using correctly. Start simple, add accounts as you need them. Don't create twenty expense accounts on day one and hope you'll use them. You won't. If you need a downloadable template, most accounting software has built-in templates for landscaping. QuickBooks has one. Xero has one. They're decent starting points but they're generic. You should customize the revenue accounts to match your actual service lines and add or remove sub-accounts based on your equipment and supplier structure. A template without customization is just a list of hypothetical accounts that don't reflect your business.

The real test of whether your chart of accounts is working comes six months in, when you pull a report and can answer these questions without digging through attachments: which service line is most profitable, which job is dragging your margin down, and how much of your revenue is staying as gross profit after direct costs. If you can't answer all three quickly, your account structure needs adjustment, not your business strategy.