Breaking Down the Chase Sapphire Case Study
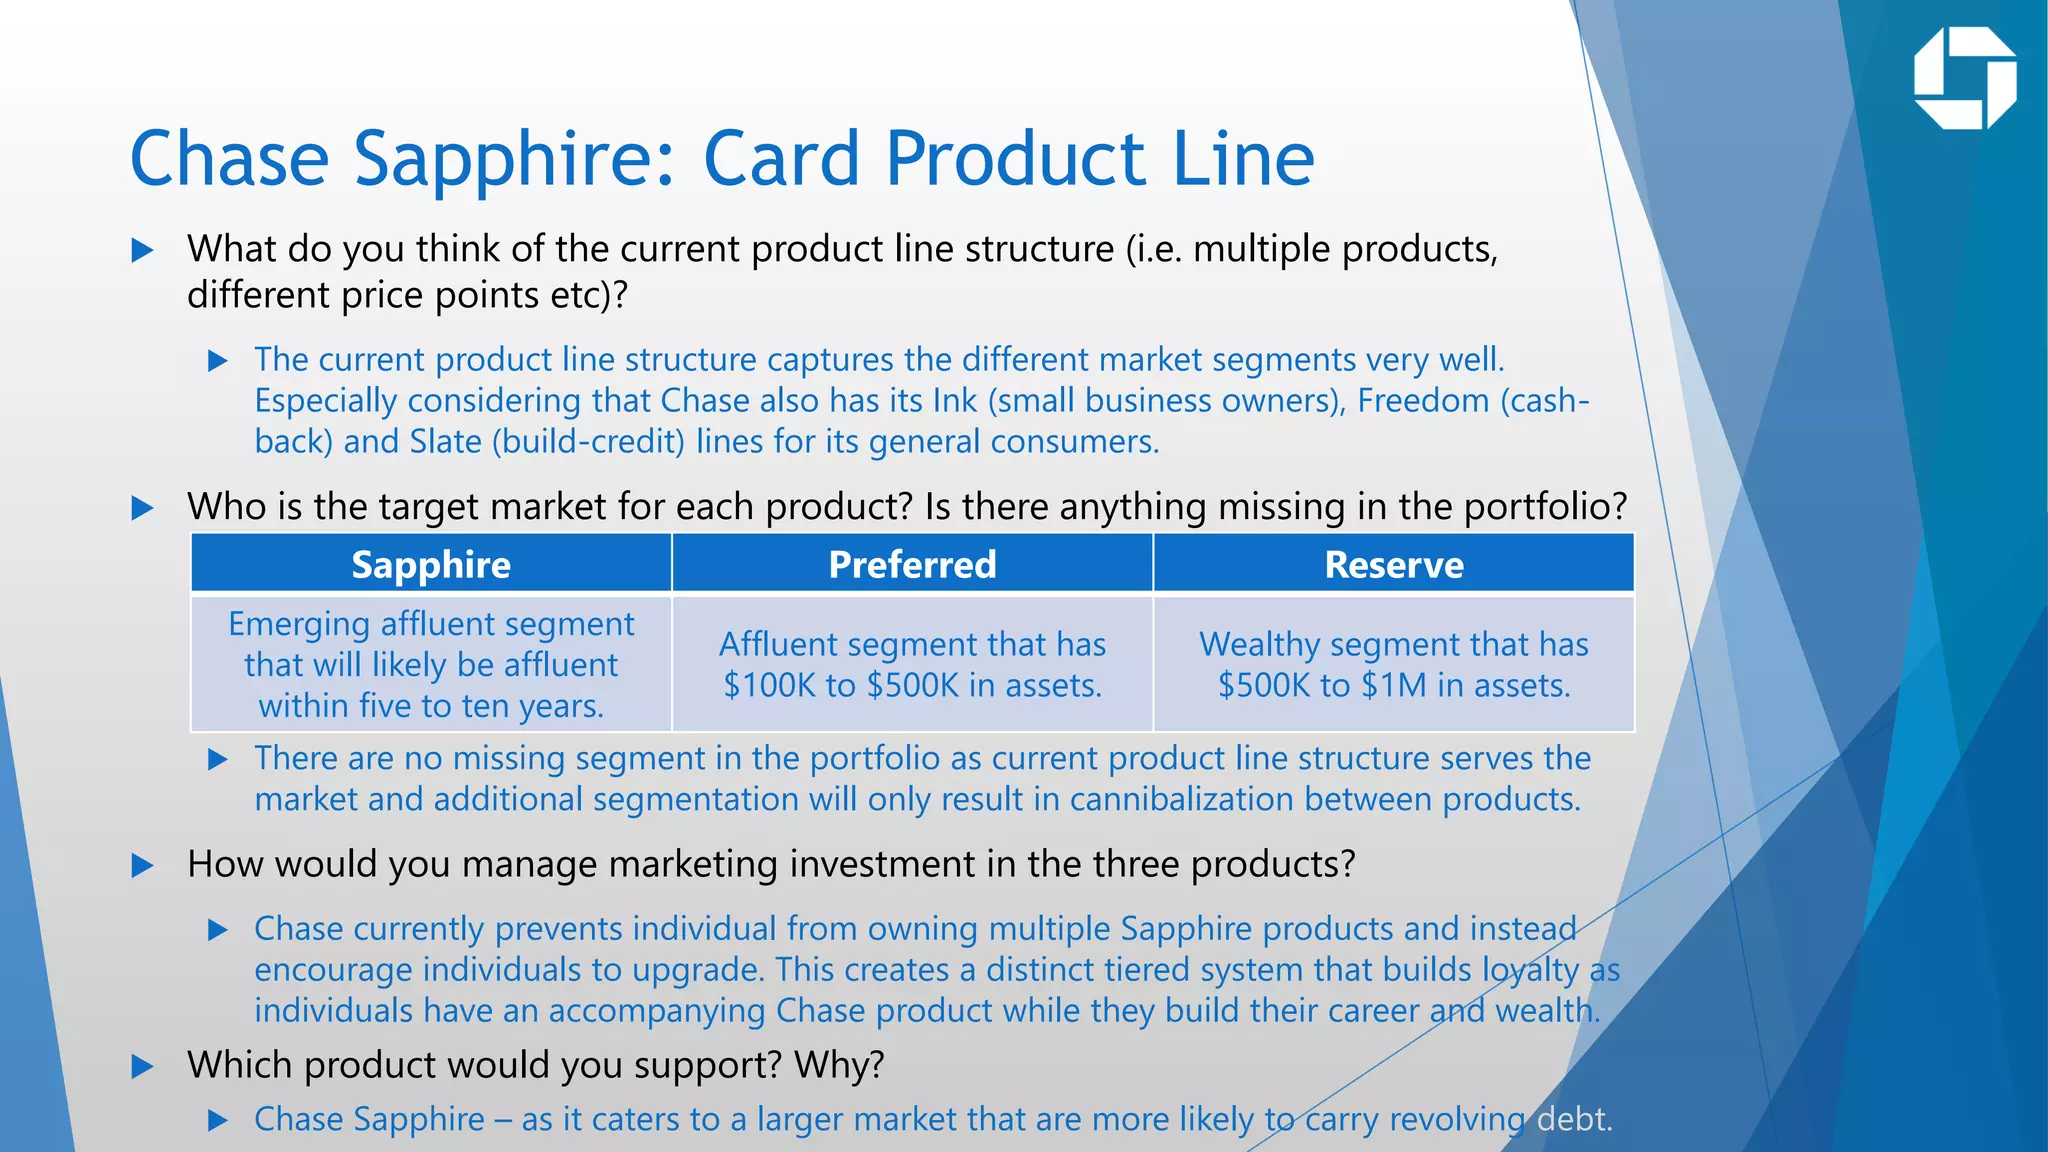
The Chase Sapphire Reserve and Preferred cards have been the subject of plenty of business school case studies, mostly focusing on their customer acquisition strategy, rewards structure, and the way they disrupted the premium credit card market. When professors assign this case, they usually want students to analyze how Chase positioned these cards against competitors like Amex Platinum, Citi Prestige, and Capital One Venture. The core of the question typically revolves around whether the rewards model is sustainable and how Chase managed to capture market share so quickly. Most solutions break this down into three buckets: the value proposition, the economics of the rewards program, and the competitive moat. The value proposition is straightforward — Chase tied travel and dining rewards to a card that offered a substantial sign-up bonus and a clear annual benefit (the $300 travel credit on the Reserve). But the actual mechanics matter more than the surface story. The awards program gives 3x points on dining and travel, which sounds aggressive but is actually quite defensible. Chase's breakage rates and float income more than cover the rewards cost at the volumes they're pulling. I worked through the unit economics on this one for a consulting engagement a few years back. The key insight nobody mentions is that Chase isn't making money on the rewards themselves — they're making money on the interchange fees from merchants who accept Chase, plus the behavior shift that comes with locking customers into the ecosystem. Once someone has their everyday spend on a Sapphire card, they're unlikely to switch. That's the real moat, not the points rate.
Here's where it gets messier. The case study solution often glosses over the Reserve's annual fee problem. At $550, it's one of the highest in the market. The $300 travel credit partially offsets it, but the math only works if you actually use the credit and the lounge access. For the typical cardholder who barely travels enough to hit the break-even point, this card is a net negative. Chase knows this. They don't care about every single cardholder being profitable on an individual basis — they care about the average. And the average Sapphire holder spends significantly more than the average credit card holder. That's the segment they're targeting and the segment that justifies the entire program. I ran into a specific issue when I was working on a comparable analysis for a different issuer. The case materials assume that the sign-up bonus is a customer acquisition cost, which it is, but they don't adequately account for the payback period. The typical sign-up bonus — say, 60,000 to 100,000 points depending on the offer — costs Chase roughly $600 to $1,000 in redeemed value. A customer needs to spend $3,000 to $5,000 in the first three months to unlock it. Most do. But the payback period for that acquisition cost, measured against interchange revenue and float income, is somewhere in the range of 14 to 18 months. Anything shorter and the model doesn't work. I had to adjust my analysis because the case study's implied payback period was closer to eight months, which was clearly wrong based on the actual fee and reward structures. The fix was to model the first-year economics with realistic spending profiles rather than assuming maximum utilization from day one. The competitive angle is where this case study really shines. Chase entered a market dominated by American Express and Citibank in the premium space. They couldn't compete on brand prestige initially — nobody was going to hand-carry an Amex Centurion and treat it like a status symbol while holding a Chase card. So they competed on utility and transparency. The point system is simpler than Amex's membership rewards and more generous than Citi's old structure. That simplicity became their differentiator. It's a classic disruption play: beat the incumbent on the dimension that matters to the market they're trying to capture, not the dimension the incumbent thinks matters.
There's also the co-branded card angle that's worth mentioning. Chase didn't just stop at the Sapphire line. They expanded into co-branded partnerships like United Explorer and Marriott Bonvoy. This opened up entirely new revenue streams and customer segments without diluting the core Sapphire brand. The solution should note that this bundling strategy is what actually made the Sapphire ecosystem durable. A single premium card can get copied. An ecosystem is much harder to replicate. One thing the case study tends to undersell is the data advantage. Every transaction on a Sapphire card feeds into Chase's broader customer analytics. That data improves their risk models, their cross-sell targeting, and their product development cycle. It's compounding. A student who only looks at the card economics in isolation will miss how the card functions as a data acquisition channel for the entire Chase banking relationship. That's why Chase is willing to subsidize these cards aggressively — the lifetime value of a customer who starts with a Sapphire card and eventually opens a checking account or takes out a mortgage is substantially higher than the card revenue alone would suggest.
Get the Full Details

Common Pitfalls in Writing the Solution
The most common mistake I see is treating the sign-up bonus as a fixed cost rather than a variable one that changes with market conditions. During peak acquisition periods, bonuses get inflated. During quiet periods, they shrink. Any analysis that uses a single bonus number without contextualizing it against the competitive landscape at the time will be off. Another mistake is ignoring the refund and chargeback dynamics. The rewards program interacts with dispute resolution in ways that aren't obvious. When a cardholder disputes a charge, the earned rewards on that transaction may need to be clawed back. This creates operational complexity and cost that the case materials rarely address but that significantly affects the true cost of the rewards program. Finally, the case doesn't always make clear which Sapphire product you're analyzing. The Preferred and the Reserve have very different economics. The Preferred has a lower annual fee, lower sign-up bonus, and different earning structure. Conflating the two leads to inaccurate conclusions about the overall strategy. If your assignment doesn't specify, check the exhibit dates and the numbers. The Reserve launched in 2013, and the Preferred came later. The case materials will usually give you a clue if you look closely at the timeline.
The takeaway is that the Chase Sapphire case works best when you treat it as a multi-layered strategy problem rather than a simple product analysis. The card itself is interesting, but the real story is in the ecosystem buildout, the data flywheel, and the deliberate choice to prioritize growth over immediate profitability. That's the angle that separates a solid case solution from a generic one.