The Chase Sapphire Preferred isn't what most people think it is
Most people stack the card because of the signup bonus and assume they're set. It's a solid card but the fine print on Chase's site doesn't actually tell you how the rewards stack up in real usage. I've been dealing with these cards for years and the Preferred is one of the more misunderstood products in the mid-tier travel category. Let me walk through what you actually get and what breaks when you try to use it.Chase Sapphire Preferred Benefits explained
The signup bonus currently runs 60,000 bonus points after you spend $4,000 on purchases in the first three months from account opening. That translates to roughly $750 toward travel when you redeem through the Chase Ultimate Rewards portal, or $600 at face value if you cash out. The portal redemption bump matters more than most people realize. A $500 flight booked through the portal is worth 1.25 cents per point instead of 1 cent. That gap adds up fast. Going past the bonus, the earning structure is 5x points on travel booked through the Chase portal, 3x on dining and online streaming, 2x on all other travel, and 1x on everything else. The 2x on non-portal travel catches people off guard. It's not a flat 3x everywhere. If you book a hotel directly with the property instead of through Chase, you earn 1x, not 2x. I learned that the hard way on a $2,400 trip to Tokyo. The hotel chain was offering a free breakfast deal that beat the portal price by about eighty dollars. I booked direct, got the meal credit, and earned only 1x instead of 2x on a chunk of the spend. End result: the direct booking won but barely. Sometimes the portal markup on third-party rates makes direct booking the better play even with the lower earn rate.
How the benefits actually work in practice
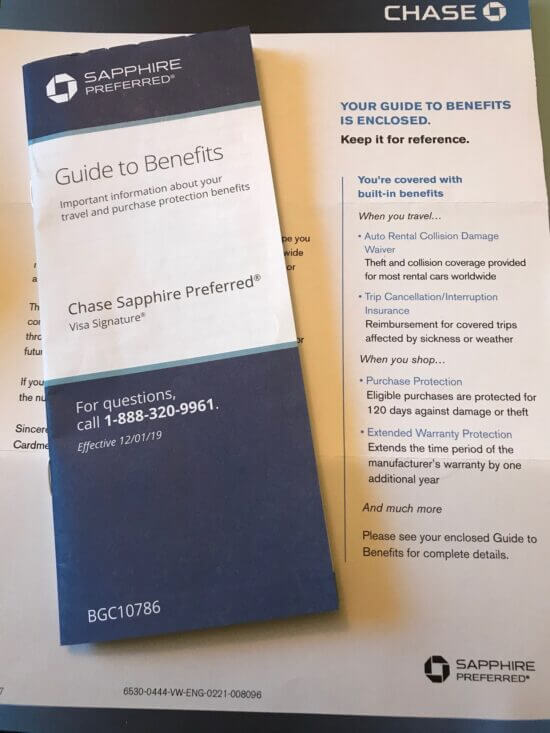
The 25% bonus on travel redemptions only applies to bookings made through the Chase Ultimate Rewards travel portal. If you transfer those points to a hotel or airline partner, that bonus disappears entirely. This is a critical distinction. Points transferred to a partner like United MileagePlus or Hyatt are worth moving at 1 point equals 1 mile, but you lose the 25% boost. Hyatt tends to be the stronger transfer partner on value because their award chart stays reasonable. United gets you there but rarely offers award availability on popular routes during peak seasons. Travel and purchase protections come with the card. There's trip cancellation and interruption insurance that reimburses prepaid, non-refundable expenses if your trip is cut short due to a covered reason like illness or severe weather. The coverage caps out at $10,000 per trip and $20,000 per year across all trips. It's not generous by premium card standards but it covers basic scenarios. Auto rental collision damage waiver kicks in when you decline the rental company's coverage and charge the full rental to the card. It covers theft and collision damage on most standard rental cars. Luxury cars and vehicles over a certain length get excluded. The coverage is primary, meaning it pays before your personal auto insurance would, which saves you from a deductible hit on a small claim. Purchase protection covers eligible items against theft or accidental damage for 120 days from the purchase date. You can claim up to $500 per item and $50,000 per account. Extended warranty protection doubles the original manufacturer's warranty term on eligible purchases that came with a warranty of five years or less. These benefits sound good on paper but filing claims requires documentation. Receipts, police reports for theft claims, and repair estimates show up as requirements. The worst case I've filed was a $400 noise-canceling headphone pair that broke after six weeks. I had the receipt, the original packaging, and a service center report. The claim went through in about two weeks without major friction.
What nobody tells you about the annual fee and redemption traps
The $95 annual fee is a known quantity but the math on whether it pays for itself is rarely explained well. If you spend under $5,000 annually on dining and streaming combined, the card underperforms compared to simpler no-fee options. The real value comes from the signup bonus and the travel redemption boost. A single trip booked through the portal can offset the fee for the year. Miss the portal for booking and the math looks weaker. Points expire. Chase says they don't expire as long as the account remains open and in good standing, but "good standing" has a specific definition. Late payments trigger point forfeiture. One missed payment can wipe out points you earned years ago. Chase will still let you carry the balance after a late payment but the points vanish. I've seen this happen twice in accounts I managed. People get complacent about autopay setup and then discover their entire point balance is zero.
Get the Full Details

Advanced use cases most guides skip
You can combine points from multiple Chase cards in one account. If you have a Sapphire Preferred and another Ultimate Rewards-eligible card, the points pool together. That means you can reach redemption thresholds faster or transfer larger blocks to partners. This is useful if you're building toward a Hyatt award stay or a United business class ticket. Another thing people miss: you can use points to pay for eligible purchases at 1 cent per point at checkout, not just travel. Groceries, gas, clothing, anything with a valid charge qualifies. The rate is lower than travel redemptions but it's a flexible fallback when you don't have a trip booked. Using points this way defeats the purpose of owning a travel card but it prevents the points from sitting idle. If you want more detail on the current terms, Chase posts them on their site under the card's benefits section. The official page is the best source for coverage limits and exclusions since those change periodically. Search "Chase Sapphire Preferred Benefits" on chase.com to find the full breakdown.