Setting Up a Finance Journal Notebook That Actually Works
The Cheap Finance Journal Notebook is basically a simple spreadsheet or document where you record every financial transaction — income, expenses, transfers, everything — with enough detail that you can actually make sense of it months later. Most people overcomplicate it. The entire thing can be built in about twenty minutes using Google Sheets or Excel, and it'll serve you just fine for personal budgeting or tracking business cash flow on a tight budget. I've built probably a dozen of these over the years for different clients and personal use. The core structure is always the same columns: Date, Category, Description, Inflow, Outflow, and Balance. You put the date first because everything else hangs off it. Category is where most beginners mess up — they make it too granular. Don't create separate categories for "coffee" and "groceries." Merge them under "Food" unless you're doing detailed expense analysis, which you probably aren't if you're using a cheap notebook instead of dedicated accounting software. Here's the column setup I actually use. Date as a proper date field so you can filter and sort later. Category pulled from a dropdown list to avoid typos stacking up. Description for whatever note you need, like "rent" or "client payment - Project Alpha." Inflow and Outflow stay as separate columns rather than combining them into a single net column. This makes reconciliation significantly easier when you're cross-checking against bank statements. Balance is a running total formula — =PreviousBalance+Inflow-Outflow — so you can see your position at any point without recalculating.
One specific problem I ran into that nobody warns you about: when you're carrying this notebook forward month to month, the formulas break if someone inserts or deletes rows in the middle of a block. I spent about three hours one evening fixing a corrupted balance column on a client's setup because they had added notes between transaction rows. The workaround was switching from a simple running formula to a SUM function that references the original range, =SUM($E$2:E15) for the balance in row 15, so inserting a row anywhere above doesn't shift the calculation window. It sounds minor but it saves you from losing your entire history.
Common Pitfalls and What Actually Matters
The biggest mistake I see people make is setting up an elaborate categorization system on day one and abandoning it within two weeks. A finance journal only works if the friction to enter a transaction is low. Five seconds per entry is the target. Anything more and you'll stop doing it. I've watched people build beautiful multi-sheet trackers with pie charts and conditional formatting and then go three weeks without a single entry because updating the tracker felt like homework. Another counter-intuitive thing: your notebook should have an opening balance row that pre-populates your starting position. Don't start from zero and try to work backwards. If you begin with $2,341 in your checking account, enter that as row one with a category called "Opening Balance" and an inflow of $2,341. Everything after that flows from there. Without this anchor, your balance column will drift from reality and you won't know where it went wrong until you've been logging for months. There's a limitation worth being honest about. This system falls apart fast once you're managing more than two or three accounts, dealing with recurring subscriptions across multiple platforms, or reconciling credit card charges against bank deposits. At that scale, the manual entry model becomes a part-time job. I've had clients who outgrew this within four months and moved to something like Simplifi or Mint, or if they're tracking business finances, Wave Accounting, which handles multi-account reconciliation automatically. A notebook isn't wrong — it's just bounded by the number of transactions you can realistically log by hand every day.
Get the Full Details
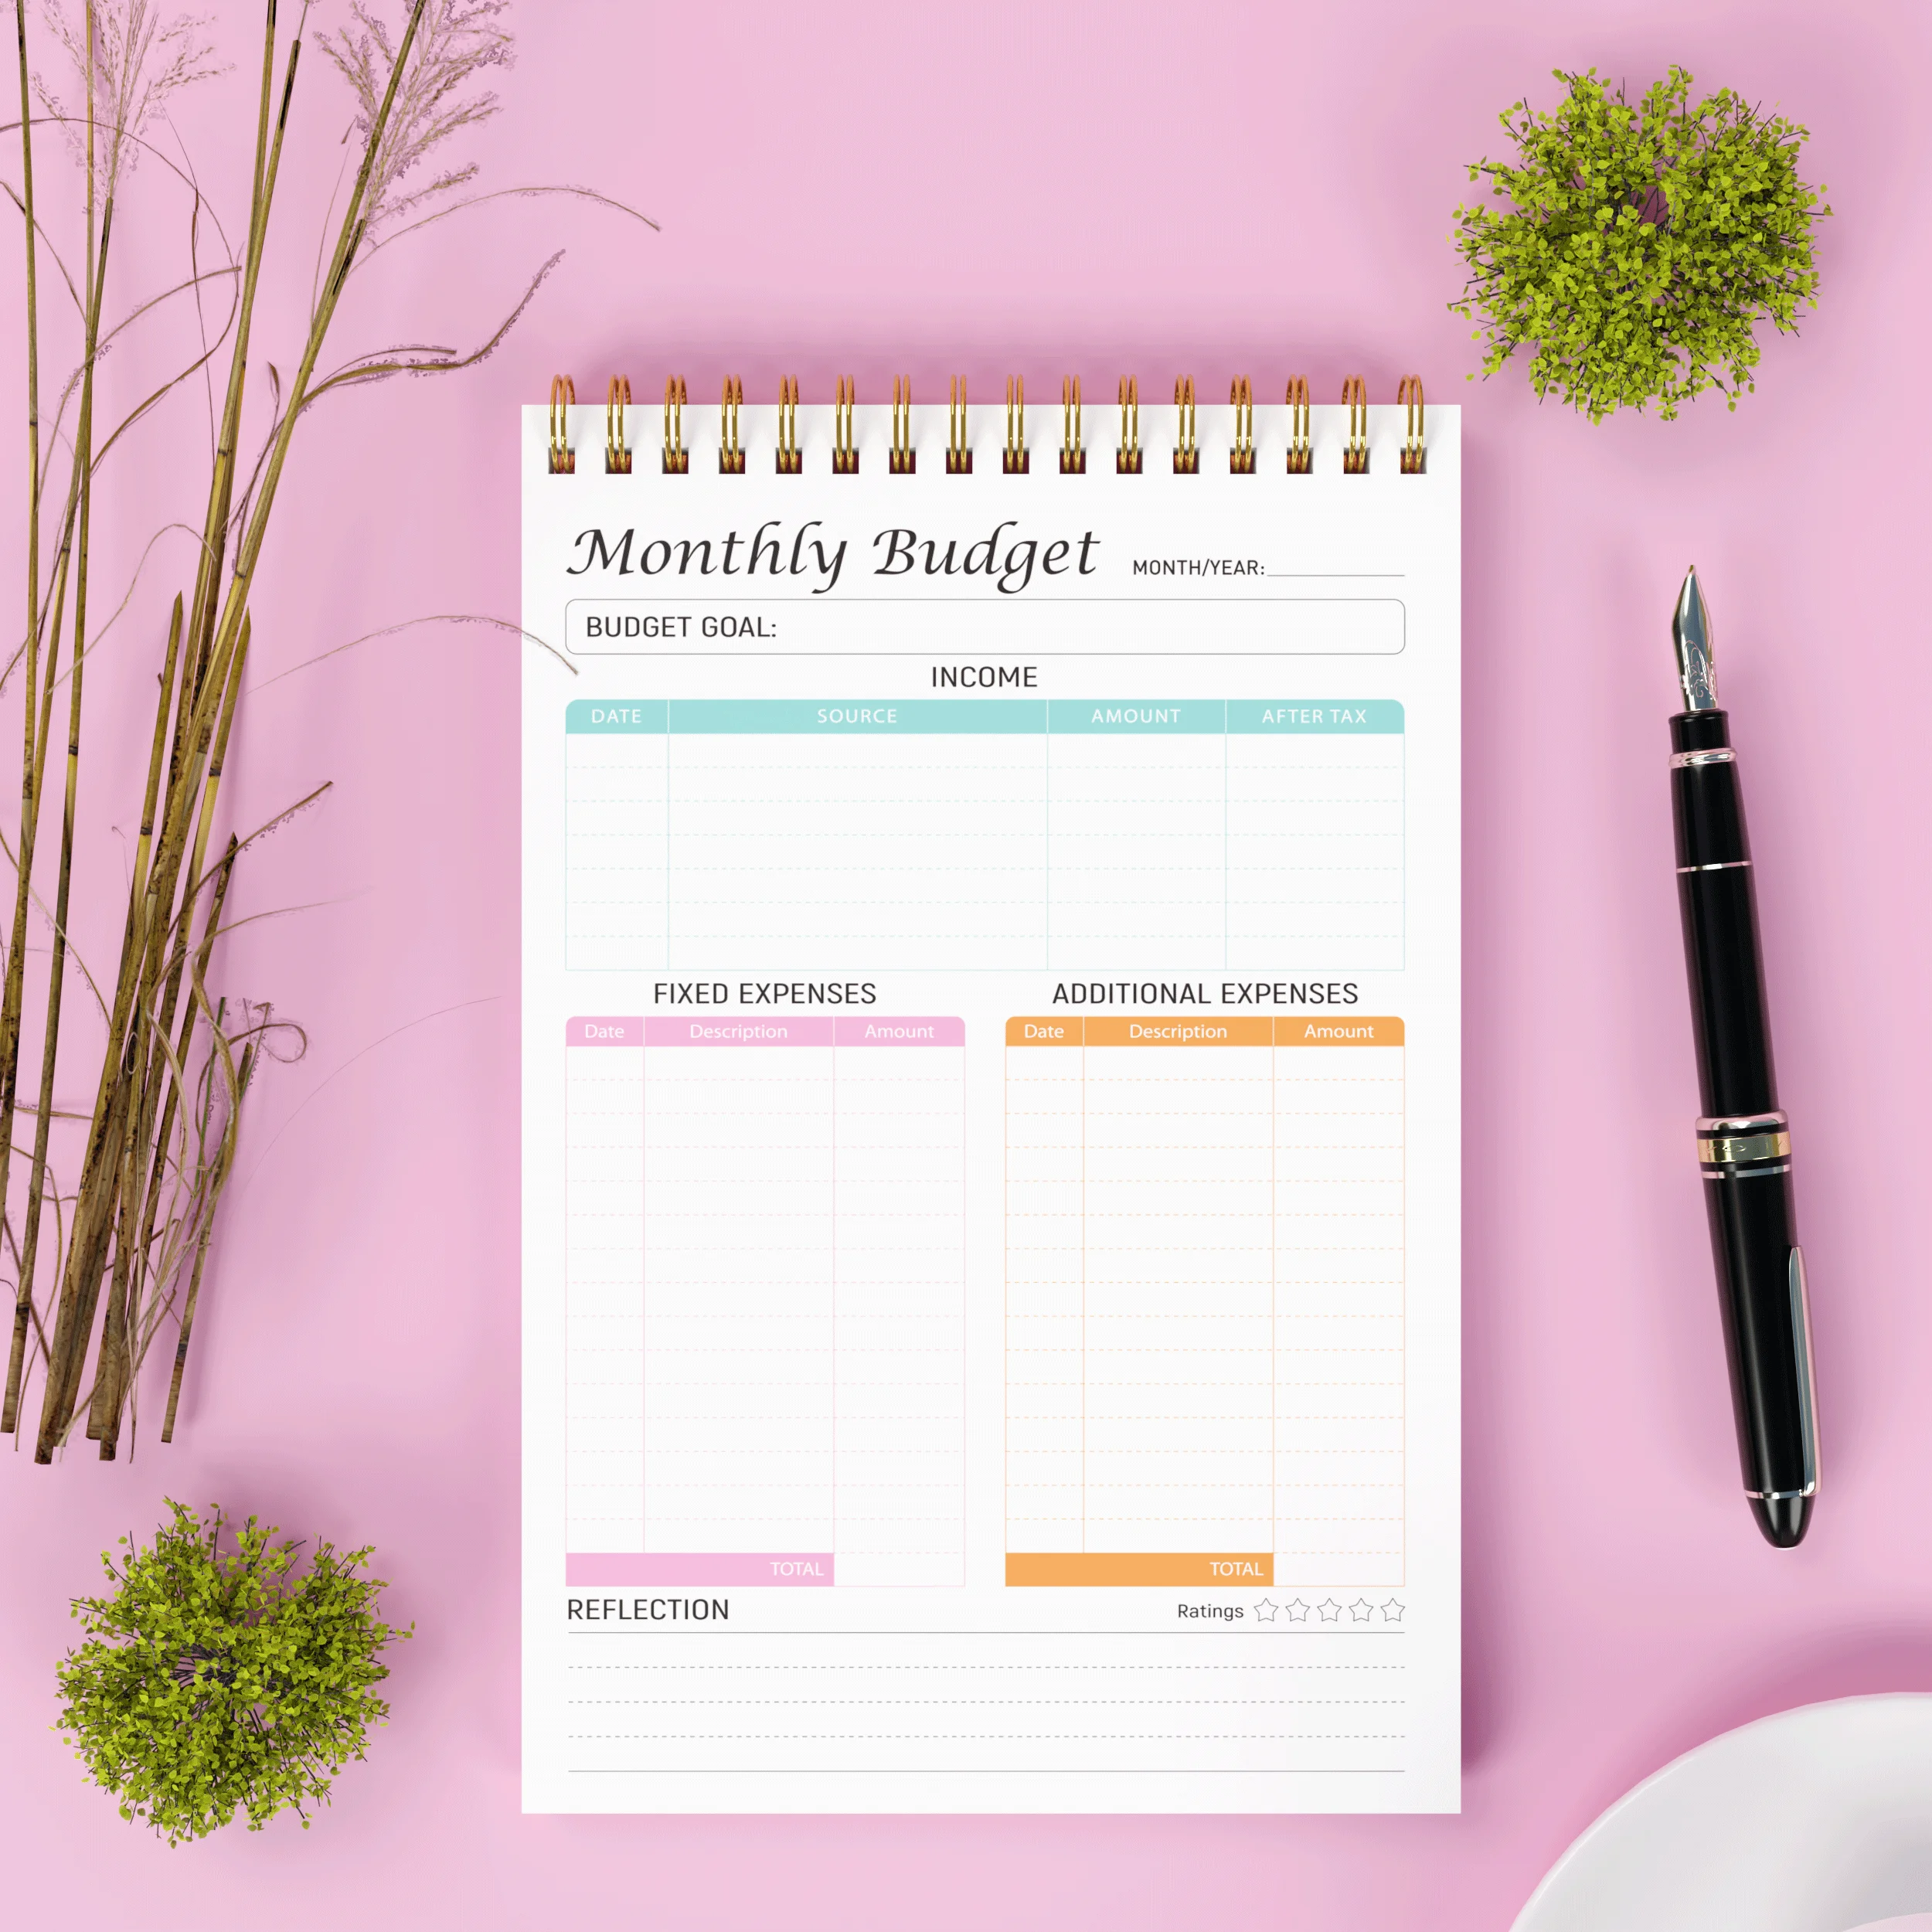
If you're a freelancer with irregular income and one or two bank accounts, this notebook model will serve you well for a year or more. If you have a salaried job with direct deposit and automatic bill payments, you might not need it at all — the bank statements alone probably tell you everything you need to know. Know your situation before you spend time building something that doesn't match your actual workflow.
Where to Get Started
There isn't a single canonical download link for a Cheap Finance Journal Notebook since it's a generic concept, not a specific product. The quickest path is to copy this structure directly: Date | Category | Description | Inflow | Outflow | Balance. Paste it into a new Google Sheet, format the first row as headers, add data validation to the Category column with your standard list, and drop in the balance formula in the first data row then drag it down. Total time: fifteen minutes. You can also find pre-built templates on Google Sheets template gallery by searching "personal finance tracker" or "cash flow spreadsheet" — they'll have extra features you may not need, but the core is the same. Keep it simple. Enter transactions daily or at least every few days. Reconcile once a month against your actual bank statement. If the numbers don't match, trace back from the most recent entry upward. That's it. Nothing fancy required.