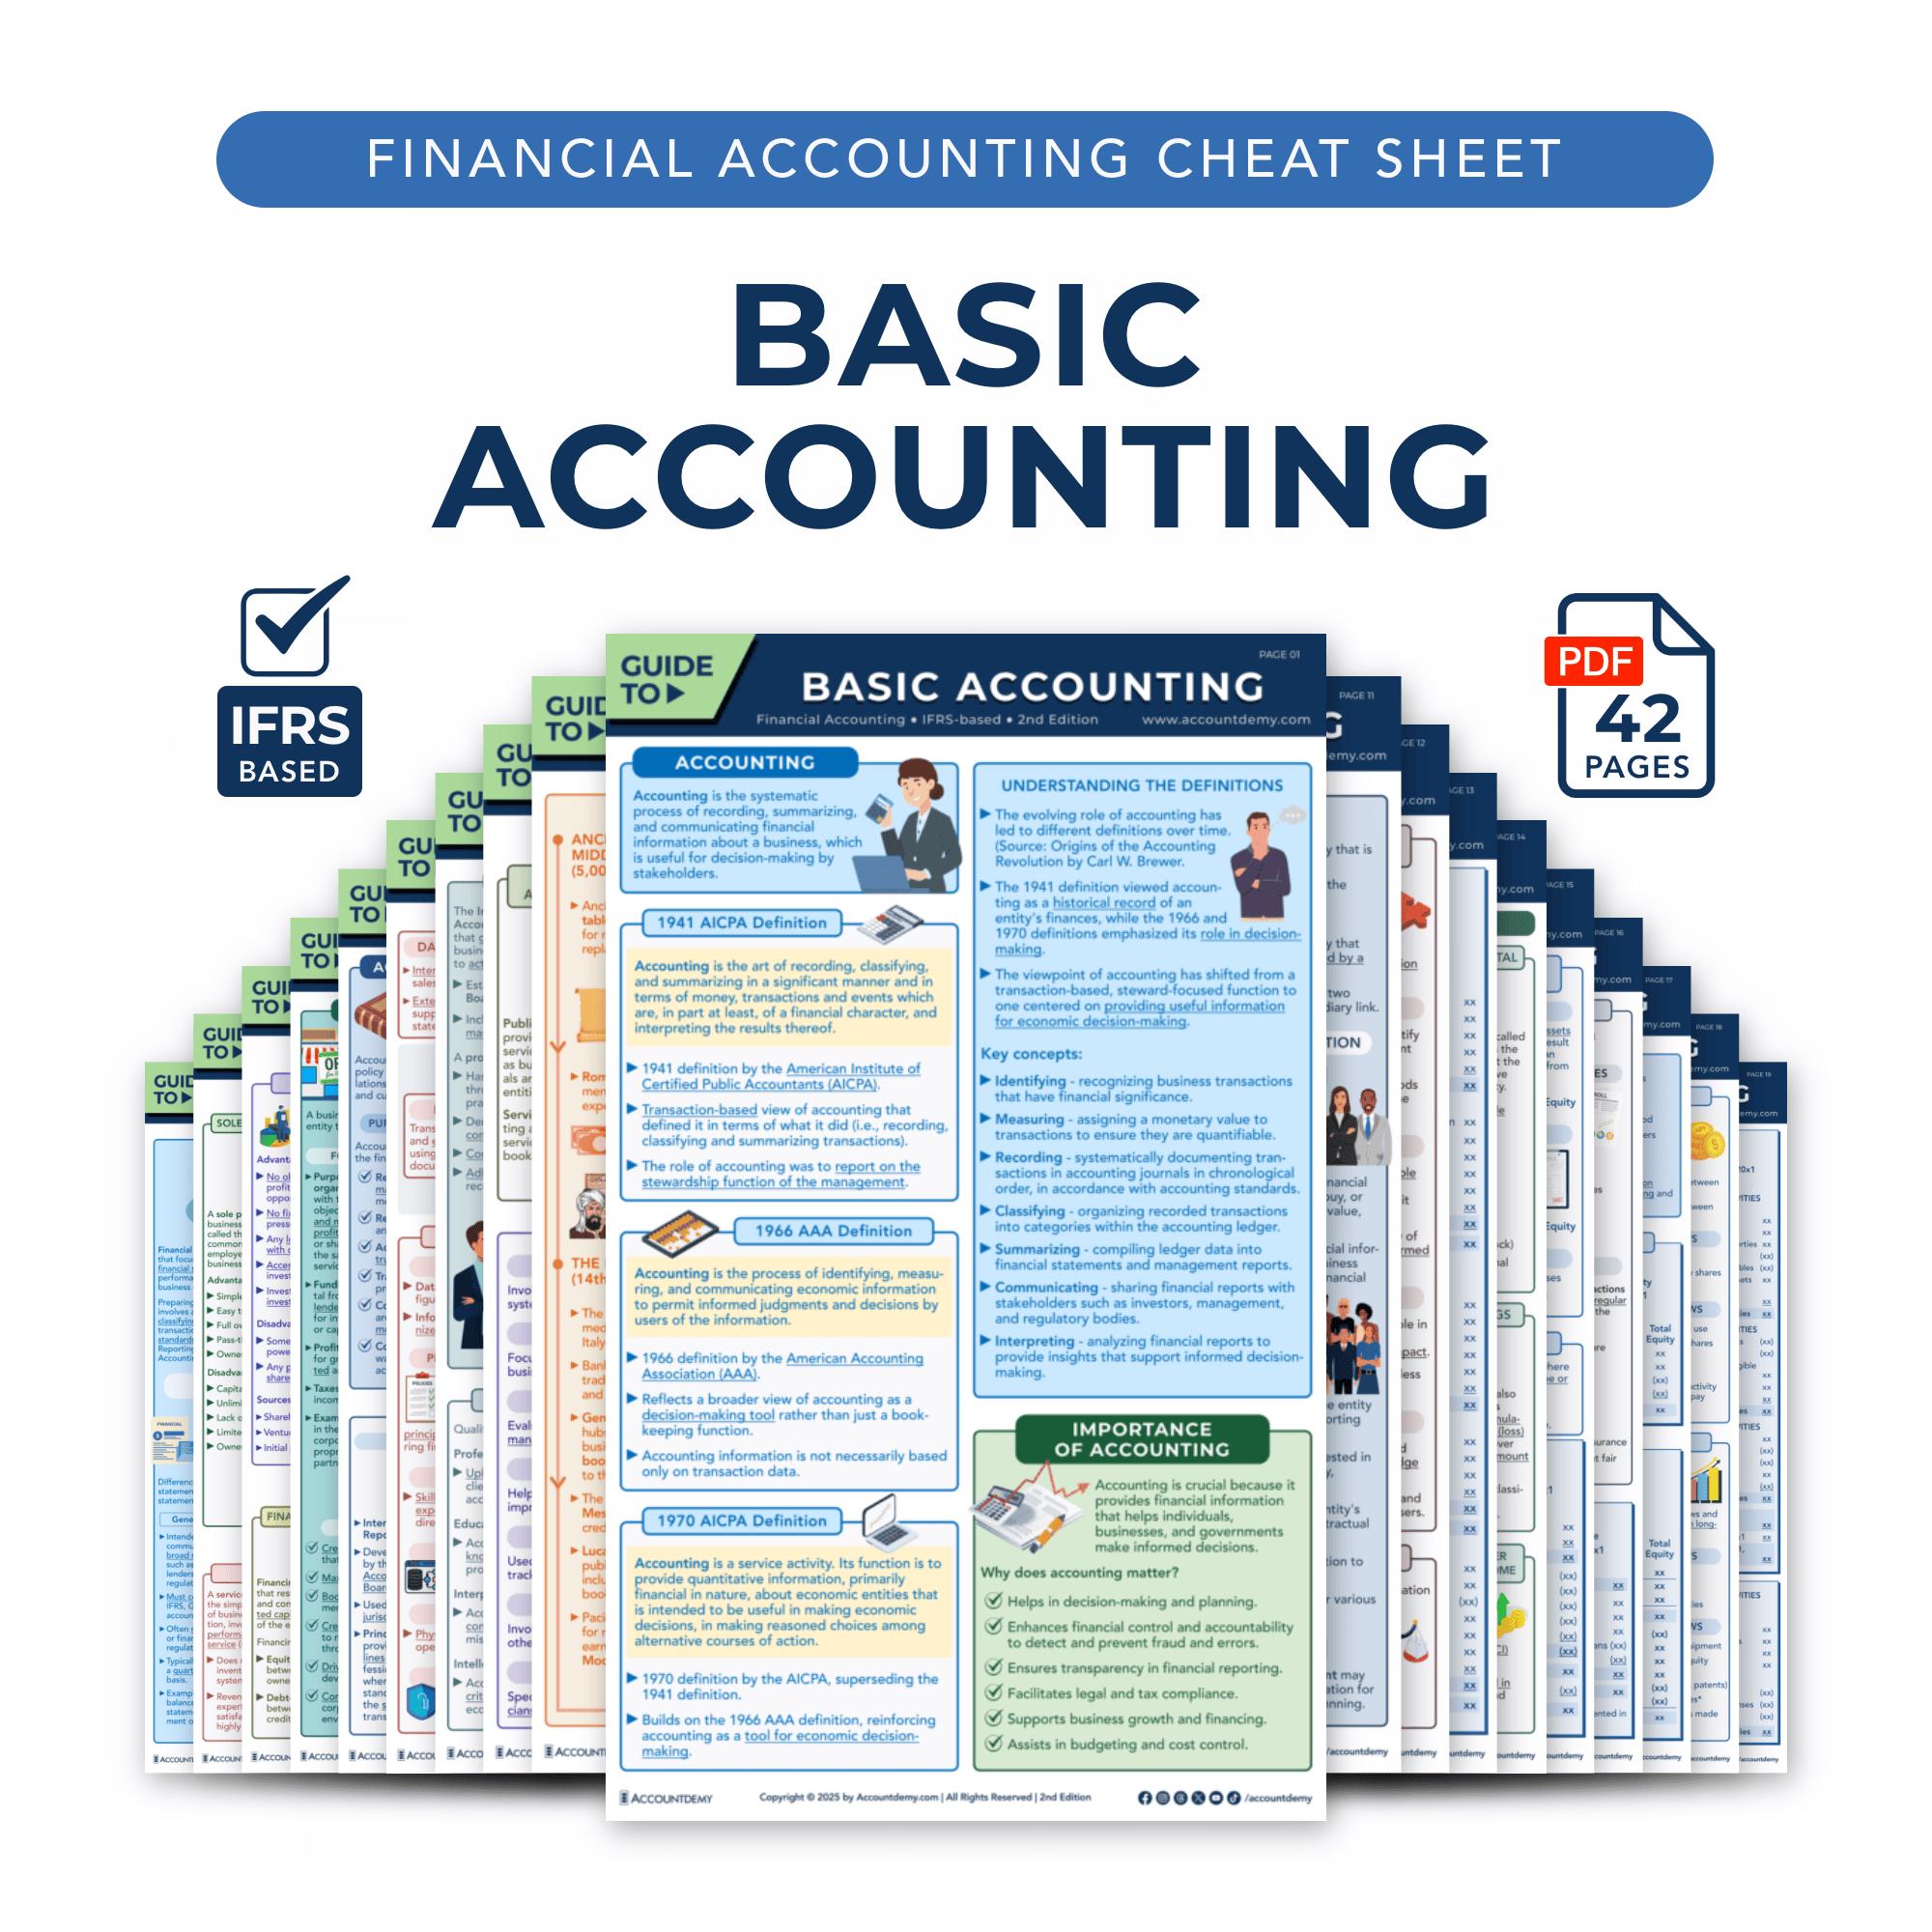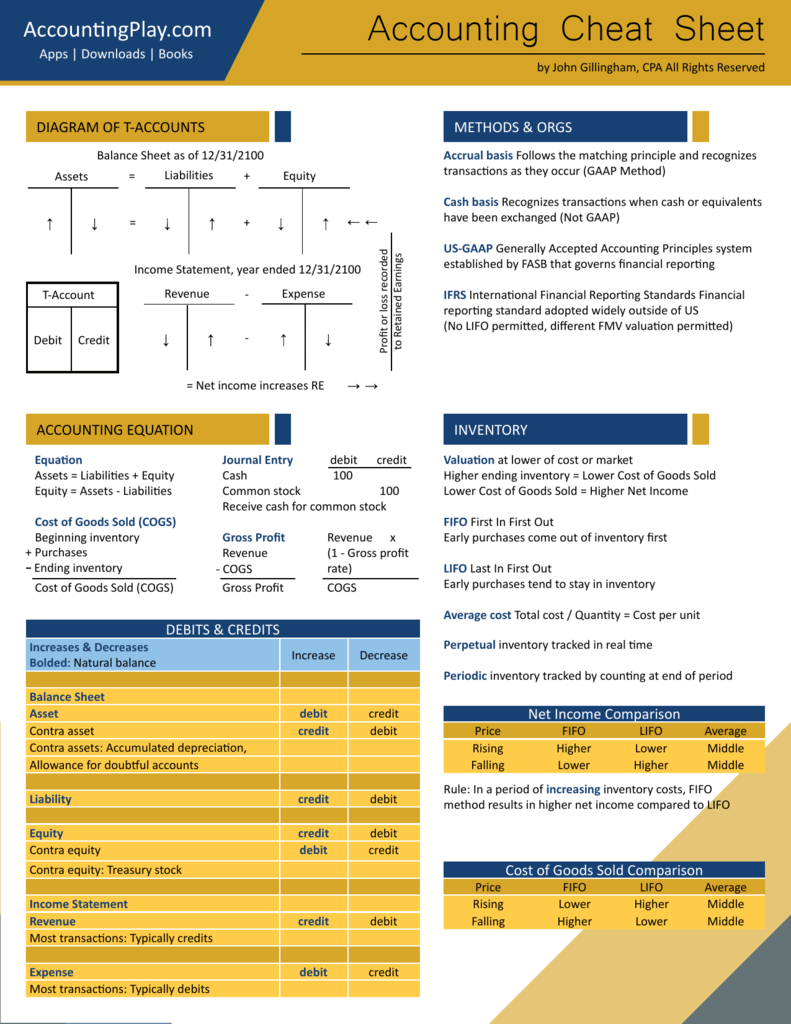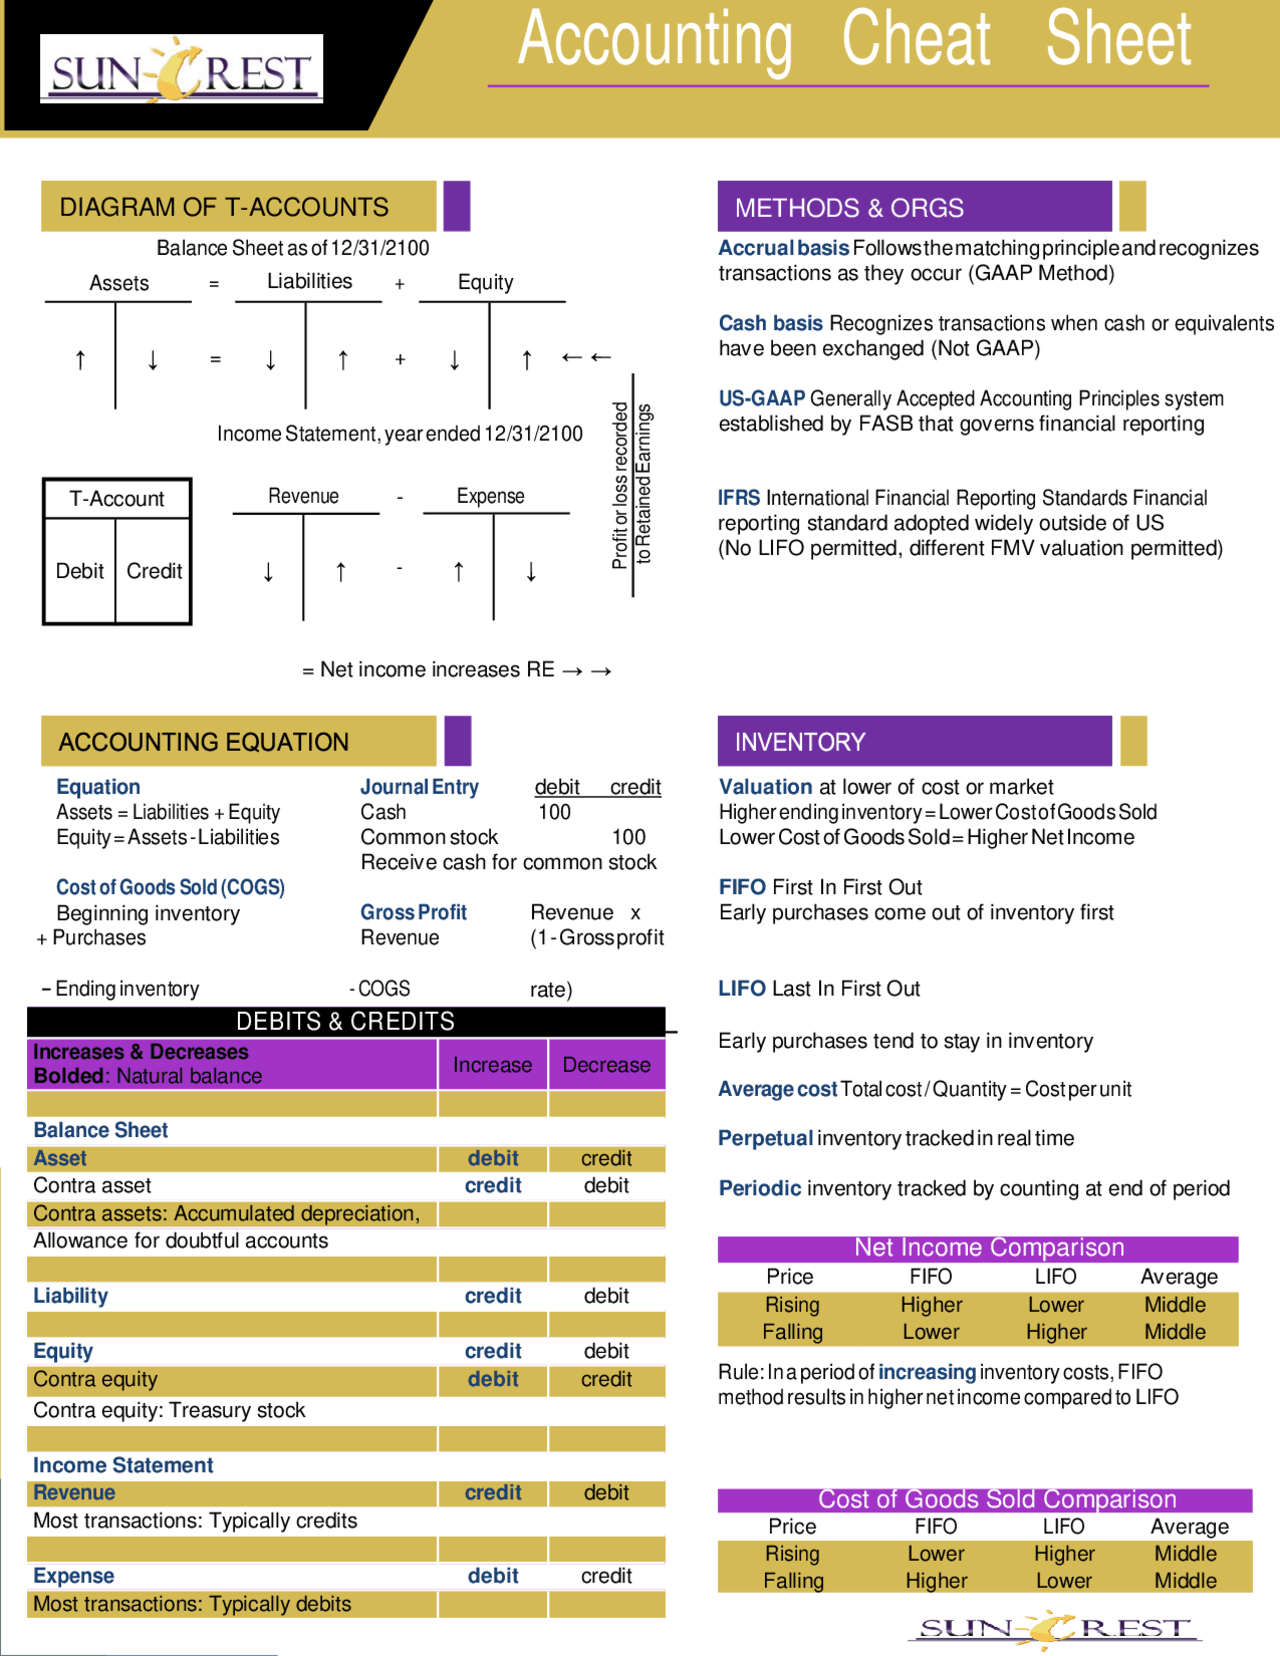
What People Actually Need From an Accounting Cheat Sheet
Most cheat sheets online are garbage. I've seen dozens. They're either too generic to be useful or they cut corners on the math that actually matters. A good one sits somewhere between a quick reference and a reality check. It should tell you the right formula, remind you when not to use it, and warn you about the edge cases that screw people up during real closing. The phrase "Cheat Sheet For Accounting Best" keeps coming up in forums because people are frustrated. They want something fast but accurate, something they can actually print and pin above their desk. What follows is what I use. It's not exhaustive. Nothing that short can be.
Core Cheat Sheet For Accounting Best Entries
Depreciation Methods You'll Actually Encounter
Straight-line is the default for a reason. It's simple, predictable, and auditors don't ask questions. The formula is straightforward: (cost minus salvage value) divided by useful life in years. That gives you the annual expense. Monthly, divide by twelve. Double-declining balance hits harder early on. You take the straight-line rate and double it, then apply it to the book value each year. It doesn't subtract salvage value upfront. That catches people out. You switch to straight-line partway through the asset's life when the DDB amount drops below what straight-line would give you. This is standard practice under GAAP for tax-advantaged depreciation on certain equipment. I once spent three hours debugging a depreciation schedule where someone had applied the salvage value at the beginning of a DDB calculation instead of at the end. The books didn't balance, and the variance was small enough to hide in rounding. Took me two weekends to trace. The workaround is simple: never let the book value drop below salvage. Write that rule on your sheet.
Revenue Recognition Rules That Bite You
ASC 606 changed how most companies book revenue, but the core idea is still five steps. Identify the contract. Identify the performance obligations. Determine the transaction price. Allocate that price to each obligation. Recognize revenue when or as the obligation is satisfied. The part people skip is step four. Allocating transaction price across multiple performance obligations. If you sell a software license with implementation services and support, you can't just dump all the revenue into one bucket. Each obligation needs its own standalone selling price. You estimate it if there's no market benchmark. This takes time and documentation. But skipping it is how you get restatements. I had a client who recognized 100 percent of a three-year subscription upfront because "the contract was signed." The auditors flagged it immediately. Correct treatment spreads revenue over the service period. The fix was to restate the prior year, which cost them more in audit fees than the wrong entry ever saved in cash flow planning.
Get the Full Details

Inventory Valuation Pitfalls
FIFO, LIFO, and weighted average each produce different COGS and ending inventory numbers. LIFO is still allowed under US GAAP but not IFRS. If you're working with international partners, that distinction matters. FIFO tends to show higher profit in inflationary periods because older, cheaper inventory flows through COGS first. LIFO does the opposite and reduces taxable income. The real issue is inventory layers. Under LIFO, you build up layers year over year. When sales dip, you can LIFO liquidate, pulling old cheap layers into COGS and artificially boosting gross margin. Auditors watch for this. If your COGS drops while your selling prices rise, you should explain why. The explanation is usually liquidation. I found a manufacturing company once that hadn't done a physical count in four years. Their perpetual system was off by about eleven percent. The variance showed up as shrinkage expense that ate into net income. The workaround they used was quarterly cycle counts on high-value SKUs and annual full counts. That got the variance down to under two percent within eighteen months.
Budgeting Shortcuts That Aren't
Zero-based budgeting sounds efficient until you need to justify every line item every year. It works for discretionary spend. It doesn't work well for payroll, rent, or debt service. Those are structural costs. You budget them based on headcount plans and lease terms, not annual justifications. The practical approach is hybrid. Zero-based for marketing, travel, and professional services. Incremental for everything else. I template it this way: fixed costs pulled from contracts, variable costs driven by headcount and revenue forecasts, and discretionary items scoped annually. The resulting budget is faster to build and easier to defend. One thing that helps: lock in your revenue assumptions before you build the cost side. I've seen budgets cascade upward because someone started with a target net income and worked backward. That inverts the logic and produces fantasy numbers. Revenue first, costs second, variance analysis third.
Journal Entry Conventions That Prevent Errors
Standardizing your JE templates saves more time than any automation tool. Date, reference number, account, debit, credit, description, preparer, approver, attachment index. Keep it consistent across departments. Every adjusting entry should have a clear reference to the source document. If it doesn't, flag it. The biggest waste I see is recurring entries without review. A monthly accrual that rolls forward unchanged for six months is a ticking variance. I set a rule: any recurring JE gets a brief note on whether the amount changed and why. Three words are enough. "Same as prior," "revised per new contract," "adjusted for headcount change." It takes ten seconds and it makes close a lot less painful.

When a Cheat Sheet Falls Short
Shortcuts don't replace judgment. A two-page reference can't handle multi-currency consolidation, lease modifications under ASC 842, or revenue arrangements with right-of-return clauses. These require reading the actual standard and understanding the specific facts of your situation. The cheat sheet covers the common cases. It won't save you from the unusual ones. For those, you go to the primary sources. FASB ASC for US GAAP, IFRS Foundation for international standards, and your jurisdiction's tax code for anything compliance-related. The cheat sheet is a starting point, not a substitute for looking at the full text when the situation diverges from the norm. If you need something you can actually use, the best approach is building your own. Take the formulas that matter to your daily work, add the exceptions you've learned the hard way, and update it every quarter. It'll be longer than you want it to be. It'll also be better than anything you download.