Accounting Cheat Sheets: What Actually Works
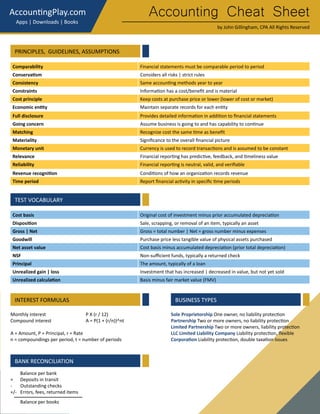
I've spent years dealing with clients who want everything condensed into something digestible. Accounting is one of those fields where people genuinely need reference material, but they usually make it harder than it needs to be. A cheat sheet for accounting should be functional, not decorative. The ones I see most often are just formatted spreadsheets with tiny fonts that look cute but are impossible to use under deadline pressure. The phrase itself comes from a trend I noticed around 2019 when Pinterest and Instagram accounts started posting color-coded accounting cheat sheets with pastel backgrounds and rounded corners. They went viral because they looked nice, not because they were accurate. I've seen people cite pastel-highlighted debt-to-equity formulas in client meetings. It's not pretty when the numbers don't match the source documentation. Here's how to actually build something useful.
Start with the core categories. Debits and credits come first because everything else branches from there. Revenue recognition, accruals, depreciation methods, amortization schedules, balance sheet classifications, cash flow statement formats, tax bracket basics, and audit trail requirements. That's the foundation. Everything beyond that depends on jurisdiction, industry, and company size. Don't clutter the sheet with edge cases you'll never encounter. I spent three weeks last year trying to figure out why a client's deferred tax asset calculations kept flagging in review. Their previous accountant had used straight-line depreciation for book purposes and MACRS for tax purposes, but hadn't documented the reversal schedule anywhere. The workaround was rebuilding the temporary difference matrix from scratch using their original basis and recovery periods. Took about six hours. If they had a proper depreciation comparison table on a reference sheet, it would have taken twenty minutes. This is exactly what good cheat sheet material looks like in practice.
Structuring Your Reference Material
Keep it to one page per major topic area. Two pages maximum if you're covering interrelated concepts like the three financial statements. The moment you go beyond that, nobody will use it. People reference cheat sheets under time pressure. They flip, they scan, they move on. Use a two-column format for journal entries. Left side lists the transaction type, right side shows the debit and credit split with account numbers. Add a third column for common pitfalls. For example, prepaid insurance is a current asset, not an expense, until the coverage period passes. Most junior staff mix this up on their first few months of work. The matching principle deserves its own section because it causes more misstatements than any other concept. Expenses belong in the period that generates the related revenue, not the period the bill arrives. Inventory costs match to sales. Service labor costs match to the service delivery period. These sound obvious until someone tries to expense a twelve-month service contract in month one because the invoice came early.
Get the Full Details
Common Formats and Their Failure Points
Pastel highlighter versions fail because they sacrifice readability for aesthetics. Color coding works when it serves a function, like marking year-end adjustments in yellow or accruals in orange. Random rainbow schemes add nothing. Single-page laminated cards work well for field work and audit prep. They fit in a binder next to your calculator and spreadsheet printouts. The downside is space constraints. You can't fit every exception on one card. Decide what stays and what moves to an appendix or separate reference document. Digital versions in spreadsheet or PDF format are the most practical long-term solution. I keep a master Google Sheet with tabs for each major accounting area. When standards change, which they do regularly, I update the source document rather than reprinting physical copies. The version control problem with digital sheets is real though. Make sure everyone on your team knows which file is current.
Another thing nobody warns you about: the relationship between the balance sheet and the cash flow statement trips up most people learning the material. Changes in working capital accounts flow directly into operating cash flow. Increase in accounts receivable means cash was collected but revenue was recognized earlier. Decrease means the opposite. Without this connection clearly mapped on your reference sheet, reconciling cash flow statements becomes guesswork.
When Your Cheat Sheet Falls Apart
Standardized templates don't handle intercompany transactions cleanly. I've worked with mid-market companies where parent and subsidiary charge management fees to each other, and the elimination entries create circular dependencies that basic cheat sheets don't address. In those cases, you need a dedicated consolidation worksheet that tracks intercompany balances separately from the standard chart of accounts. Multicurrency environments are another gap. Functional currency translation versus transaction currency translation follows different rules under ASC 830 and IAS 21, and most generic reference materials lump them together incorrectly. If your operation involves anything beyond a single currency, build a separate section covering remeasurement, translation adjustments, and gain loss recognition thresholds.

Where to Find or Build Yours
If you want something ready-made, the AICPA publishes reference guides that are more thorough than most DIY versions. State boards sometimes release exam prep sheets that double as practical references. CPA review courses like Becker and Wiley include condensed formula sheets that are accurate but optimized for testing, not daily work. Building your own takes about four hours if you work methodically. Pull your standard journal entry templates, extract the recurring patterns, strip out jurisdiction-specific notes you don't need, and format it for actual use. Test it on a live transaction before calling it finished. If you catch yourself second-guessing an entry while using the sheet, something's missing or wrong. The version I currently use runs about eighteen pages across four tabs: journal entries and adjustments, ratio calculations and thresholds, tax computation summaries, and reconciliation procedures. It lives in shared cloud storage with edit history enabled. Last year I reduced my monthly close review time from two days to roughly a day and a half after updating the depreciation and accrual sections based on real audit findings. That's the kind of return this material provides when it's actually useful rather than decorative.