Working With Financial Literacy Simulations: What You Need to Know
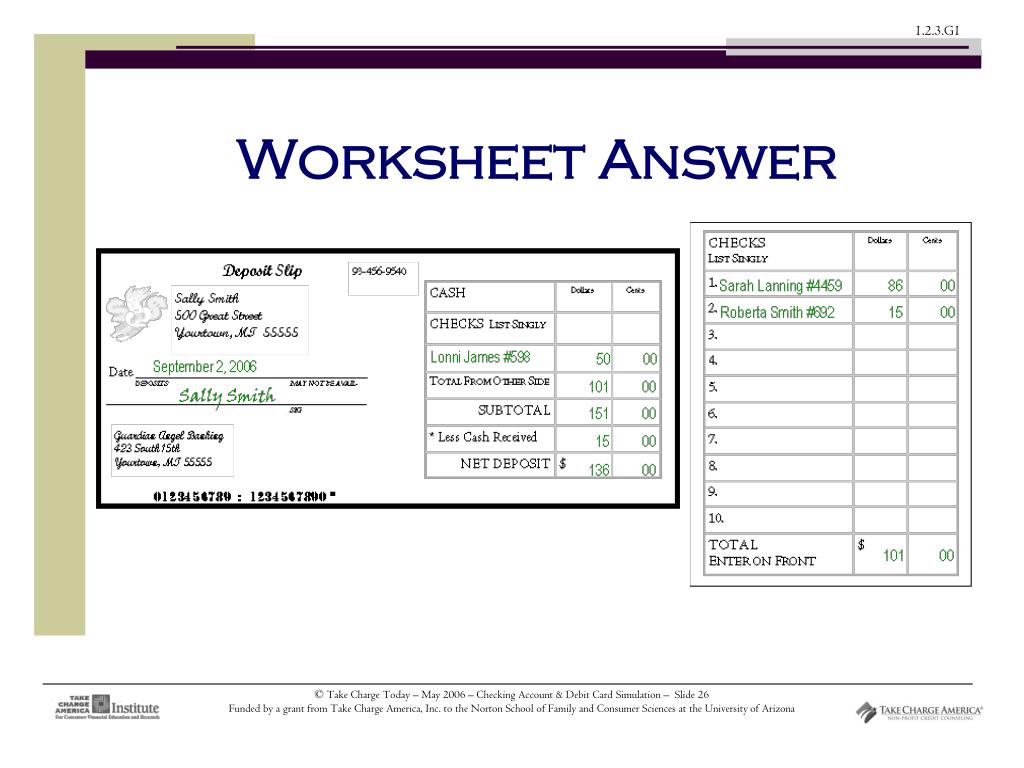
The checking account and debit card simulation answer key is essentially a reference document for an educational module where students manage virtual accounts, process transactions, and balance their books. These simulations are common in high school personal finance courses and some community college programs. The software typically presents a series of scenarios—writing checks, tracking ATM withdrawals, reconciling a register—and asks students to compute balances, identify errors, or determine available funds after a sequence of events. I ran into this repeatedly when helping students debug their work. The most frustrating part isn't the math itself. It's that the simulation often introduces transactions in a deliberately confusing order. A deposit posted on Thursday, a check written on Friday, but the problem lists them out of sequence or buries a recurring auto-pay charge between obvious line items. Students miss it. They calculate based on what they see rather than the chronological reality of the account.
Using the Checking Account And Debit Card Simulation Answer Key Effectively
The answer key serves two purposes. First, it lets you verify your final numbers quickly. Second, and more importantly, it reveals the transaction sequence the software expects. When your balance doesn't match the key, don't just copy the answer. Look at where your calculation diverged from the provided solution and trace back through the transaction list to find which item you processed incorrectly or overlooked entirely. Here is how I typically walk through a problematic set: Step one: Write out every transaction in the order it was given. Do not reorder them chronologically yet. Just transcribe exactly what the simulation shows.
Step two: Add a column for running balance. Start with the opening balance given in the problem and work down one line at a time. Show every plus and minus. This is where most mistakes surface—if you are doing mental math or skipping steps, the running balance column exposes it immediately. Step three: Cross-reference with the answer key. If your final balance is off by even one cent, go back to your running balance column and compare it line by line with what the key shows. The divergence point tells you exactly which transaction caused the error. One edge case that catches people consistently involves debit card purchases that post as pending versus posted. The simulation might show a $42.50 purchase at a gas station as pending, then later show the same transaction clearing for $42.50. If you count it once, your balance is wrong. If you count it twice, your balance is also wrong. The correct approach depends on what the question is asking—available balance at a point in time versus cleared balance. I learned this the hard way during a tutoring session when a student spent twenty minutes trying to reconcile a problem that hinged entirely on whether the pending transaction had actually posted. The simulation had not specified. We checked the help documentation and found the default rule for that particular software version: pending transactions do not affect available balance until they clear. She still had three other problems to finish that day.
Get the Full Details

Common Pitfalls and Why They Cost Points
The biggest issue I see students make is assuming the starting balance is always positive. Some simulation problems begin with an overdraft scenario—a negative opening balance representing a prior unrecorded charge. If you treat it as positive, every subsequent calculation is backwards. Look carefully for a dollar sign with a negative prefix or parentheses around the amount. That notation means negative in these systems. Another frequent error involves service fees. The simulation may include a monthly maintenance fee, an overdraft protection transfer fee, or an ATM surcharge from a non-network machine. These are often listed in a separate instructions panel rather than within the transaction timeline itself. Students skip over them because they are focused on the check-writing and deposit entries. A single missed $3.50 ATM fee can throw an entire reconciliation out of alignment. Check register formatting is another source of confusion. The simulation might present transactions as a list, but expect your answer in register format with date, description, debit, credit, and balance columns. The numbers are the same, but the presentation matters for partial credit. I have watched students get zero on a problem they calculated correctly because they returned a simple number instead of the formatted register the question required.
What the Answer Key Cannot Do for You
The answer key gives you final balances and sometimes intermediate steps, but it does not teach you the underlying logic. If your course uses a specific reconciliation method—bank reconciliation with outstanding checks and deposits in transit, for example—the answer key alone will not help you understand why certain items create timing differences. You need to know the difference between a check written but not yet cashed and a deposit made but not yet credited by the bank. These timing issues are the whole point of the exercise in many cases. There is also a limitation worth noting directly. Some simulation platforms generate randomized transaction values per student. The answer key you find online may not match your specific instance because your numbers were algorithmically generated. This is a real problem in courses using adaptive learning software. In those cases, the answer key is only useful as a format reference, not as a numerical check. You can verify your methodology against it, but you cannot trust the final figures. If you are working with randomized problems, the workaround is to create your own verification path. Set up a simple spreadsheet with the same transaction structure the simulation uses. Input your opening balance, add and subtract each transaction in order, and compare your spreadsheet output to what the simulation reports at each checkpoint. This takes about five extra minutes but eliminates the guesswork of whether you are following the right method or just arriving at a lucky number.
Practical Tips That Actually Move the Needle
Keep a dedicated scratch sheet for each problem. I know it seems obvious, but I have seen too many students erase and re-erase the same line five times, losing track of their work in the process. A clean sheet with one attempt per problem lets you compare your first try against the key without confusion about which version you are looking at. When the simulation asks for an available balance, check whether it wants the balance before or after a specific transaction. The wording matters. "What is your balance after the check clears?" versus "What is your balance before the check clears?" produce different answers even though the numbers involved are identical. Read the question once before you start calculating. It saves about two minutes per problem and prevents a category of errors that has no mathematical component whatsoever. For the transaction processing questions where you need to identify which check cleared and which did not, use the check number as your primary anchor. The amount alone is not reliable because multiple checks can share the same dollar value. Check numbers are sequential and unique within any given problem set. If two checks for $75 appear and only one cleared, the check number tells you which one. This is the kind of detail that separates students who finish early from those who stay stuck on reconciliation problems for the last ten minutes of the quiz.