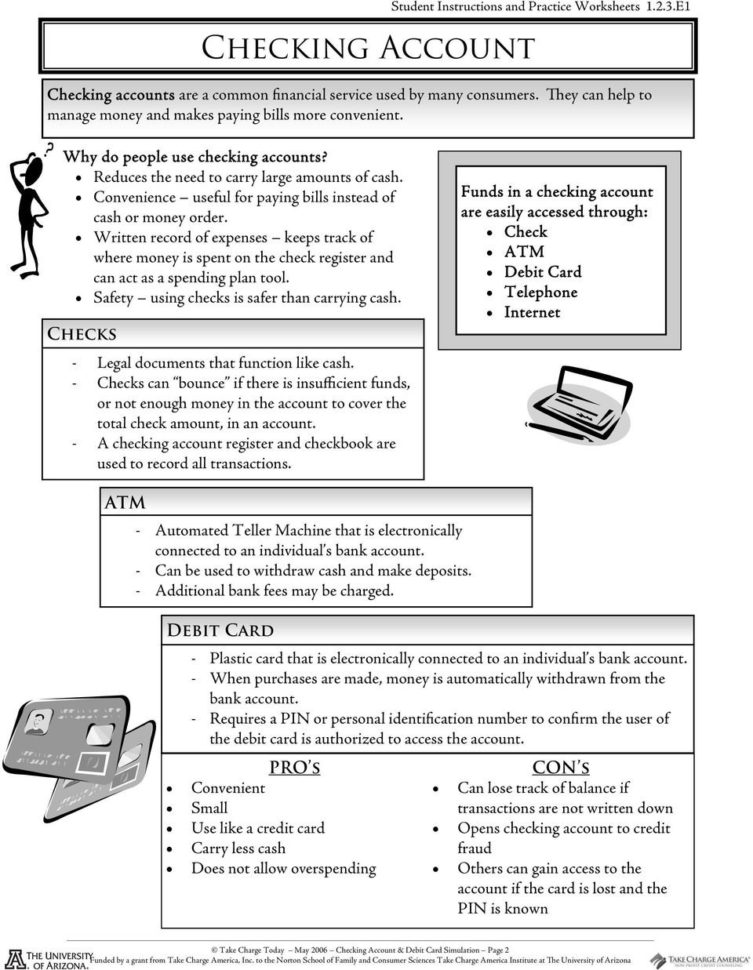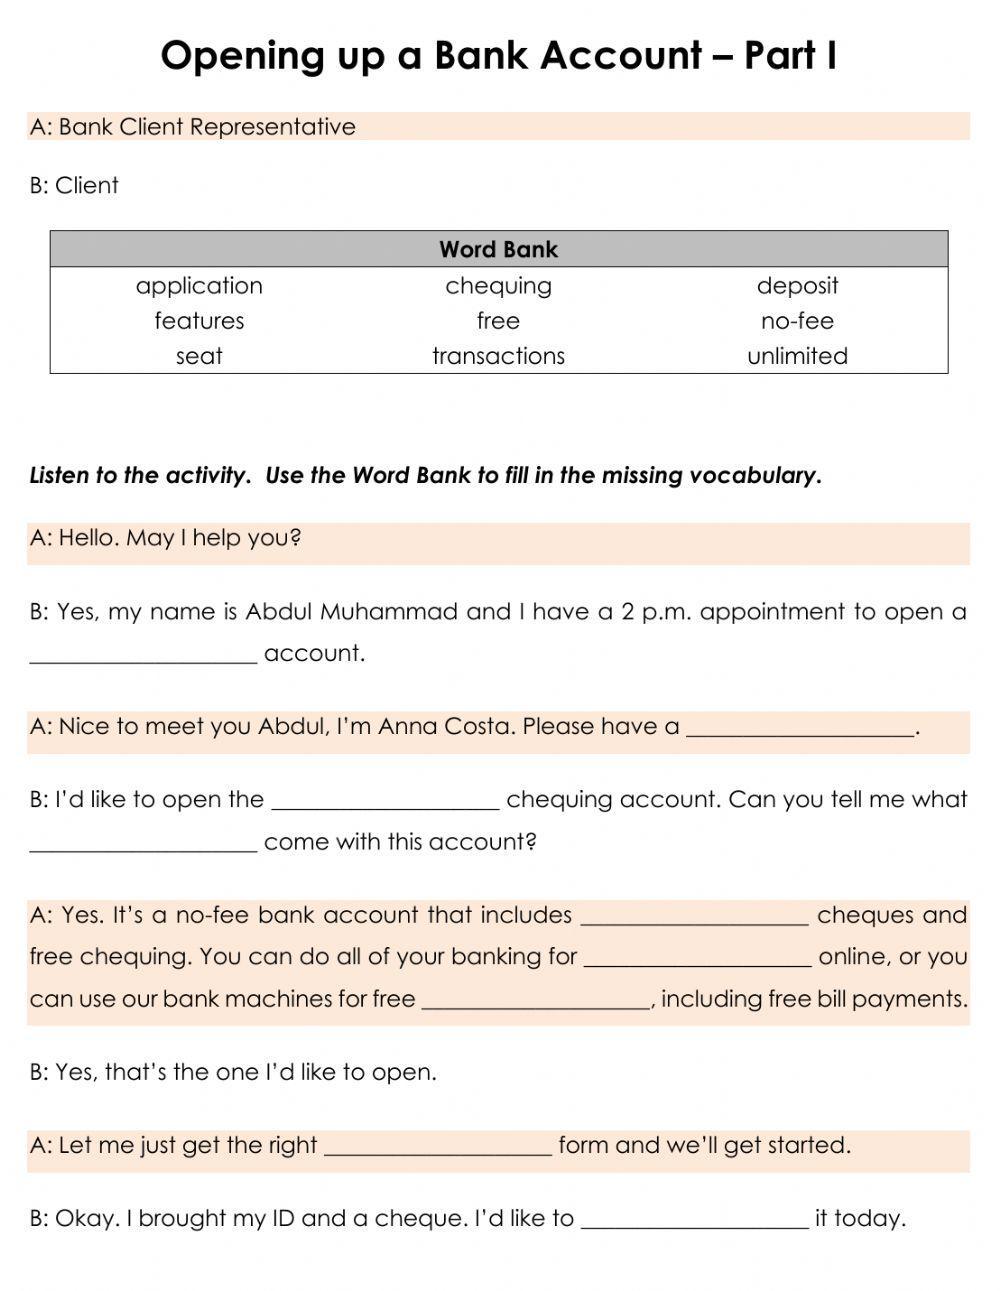
What Checking Account Worksheets For Students Actually Are
They're essentially printable or digital exercises designed to walk students through the mechanics of managing a checking account. Most follow the same basic format: you give learners a fictional scenario with a starting balance, a series of deposits and withdrawals, and ask them to track their account over a period of time. The goal is to make abstract concepts like maintaining a positive balance, understanding debit transactions, and avoiding overdraft fees feel concrete and calculable. I've seen these used in everything from middle school math classes to college-level personal finance seminars. The quality ranges from decent to genuinely helpful. Some are just repetitive arithmetic problems dressed up as "bank statements," while others actually simulate the decision-making process you'd face in real life.
Where to Find Checking Account Worksheets For Students
There are several reputable sources depending on your level and needs. TeachersPayTeachers has a massive selection at various price points. Khan Academy offers free financial literacy modules that include checking account practice. State education department websites sometimes publish their own worksheets aligned to curriculum standards. And a lot of community banks offer free educational materials for local schools, which tend to be more practically grounded than the generic ones found online. One important thing to look for: check whether the worksheet includes explanations of terms like "pending transactions," "automatic payments," and "debit versus ATM withdrawal fees." A good worksheet doesn't just ask you to subtract numbers. It forces you to understand why those numbers changed.
The Core Mechanics You Need to Know
At the most basic level, a checking account worksheet tracks three things: the starting balance, all transactions (deposits and withdrawals), and the running balance after each transaction. The standard formula is simple enough, but the nuances are where students typically struggle. The most common worksheet structure starts with a given balance, then lists transactions in chronological order. Students record each one and update the balance. By the end, they should arrive at a final figure. If it doesn't match the answer key, they go back and find where they made an error. This repetition builds accuracy and attention to detail, which are actually the two most important skills in real account management. More advanced worksheets introduce complications like NSF fees, monthly service charges, interest earned, and automatic bill payments. These are the elements that separate a basic arithmetic exercise from something closer to real-world financial literacy.
Get the Full Details
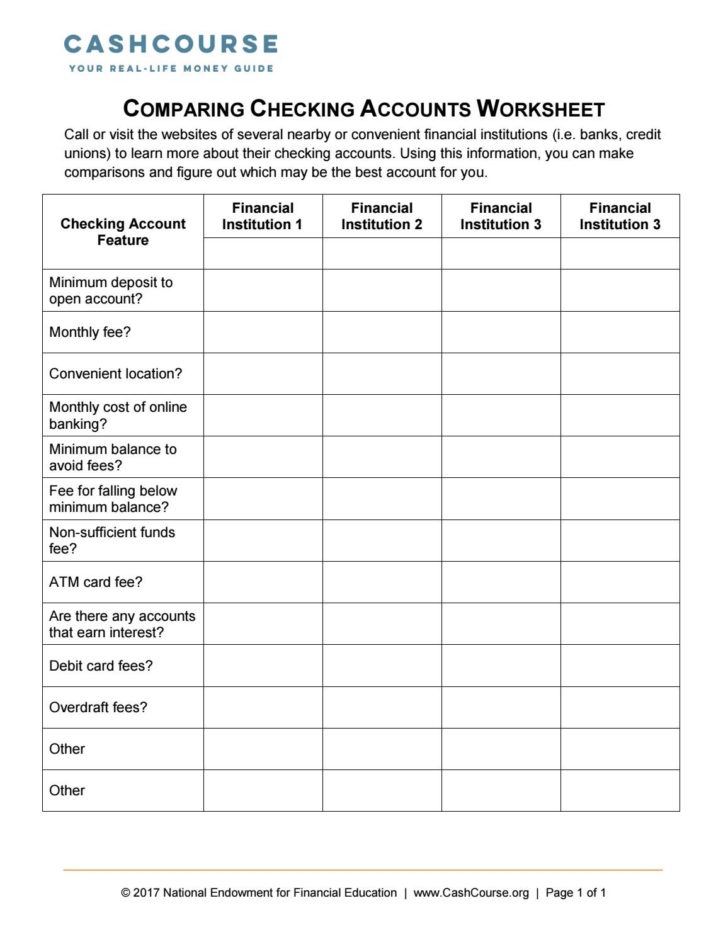
How I Actually Use These in Practice
I've designed and reviewed dozens of these worksheets over the years. The most effective ones I've encountered don't just present a clean list of transactions. They include a simulated bank statement image that students have to cross-reference. This forces them to read and interpret real banking language rather than just operating on isolated numbers. Here's a specific example that comes to mind. I was creating a worksheet for a adult education financial literacy program, and I ran into a problem with one of the practice scenarios. The worksheet included a check that was written for $147.32, but the transaction date was listed before the deposit date that funded the account. In a real bank, this would create a temporary negative balance until the deposit cleared, but the worksheet's answer key simply treated everything as simultaneous. This meant students who were actually trying to track the running balance correctly would arrive at a different number than the key showed. It confused everyone. The workaround I ended up using was straightforward. I redesigned that section to include a note explaining the timing difference and provided two possible answer paths: one assuming the deposit cleared first, and one reflecting the actual sequence. That way students could see both outcomes and understand that order of operations matters in banking. It added about twenty minutes to the worksheet development time but eliminated an entire category of confusion that had been showing up in student feedback.
Common Pitfalls That Beginners Miss
The biggest mistake students make on these worksheets is treating every transaction as if it clears immediately. In reality, checks can take one to three business days to clear, debit card transactions might post the same day or the next, and direct deposits often arrive on the same day but not always at the same time. Worksheets that ignore this gap create a false sense of certainty that doesn't exist in actual banking. Another frequent error is forgetting that fees compound. A single overdraft can trigger a fee, which drops the balance further, which can trigger another fee if it pushes the account below zero again. I've seen students who couldn't account for this on a worksheet with only twelve transactions. Multiply that by a month of actual banking activity and the problem becomes much worse. A less obvious issue is that many worksheets don't teach students how to reconcile an account. Reconciliation means comparing your own records against the bank's official statement to identify discrepancies. This is a skill that appears in virtually every real checking account situation, yet most worksheets skip it entirely. If you're using these as your only educational resource, you're missing a critical component.
The Limits of These Worksheets
Let me be blunt about what these tools cannot do. They cannot simulate the emotional stress of managing money when you're actually short. They cannot teach you how to prioritize bills when three are due at once. They cannot replicate the confusion of a disputed charge or the frustration of navigating a bank's mobile app while trying to figure out why your balance looks wrong. They also tend to assume ideal conditions. Perfect clarity in transaction descriptions. No hidden fees. No rounding discrepancies between your calculator and the bank's system. Real checking accounts are messier than any worksheet can represent. For that reason, I'd recommend pairing worksheet practice with actual hands-on experience. Open a real checking account with a small deposit. Track every transaction yourself using an app or a simple spreadsheet. Compare your records to the bank statement at the end of the month. The gap between doing worksheets and doing actual account management is where real learning happens.

Building Your Own Worksheet
If you can't find one that fits your specific needs, creating your own is not particularly difficult. Start with a realistic scenario: a student's first job, a part-time gig, an allowance, a mix of income sources. Set a starting balance that makes sense. Then layer in transactions that reflect actual decisions, not just arithmetic exercises. Include at least one situation where the person has to choose between spending and saving. That choice is what makes the exercise meaningful. Use realistic transaction amounts and descriptions. "Grocery Store" is better than "expense 1." "$43.87" is better than "$40." Small details matter because they train students to read actual banking language. When they encounter a real bank statement later, it won't look like a foreign document. Include an answer key with explanations, not just numbers. The explanation should describe why the answer is correct and what common errors might lead to wrong results. This turns the worksheet from a test into a teaching tool.
What to Look for When Evaluating a Worksheet
Check the source. Worksheets from certified financial education programs or accredited educational publishers tend to be more reliable than random downloads from file-sharing sites. Look for worksheets that include vocabulary definitions or a glossary. The ones that assume prior knowledge without providing it will frustrate students and slow down learning. Verify that the arithmetic checks out. This sounds obvious, but I've encountered worksheets with errors in the answer keys. If the final balance doesn't reconcile with the transactions listed, the entire exercise is useless and may actively confuse students. Cross-check a few calculations before assigning or purchasing. Consider the time investment. A well-designed worksheet should take between twenty and forty minutes for a student working independently. Anything significantly shorter likely lacks sufficient depth. Anything longer than an hour usually indicates either excessive repetition or unclear instructions that slow students down unnecessarily.
The bottom line is that these worksheets are a starting point, not a complete education in financial literacy. They build foundational skills in calculation, record-keeping, and basic understanding of how checking accounts operate. But they need to be supplemented with real-world practice and ongoing learning to be truly effective. The best students are the ones who use worksheets to build confidence and then test that confidence against actual financial decisions.