Accounting Checklists Don't Save You — Systems Do
I built my first real accounting checklist back in 2009 for a mid-market manufacturing client with three subsidiaries and a bookkeeper who treated GAAP like a suggestion. The list started as twelve items. It ended at forty-seven after the first audit flagged three separate reconciliations that had never actually been completed. That's the thing nobody tells you about these things: they grow. They always grow. The Checklist For Accounting Top 10 framework you'll find floating around is decent as a starting point, but it's incomplete if you're dealing with anything beyond a sole proprietorship with a single bank account. Below I'm laying out what the top ten should actually cover, the order I use, and the workaround I developed after spending a month trying to track down a $3,400 variance that turned out to be a duplicate invoice sitting in a vendor folder named "Miscellaneous 2017" — a folder I still haven't deleted.
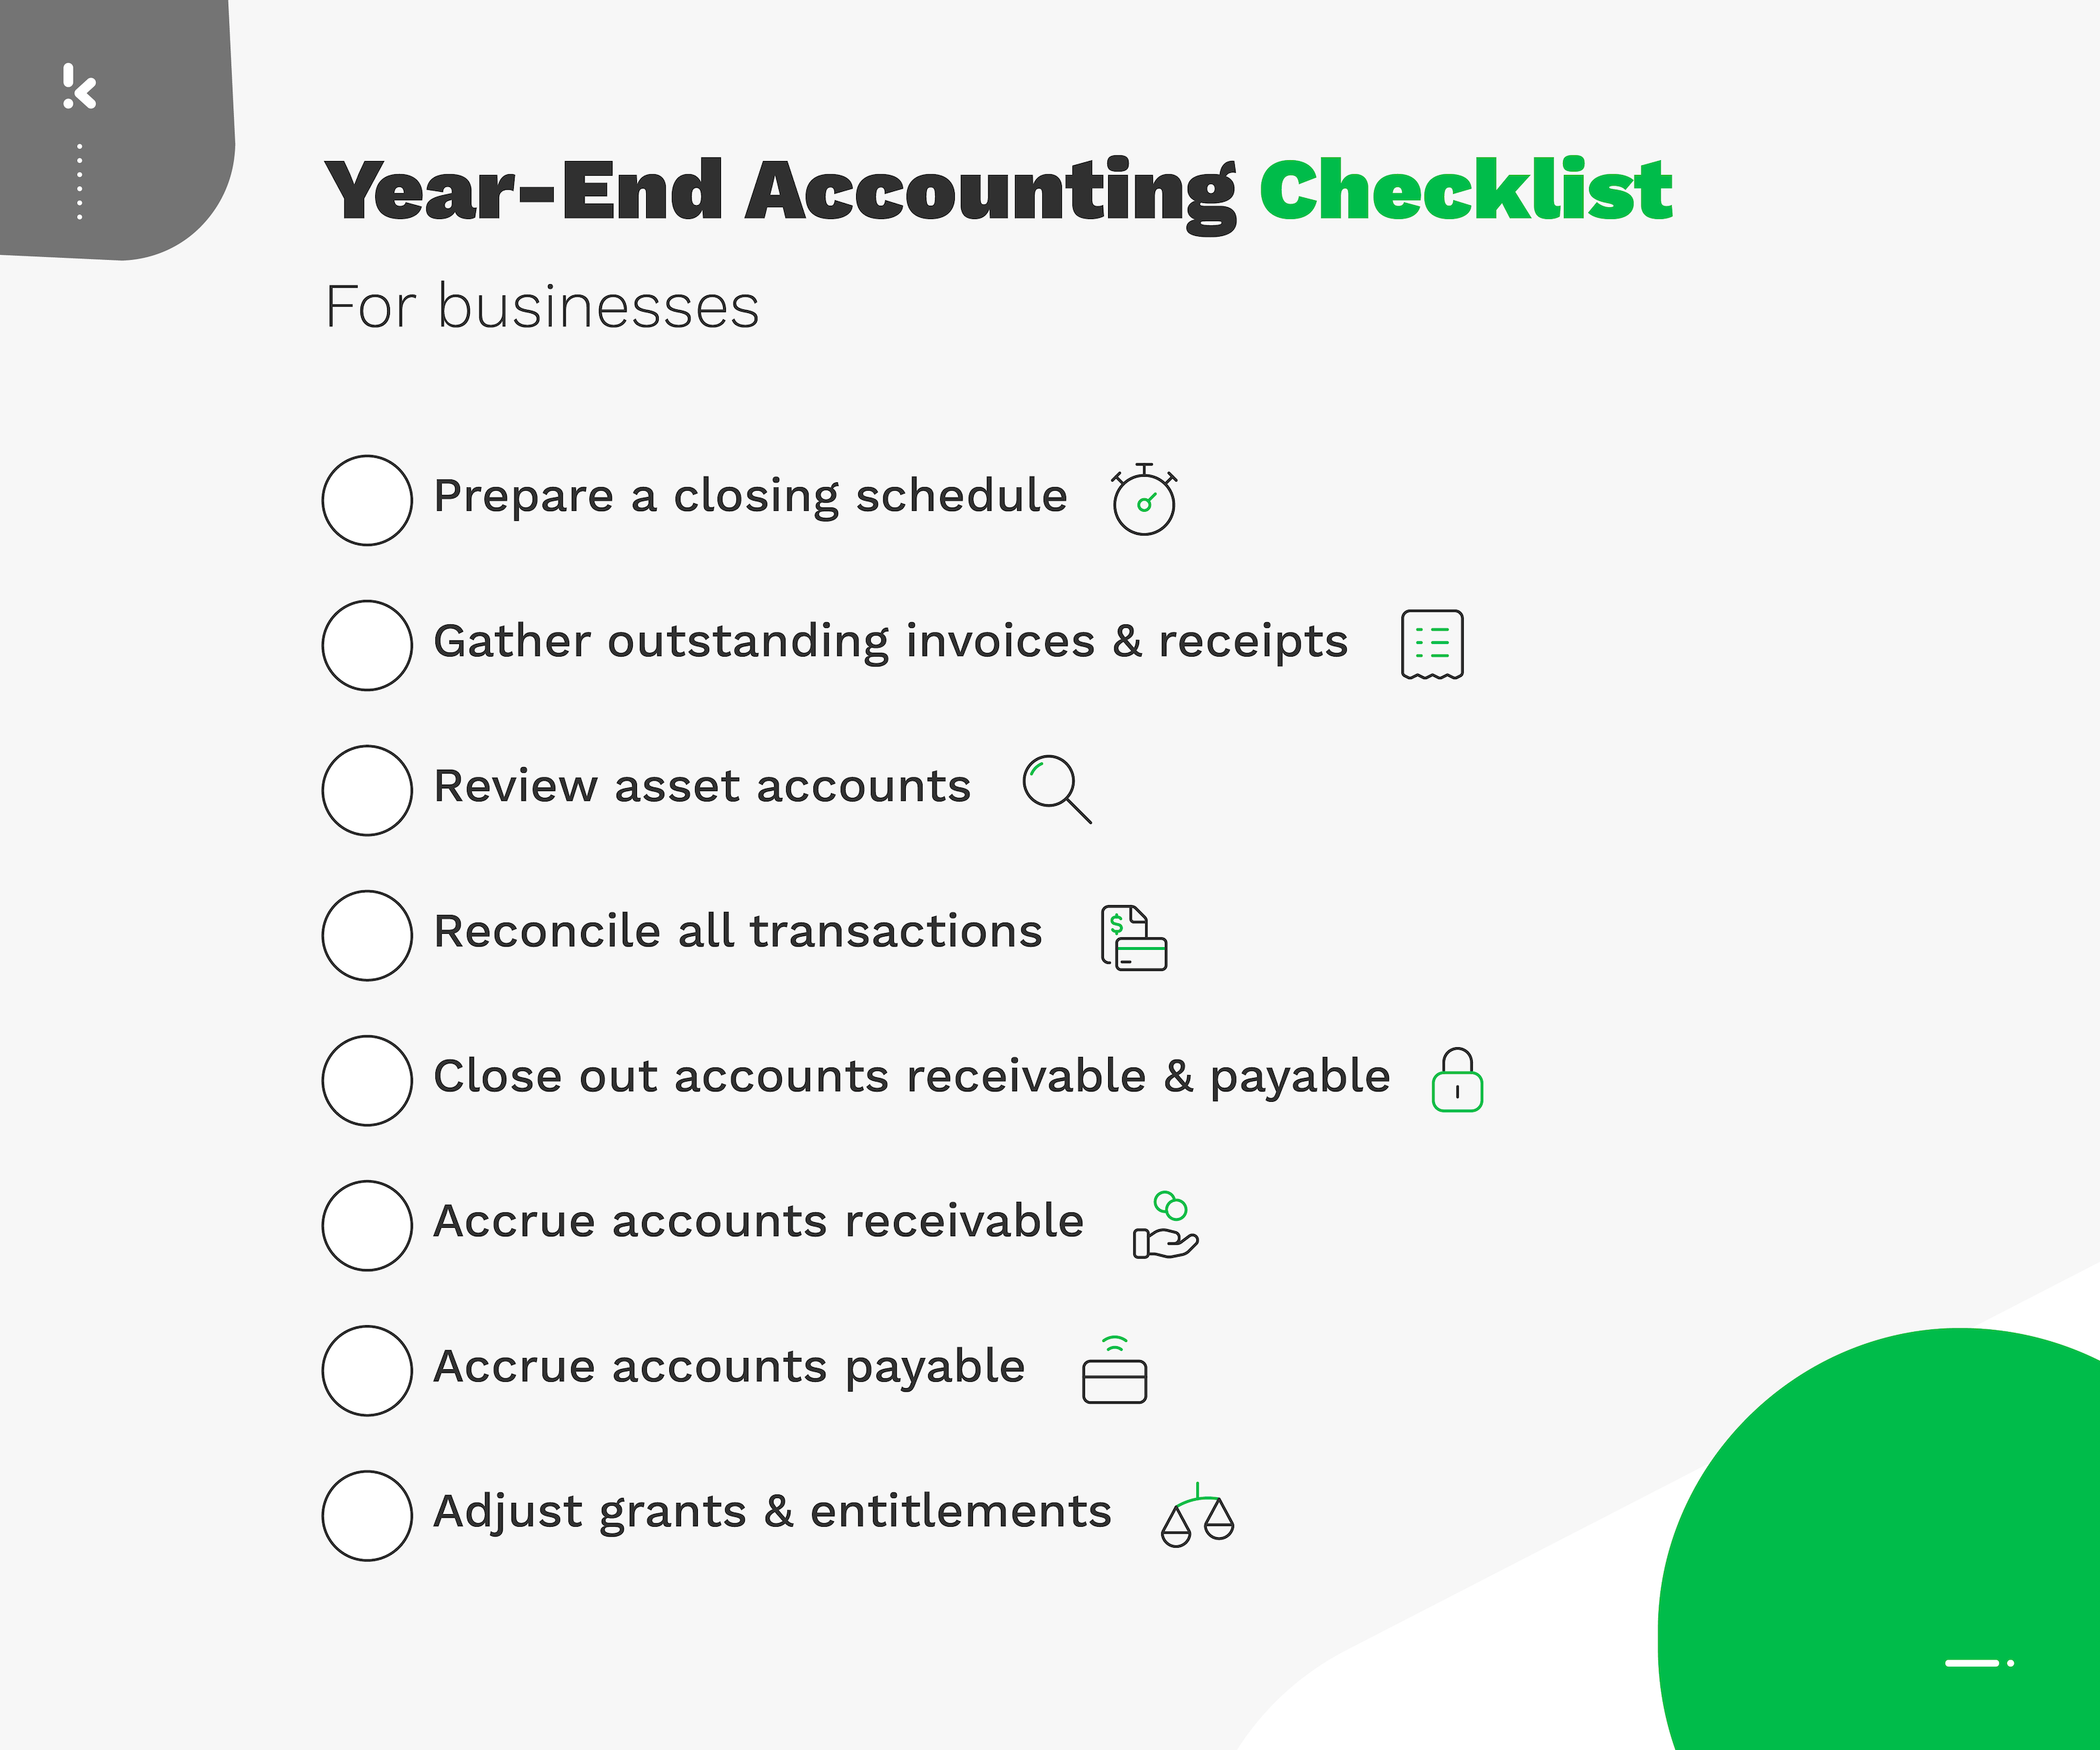
Checklist For Accounting Top 10
1. Bank and cash reconciliation — This is the foundation. Every account, every card, every petty cash drawer. Match your ledger to the actual statement. Note any outstanding checks over 90 days. In my experience, unrecorded bank fees are the most common item here, usually from dormant accounts the business forgot they had. Flag those immediately. They compound silently. 2. Accounts receivable aging and collection review — Pull the aging report. Verify each line against open invoices. Call out anything past net-60. I had a client once where $18,000 in receivables were listed as current because the invoicing system hadn't been set up with proper payment terms — the due dates were blank, so the system defaulted to zero days past due. The fix was rewriting the terms and manually backdating three months of correct aging. Took two hours and saved the engagement. 3. Accounts payable verification — Cross-reference open payables against vendor statements and recent invoices. Check for duplicate payments. This is where ghost vendors and duplicate entries hide. If you have more than two vendors with no statement matching, something is wrong. I keep a running list of every vendor I've ever audited a discrepancy with, and I check against it every cycle.
4. Payroll accuracy and compliance check — Verify gross-to-net calculations for a sample of employees, not just the highest earners. Check tax withholdings against current tables. Confirm overtime is properly recorded. If you're using a payroll processor, run their reports against your general ledger entries line by line. Mismatches between gross payroll expense and withheld liabilities are almost always timing issues, but not always. I found a case once where a new payroll provider stopped filing quarterly taxes for a six-month window and nobody noticed because the GL showed the liability had been paid. 5. Revenue recognition validation — This is where most small business owners accidentally violate revenue recognition principles. If you bill a client for a twelve-month service contract upfront and recognize it all as revenue in January, you're wrong. Spread it. Match revenue to the period the service was actually delivered. I worked with a SaaS company that was booking the entire annual subscription at signing instead of monthly, which inflated their Q1 numbers by three times and triggered a compliance audit from their lender. 6. Fixed asset register and depreciation review — Confirm all capitalized assets are on the schedule. Verify depreciation methods match what's documented in your accounting policy. Check for disposed or fully depreciated assets that are still on the books. Assets over $2,500 should generally be capitalized unless your policy threshold is higher. Track additions and disposals by quarter. A client of mine had a forklift that was written off two years prior still appearing on the depreciation schedule, which meant their expense was understated and their net income overstated by roughly $8,000 annually.
Get the Full Details

7. Accruals and prepayments — Review all accrued expenses at period end. Interest, utilities, wages earned but not yet paid. Check prepaid items and amortize them correctly. I once spent an entire week tracking down an under-accrued insurance expense of $12,000 because the premium was billed quarterly but the policy covered calendar months — the timing mismatch meant three months of coverage were never expensed in the right period. Going forward, I set up a spreadsheet that maps billing dates against policy periods automatically. 8. Tax obligation review — Sales tax collected versus remitted. Payroll tax deposits. Estimated tax payments. Make sure the numbers reconcile across all three. If you operate in multiple states, check nexus requirements. Missing a sales tax filing in one state while being current in another is surprisingly common and carries real penalty exposure. 9. Intercompany and multi-entity transactions — If you have more than one legal entity, every transaction between them needs to cancel out. I've seen intercompany loans that were never documented, transfers that disappeared into suspense accounts, and revenue allocations that had no business rationale. Document everything. Even the small stuff. A $200 transfer between entities with no memo looks like fraud on an audit.
10. Financial statement accuracy and completeness — Trial balance agrees to GL. Balance sheet balances. Cash flow statement ties to the balance sheet and income statement. Footnotes are complete. This sounds obvious but it's the item most often skipped because people assume the software did it. Software doesn't do it. You do it. I recommend running a final variance analysis comparing this period to the same period last year — anything moving more than 15% without a documented reason should be investigated before you close.
How to Use This in Practice
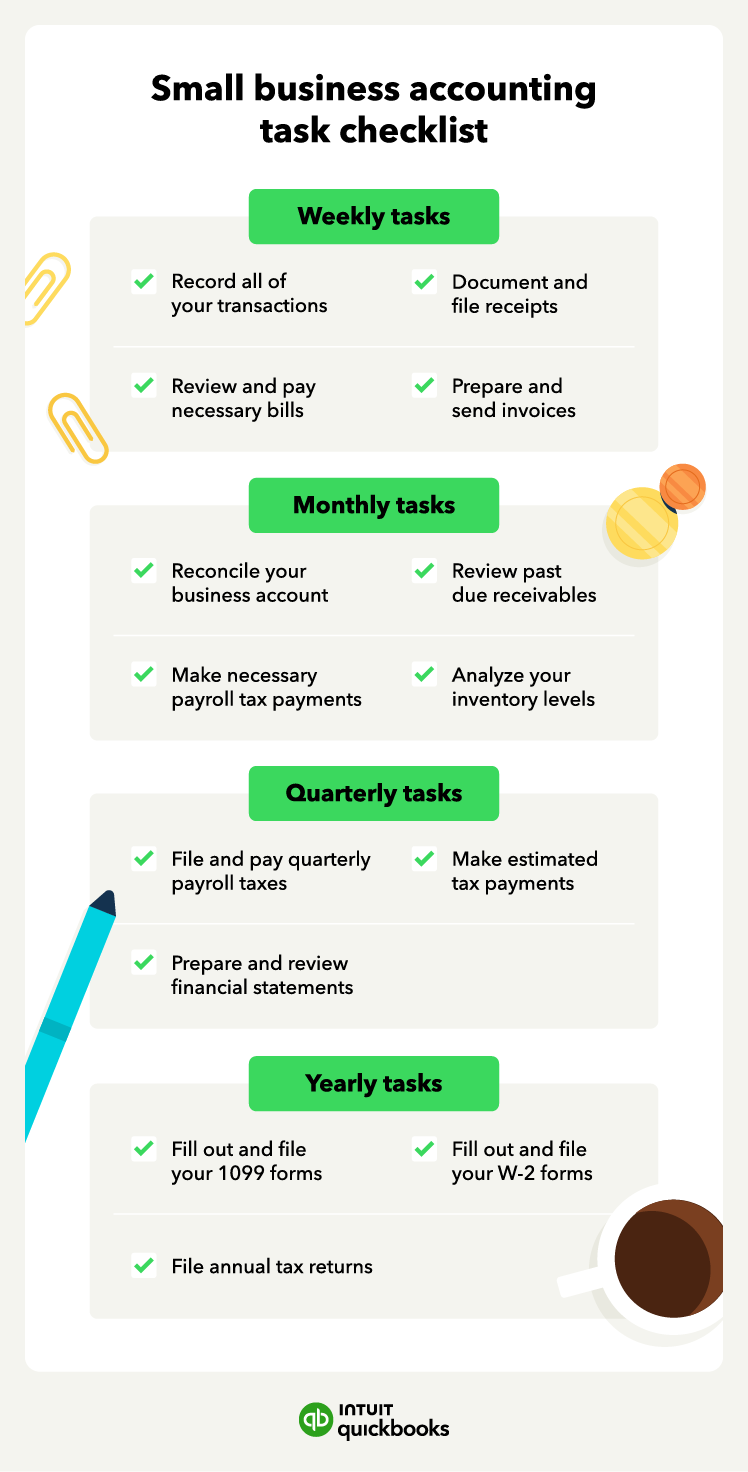
Print it. Put it in a binder. Go through it every month, not just at year-end. Monthly checklists take about ninety minutes for a small business with standard complexity. If yours is taking four hours, you're either doing something wrong or your processes need fixing. The checklist is a diagnostic tool, not a performance review. Assign each item to a person. Sign off with a date. If someone initials a reconciliation and it turns out to be wrong three months later, that signature matters. Not for punishment — for accountability and traceability. Auditors and lenders both want to see that trail.

Where Checklists Fail and What to Do Instead
A checklist won't catch everything. It won't catch intentional misstatements, and it won't catch systemic process failures. I've seen businesses with perfect checklists and fraudulent bookkeepers who manipulated entries after the reconciliation was signed. The workaround is surprise spot-checks — pick one item at random, outside the normal cycle, and verify it independently. Once a quarter is enough. Checklists also break down when your chart of accounts is a mess. If you have eleven different accounts for office supplies, no amount of checklist discipline will fix that. Consolidate your accounts first. Clean data beats clean process every time. And if your volume is high — more than fifty transactions per day across all accounts — a manual checklist becomes a liability. You'll skip steps because you're rushing. In that case, automate reconciliation where possible. Use tools that match transactions automatically and flag exceptions. My rule of thumb: if a step can be automated, automate it. If it can't, put it on the checklist and keep it simple enough that someone new can do it in under twenty minutes.
The Checklist For Accounting Top 10 is a starting frame. Build on it. Cut what doesn't apply. Add what your situation demands. The best checklists I've ever used evolved over three years of revisions, not one.