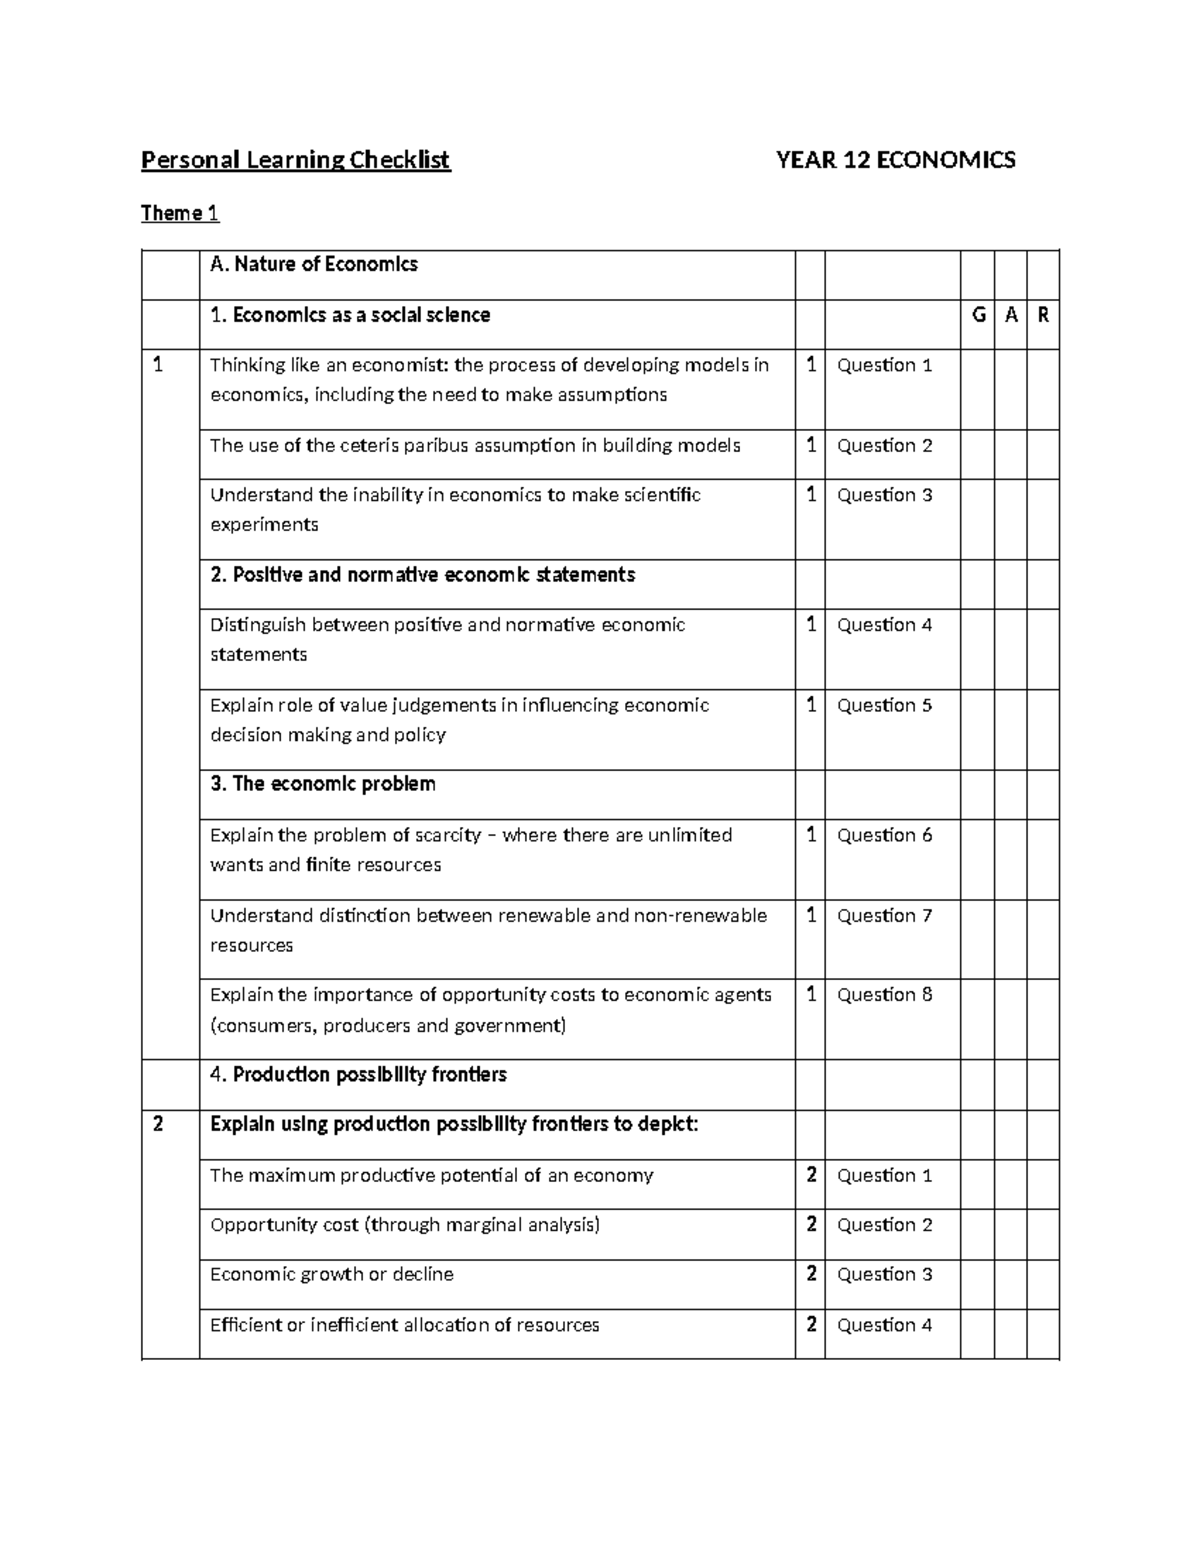
Yearly Economics Checklists: A Practical Guide
I spent years watching people waste weeks on annual economic reviews because they were using generic spreadsheets instead of proper checklists. The core issue is that economics isn't just about numbers, it is about the assumptions those numbers rest on. When you skip the second-order effects, you get clean-looking reports that fall apart under scrutiny. A yearly economics checklist is simply a structured document that walks you through every required verification step for an annual economic analysis. This covers data collection, model validation, sensitivity testing, documentation, and compliance sign-offs. The standard versions I have seen usually run between 40 and 80 items depending on the scope of your review.
Downloadable Checklist For Economics Yearly Template
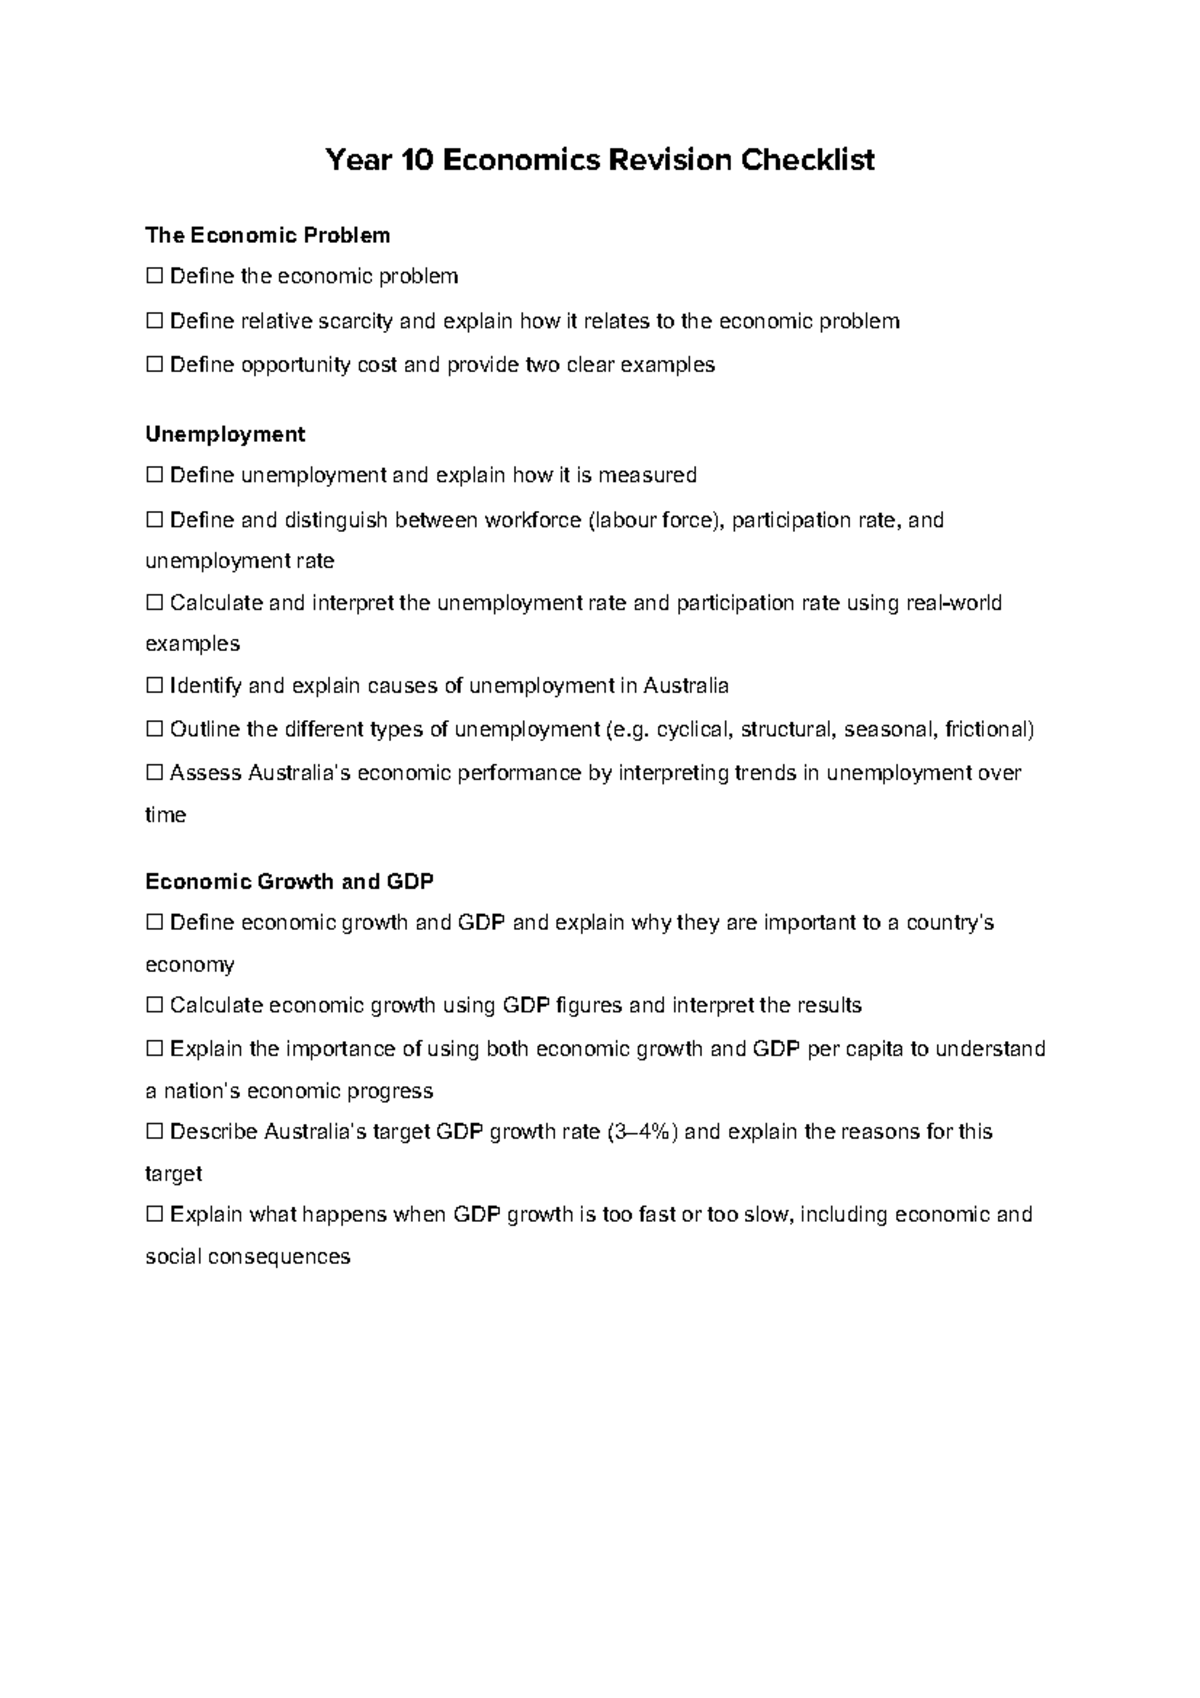
I put together a template that covers the core steps most teams end up redoing from scratch each year. You can grab it here: Checklist For Economics Yearly Template (PDF). It is free, no registration required. The file is organized into five sections: Data Verification, Model Assumptions, Sensitivity Analysis, Compliance Documentation, and Final Sign-Off. Each section has a status column and a notes field. I designed it so you can print it or fill it digitally depending on your preference.
How to Actually Use This Thing Without Losing Your Mind
Most people treat the checklist like a form they need to get through quickly. That approach usually leads to false positives on items marked complete. I recommend reading every line before you start, then tackling it in the order of the sections, not randomly jumping around. Start with the Data Verification section. This is where everything breaks if done poorly. You need to confirm that every data source matches the reporting period exactly. Mismatched fiscal years are the most common error I see. Someone will pull revenue data from one system and cost data from another, and those systems close their books on different dates. The discrepancy might be only a few days but it can shift your annual variance by enough to trigger an audit flag. Once the data section is clean, move to Model Assumptions. Write out every assumption you are building on. Even the obvious ones. Last year I was reviewing a client's annual model and they had silently changed their inflation assumption from 3% to 1.5% mid-year without noting it anywhere. The model output looked fine until I traced the numbers back to the source assumption sheet. I added a mandatory field for assumption change tracking in my revised template after that incident.
Get the Full Details
Common Pitfalls in the Model Assumptions Section
Beginners often assume that because the model ran without errors, the assumptions are reasonable. Running without errors only means the math works. It does not mean the inputs are defensible. You need to stress test at least two or three key assumptions by adjusting them significantly and seeing how the output shifts. A good rule of thumb is that if changing an assumption by 10% shifts your conclusion, that assumption deserves extra scrutiny. Another issue is confirmation bias. People tend to pick assumptions that support their preferred outcome. This happens subtly. You find yourself rounding a growth rate up slightly or choosing a more optimistic discount factor without realizing it. The checklist forces you to write the value down explicitly, which makes it harder to quietly nudge things in your favor.
Sensitivity Analysis That Actually Matters
Many teams skip thorough sensitivity analysis because it takes time and the output looks messy in reports. But this is the section that saves you during reviews. Regulators and auditors care more about what happens when things go wrong than they do about your base case projection. Run at least three scenarios: base case, optimistic, and pessimistic. For each, adjust the top five inputs by a reasonable range and record the output changes. Document the ranges you used and why you chose them. I once had a colleague who used plus and minus 5% for every input across the board. His models broke whenever any single input moved more than 5% from baseline. The actual market volatility for the assets he was modeling was closer to 20% on a bad year. His sensitivity analysis looked thorough but missed the real risk entirely.
Compliance and Documentation Requirements
The compliance section of your yearly checklist should cover version control, audit trails, and approval records. Every number in your report needs to be traceable back to a source. If you cannot point to exactly where a figure came from within thirty seconds, you have a problem. Keep all supporting files in one organized folder with clear naming conventions. The folder name should include the year and the version number, like Annual_Econ_Review_2025_v3. Sign-offs should come from the appropriate parties in a specific order. Usually the data analyst signs off first, then the model validator, then the finance lead, and finally the compliance officer. Do not let anyone sign before the section before them is complete. I have seen reviews fail because a compliance officer signed off on a model that had not been fully validated. The auditor immediately flagged that as a procedural deficiency regardless of whether the model was actually correct.

Limitations and When the Checklist Fails
No checklist catches everything. The biggest limitation is that a static checklist cannot account for genuinely novel situations that have not come up before. If your organization encounters a new type of transaction, a regulatory change, or a market shock that was not anticipated when the checklist was written, the document will not help you. In those cases, you need to pause, document the exception separately, and update the checklist for next year. Another limitation is maintenance burden. If you do not revisit and revise the checklist annually, it becomes stale and unreliable. An outdated checklist is worse than no checklist because it creates a false sense of completeness. I recommend scheduling a quarterly review of the checklist itself, not just using it annually. That way you catch items that need updating before the yearly crunch hits. Some smaller organizations try to compress the checklist down to twenty items to save time. This is usually a mistake. The compressed version tends to eliminate the detail-oriented steps that catch the subtle errors. A shorter checklist saves maybe two or three hours per year but costs significantly more in review rework and audit corrections.
Final Thoughts on Implementation
Getting the checklist working properly usually takes about three to four weeks of actual use before the team stops fighting it and starts finding it useful. The first year is always the hardest. People resist the extra steps. After that, it becomes routine and genuinely reduces the chance of oversight errors. Most teams that stick with it report cutting their review preparation time by roughly forty percent within the first two cycles. If your current process feels overwhelming, start by implementing just the Data Verification and Compliance sections for your next review. Add the Model Assumptions and Sensitivity Analysis sections in the following year. You do not need to adopt the entire system at once to get value from it.