How I Actually Use a Closing Cost Calculator for VA Loans
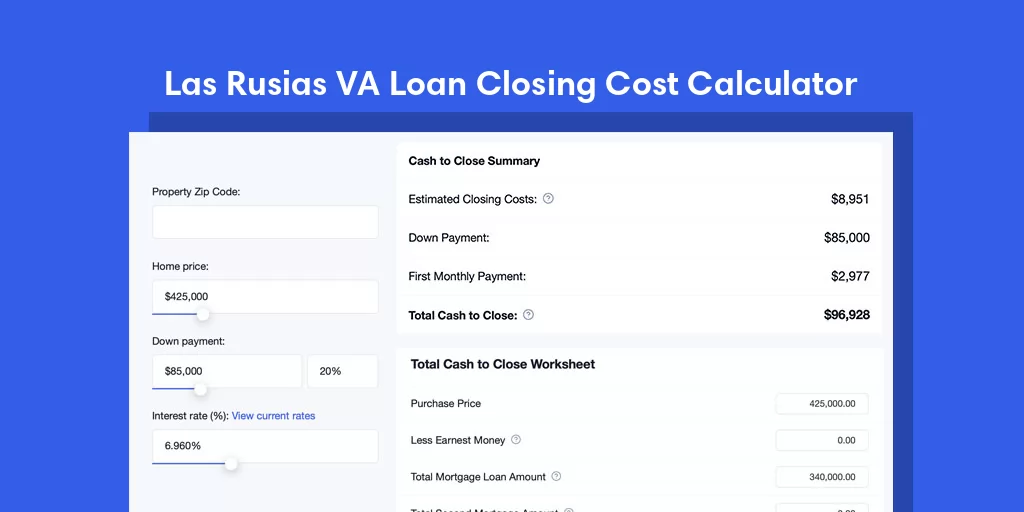
I keep running into the same problem with people who run a Closing Cost Calculator VA Loan estimate and then treat the number like gospel. It isn't gospel. It's a starting point, usually accurate to within a few hundred dollars if you're in a standard suburban county, and possibly off by a couple thousand if you're buying in a high-fee area or doing something unconventional with the transaction. A proper VA loan calculator breaks costs into two buckets: the VA funding fee and everything else lenders call closing costs. The funding fee for a first-time use with zero down sits at 2.3% for regular military and 1.65% for National Guard and Reserve. It drops to zero if you're a surviving spouse, and it's partially waived for veterans receiving compensation for service-connected disabilities. Most online calculators miss that last piece entirely. They'll give you the full funding fee number even when the borrower shouldn't pay it. The other costs are the ones people actually stress about. Appraisal runs about $500 to $900 depending on where you live. Title insurance varies wildly by county—some counties charge by value, others by a flat schedule, and a few don't require owner's title insurance at all on VA purchases. Credit report pulls, origination fees, recording charges, and prepaid items like property taxes and homeowner's insurance get layered on top.
Here's the part that trips people up every time: the VA allows the seller to pay up to 4% of the purchase price toward closing costs and prepaids. That's not 4% of the loan amount. It's 4% of the price. So on a $350,000 home, the seller can cover $14,000. That changes the math significantly compared to a conventional loan where seller concessions typically cap around 3%.
The One Time the Calculator Completely Failed Me
Back in 2022 I had a client who ran her estimate through a free online VA calculator. It came out to about $8,200 in closing costs. We were three days from closing when my underwriter flagged that the appraisal had come in $12,000 below contract price. The VA requires the difference to be handled at closing, and the calculator had zero line item for that. We ended up renegotiating the price down instead of paying cash, but the estimate was off by more than $10,000 and we were already deep in the process. After that I stopped trusting any calculator that didn't let you input the contract price separately from the appraised value. The ones that only ask for purchase price will give you a clean number until reality hits. Now I run two estimates side by side: the automated calculator for a baseline, and a manual spreadsheet where I pull actual fee schedules from the title company and lender I'm working with. That usually cuts the variance down to under 5%.
Get the Full Details

How to Get an Actual Number Instead of a Guess
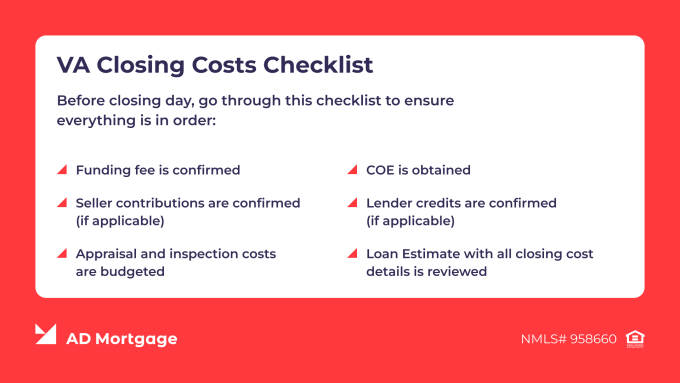
Start by entering your exact purchase price, down payment (if any), and whether you've used your VA entitlement before. Those three inputs determine the funding fee percentage. If you have a service-connected disability rating, verify with your lender whether you qualify for the funding fee waiver before running any numbers—that alone can save thousands. Next, ask your lender for a Loan Estimate within three business days of applying. That's the document that matters, not any calculator result. The VA requires lenders to provide it, and it's the only thing that reflects your actual rates and fees. I've seen discrepancies of over $2,000 between an online calculator and the Loan Estimate on the same loan, usually caused by lender-specific origination structures or local fee differences the calculator couldn't account for. If you want something faster than waiting for a Loan Estimate, the VA itself publishes a worksheet called the VA Loan Closing Cost Worksheet. It's available on their website and it's more detailed than most free online tools. You fill it out manually, but it uses actual VA fee categories instead of generic estimates. Takes about ten minutes and gets you closer to the real number.
Where Calculators Fall Short and What to Do Instead
Online calculators don't know your county. Recording fees in Fairfax County, Virginia, are completely different from recording fees in Maricopa County, Arizona. They don't know which title company you're using or whether your lender charges an underwriting fee or bundles it into the origination charge. They also don't account for special assessments, HOA transfer fees, or municipal transfer taxes that some cities impose on VA purchases. The workaround is straightforward. Run the calculator for a rough picture. Then call two title companies in the county where the property is located and ask for their fee schedule. Not an estimate—a written breakdown. Plug those actual numbers into a simple spreadsheet. You'll have a figure that's good enough to negotiate with and close with confidence. One more thing most guides don't mention: if you're refinancing an existing VA loan instead of buying, the cost structure changes entirely. Refinances don't involve appraisal fees, title insurance is often optional depending on the stream type, and the funding fee percentage differs. A calculator designed for purchases will give you misleading numbers on a refinancing scenario. Make sure you're using the right tool for the right transaction type.