Working Papers in College Accounting: What Actually Matters
College accounting courses don't just want you to arrive at a number. They want a paper trail that survives scrutiny from a grader who has zero interest in your mental math. The working papers document is where most students lose points, not because they can't balance the trial balance, but because the structure is messy or the cross-references are broken. I spent four years grading these at a community college, and the pattern was always the same. Students would get the final answer right and still tank the assignment because the working papers looked like a first draft. Let me explain how they actually work.
Getting Started with College Accounting Working Papers Answers
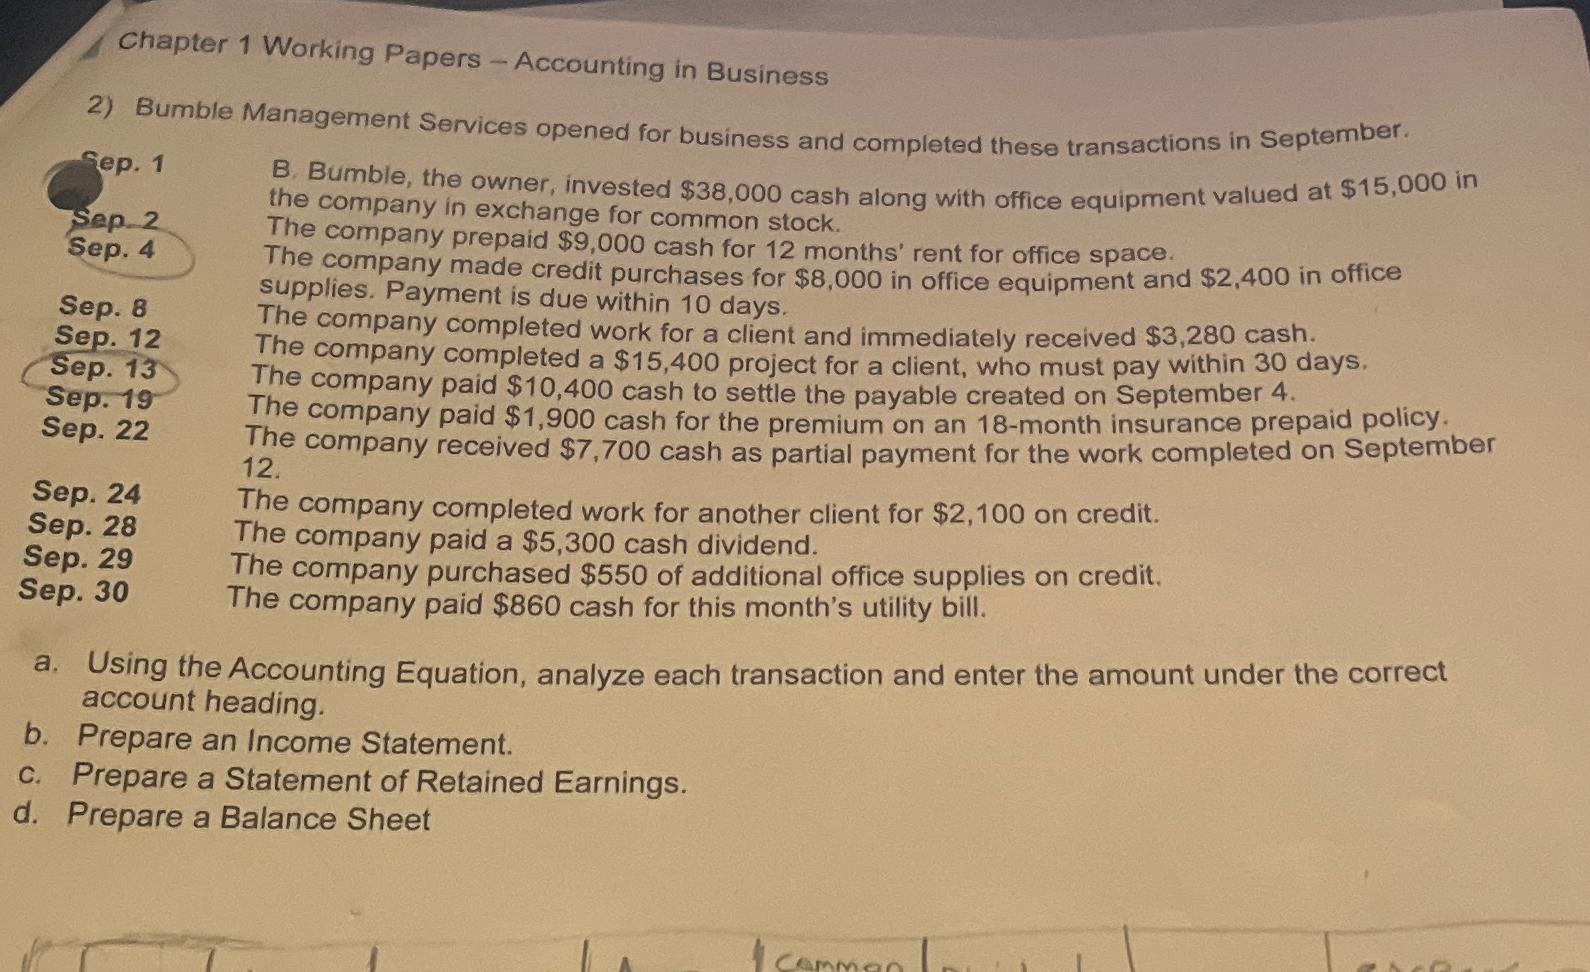
A working paper in an accounting class is a structured worksheet that shows every calculation step between the adjusted trial balance and the financial statements. Most textbooks use a standard format: columns for unadjusted trial balance, adjusting entries, adjusted trial balance, income statement, balance sheet, and sometimes a retained earnings column. The lettering system (A, B, C for adjustments; DR and CR for debits and credits) is non-negotiable in most courses. The core workflow runs like this. You start with the unadjusted trial balance figures from the problem set. Then you post each adjusting entry into the adjustment columns, making sure debits and credits within that entry balance to each other. After that, you carry the adjusted balances forward. Income statement items flow into the income statement columns, balance sheet items flow into the balance sheet columns. The net income or loss figure then transfers from the income statement columns to the balance sheet columns to make everything tie out. Here is where I see students mess up consistently. When you transfer net income to the balance sheet columns, it goes on the credit side if it is income and on the debit side if it is a loss. The direction matters. Get it wrong and your working paper will not balance, which means you have to go back and find the error. That usually takes twenty to forty minutes depending on how many adjusting entries there are.
I remember one student, let us call him Mark, who was working through a depreciation adjustment problem. The adjusted trial balance had accumulated depreciation listed as a credit balance of $12,400. The adjusting entry added another $3,200 to accumulated depreciation on the credit side. Mark calculated the new total correctly as $15,600 but then carried it into the balance sheet columns as a debit instead of a credit. The working paper was off by $6,400 between the two column totals. He spent nearly an hour hunting for the issue because he was only checking the arithmetic, not the placement. The fix was simply moving that line to the credit column. I tell that story because it happens constantly and it is completely unnecessary if you understand that accumulated depreciation is a contra-asset and always carries a credit balance throughout the entire working paper.
Get the Full Details
Practical Setup and Common Pitfalls
When you are building the working paper, keep your adjustment columns tight. Do not mix permanent account changes with temporary ones. Post all adjusting entries first, then do your extensions. This sequencing prevents you from accidentally carrying an unadjusted figure into the financial statement columns, which is probably the most common error I saw. It happens in about a third of all submissions. The lettering system exists for a reason. When grader looks at your paper and sees the same letter next to multiple amounts across different columns, they are verifying that you traced the figure correctly. A credit adjustment labeled "A" that appears in both the adjustment credit column and the income statement debit column is a red flag. The letter should only appear once per unique transaction flow. If you see the same letter duplicated in the wrong column, that is a red flag. If your working paper has three adjustments labeled "A," you have a problem with your tracking system. One thing that catches people off guard is the treatment of prepaid expenses and unearned revenue. These are balance sheet accounts that get adjusted, but they also appear in the adjusted trial balance columns and then extend to the balance sheet columns. Students sometimes try to extend them to the income statement columns because the adjustment affects an expense or revenue account. That is incorrect. The asset or liability account itself stays in the balance sheet. Only the adjustment entry touches the expense or revenue side. The distinction matters for the column totals.
Another edge case involves the income summary account in closing entries. If your course requires closing entries on the working paper, the income summary account starts with a zero balance, receives the revenue and expense transfers, and then the net balance transfers to retained earnings. Some students forget to include the closing step entirely and leave their working paper incomplete. Make sure you know whether your professor expects closing entries on the worksheet or just the adjusting entries. The format changes significantly either way.
When Working Papers Break Down
There are scenarios where the traditional ten-column worksheet format becomes unwieldy. Complex problems with multiple depreciation methods, intercompany transactions, or foreign currency adjustments can push a single worksheet past thirty columns. At that point, the paper becomes nearly impossible to read and grade accurately. I recommend switching to a spreadsheet-based working paper with separate tabs for each section, or using a supporting schedule approach where you maintain the main worksheet and attach detailed calculations on separate pages. Another limitation is that working papers assume a periodic accounting cycle. If you are dealing with rolling adjustments or real-time data from a simulation, the static worksheet format does not translate well. In those cases, a running journal with periodic trial balance reports serves better. Most college courses do not test this scenario, but it is worth knowing for practice. If you want examples and reference material, search for College Accounting Working Papers Answers along with your textbook chapter number. Most publishers provide supplementary worksheets in their online resources, and a lot of instructors post completed samples on course websites. Look for ones that include the lettering system and proper extension notation, since those details vary by professor.

The bottom line is that the working paper is a mechanical document. It rewards patience and careful sequencing, not creativity. Get the structure right, verify your columns before you finish, and double-check that every credit balance stays in a credit column. That alone will save you more points than any shortcut I could describe.