Why Most Online Mortgage Calculators Get Colorado Wrong
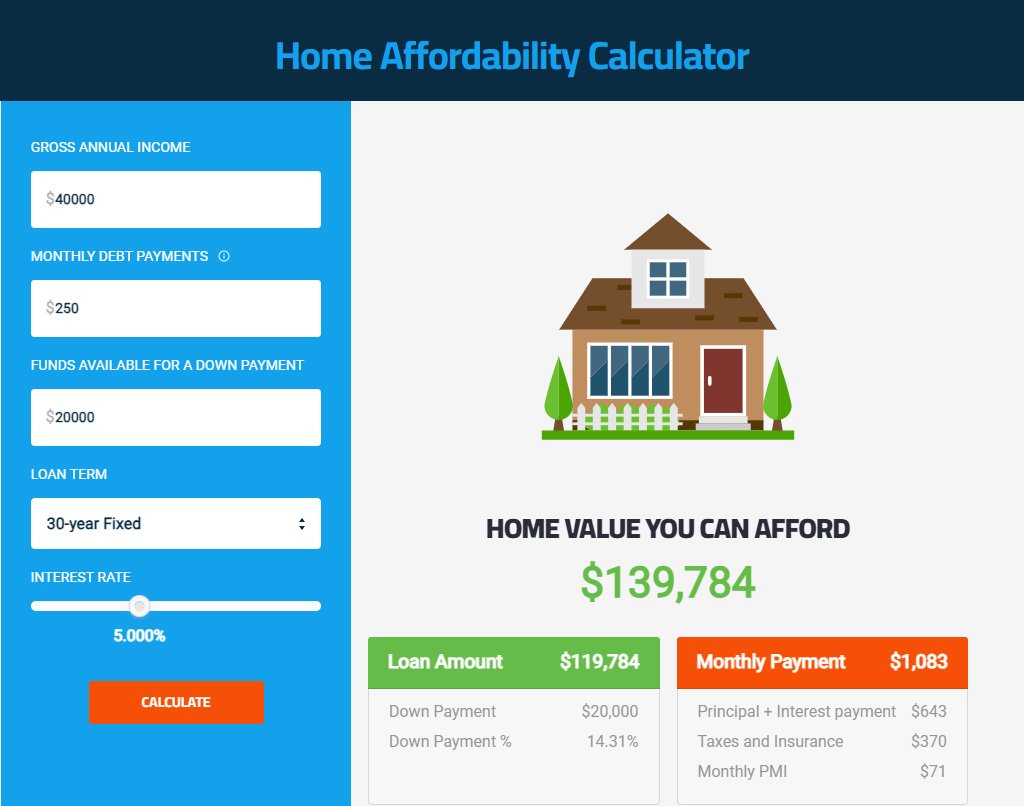
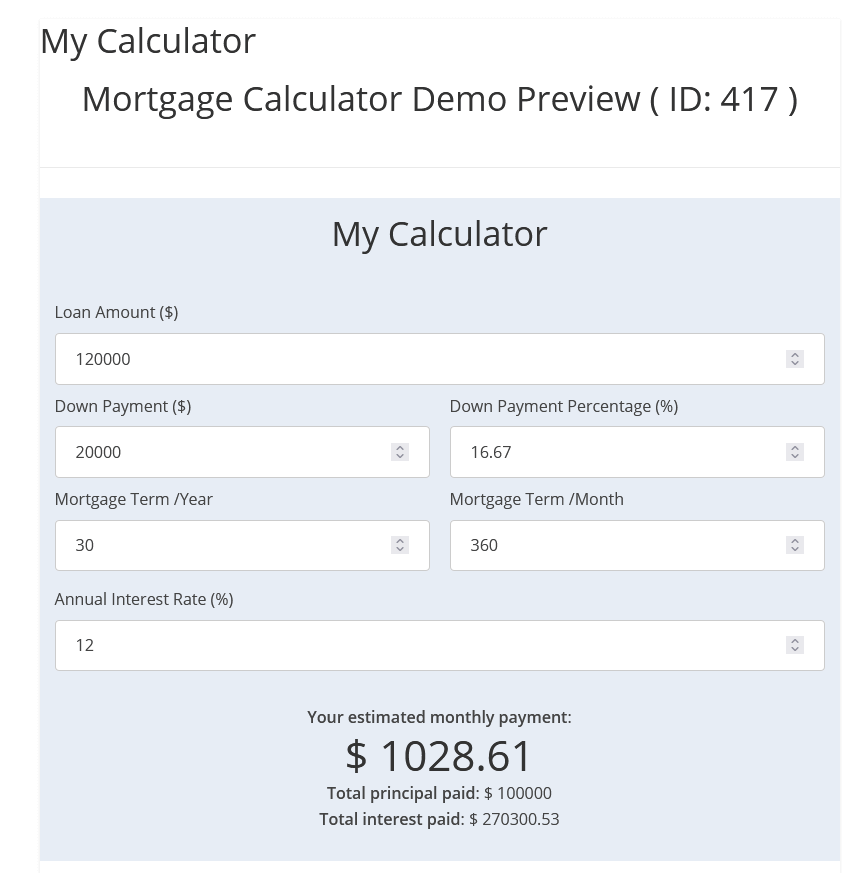
I spent years doing closings here before moving into consulting, and one thing that drove me crazy was watching people punch numbers into a generic mortgage calculator and then being genuinely confused when their actual closing costs didn't line up. The problem isn't the calculator itself. It's that most of them don't account for how Colorado structures property taxes, the assessment rate, and the way local governments handle HOA fees on new developments. The first thing you need to understand is that Colorado uses a statutory assessment rate, not a flat mill levy like some states do. Right now it sits at 7.15% for residential property, though it's scheduled to drift down toward 6.45% by 2030. That means the taxable value of your home isn't the full market value. A $500,000 home gets assessed at roughly $35,750, and the property tax bill comes from multiplying that assessed value by the local mill levy. Most calculators skip this entirely and just estimate property tax as a flat percentage of the purchase price, which can throw your numbers off by a couple hundred dollars a month depending on where you live in the state. When you're using a Colorado Mortgage Calculator, the fields you actually need to pay attention to go beyond the standard loan amount, interest rate, and term. You need to find or adjust the input for the assessment rate, because that directly affects what the tool reports as your monthly escrow for property taxes. If the calculator doesn't have that field, you're going to get a number that looks clean but is technically wrong for Colorado. I ran into this repeatedly with clients who'd gotten pre-approved based on a generic online estimate and then hit a wall at closing when the underwriter's numbers looked nothing like what they'd budgeted.
Here's the workflow I recommend. Grab the actual current market value from the county assessor's office for whatever neighborhood you're looking at — Don't rely on Zillow's estimate. Then look up the mill levy for that specific taxing district. Boulder County, Jefferson County, and Denver all run different rates, and within those counties you can have school districts and special assessed districts that push the mill levy up another 50 to 150 points. Multiply the assessed value by the mill levy and divide by 1,000 to get your annual property tax. Divide that by 12 and plug it into the calculator's escrow field. Another thing nobody bothers with: HOA fees in Colorado new construction. Front Range developments — the whole Denver Tech Center corridor, Lone Tree, Aurora's far east side — these places have HOAs that range from $200 to $800 a month on townhomes and condos. The calculator won't factor this in unless there's a dedicated HOA field, and even then you need to verify whether the HOA covers something like water or trash that the lender might otherwise include in your escrow analysis. I had a client in Westminster who almost lost her deal because her HOA was $620 a month and the bank's automated underwriting system had no way to account for it in the debt-to-income ratio. She ended up having to provide three months of HOA statements directly instead of relying on the disclosure form, which added five business days to closing. If you're looking for a tool that actually lets you adjust the assessment rate and input the real mill levy for your target county, search for a Colorado Mortgage Calculator specifically rather than a generic one. The ones that are Colorado-aware will have fields for assessment rate and will let you break out the tax calculation properly. Otherwise, use a generic calculator but do the property tax math yourself in a spreadsheet before you feed the number back in.
The Things Nobody Tells You About Colorado Mortgage Math
One counter-intuitive thing about Colorado mortgages that trips people up is the impact of the assessment rate change on refinancing. When the rate drops, your assessed value drops with it, which lowers your property tax bill even if your home's market value went up. I saw a client in Arvada refinance at a lower rate but actually end up paying less in total monthly housing costs than he was before, despite his home having appreciated significantly. The calculator numbers made it look like he was barely breaking even because the tool assumed a static tax figure. Once I recalculated with the actual assessment formula, the savings became obvious. The other thing is Colorado's specific exemption structures. Some counties offer homestead exemptions that cap the assessed value increase year over year for primary residences. Jefferson County, for example, has rules around how much your assessment can grow annually regardless of market swings. If you're buying an existing home in a county with this kind of protection, your property tax basis might be substantially lower than a brand-new purchase in the same area, even if both homes are worth the same today. A proper Colorado Mortgage Calculator should let you account for this, but most don't. In those cases, call the county assessor's office and ask what the current assessed value is versus the market value. That difference is your real data point, not whatever the listing price says. There are also scenarios where a mortgage calculator simply cannot help you. If you're dealing with a construction loan in Colorado, the disbursement schedule is tied to inspection milestones, not a standard amortization. The calculator will give you a monthly payment number, but that number is meaningless until construction is complete and the loan converts to a permanent mortgage. I've seen people get hung up on the construction phase payment estimate and completely overlook the fact that their permanent loan rate and terms hadn't been locked in yet. The conversion process itself can add three to four weeks to the timeline, and the rates often shift between the two phases. In those cases, you're better off working directly with a Colorado-based loan officer who understands the local construction lending pipeline rather than relying on any calculator output.
Get the Full Details
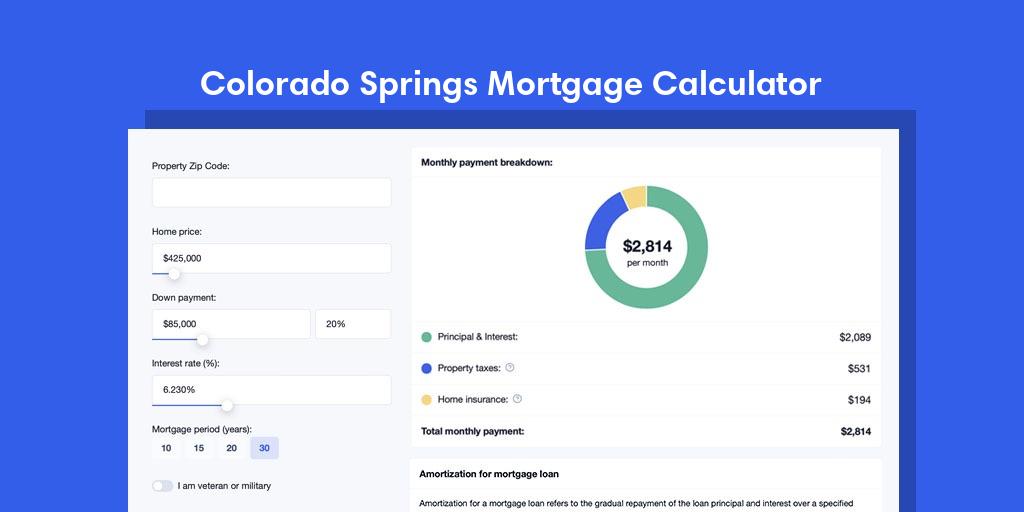
If your goal is just to get a rough monthly payment estimate for a standard purchase in metro Denver, any calculator with the right tax inputs will get you in the ballpark. But if you're buying in a special assessment district, dealing with a new construction HOA, or working with a non-traditional loan product, those tools start to fall apart fast. The numbers on screen are only as good as the assumptions you put into them, and Colorado adds enough variables to make blind confidence dangerous.