What Commercial Insurance 101 Training Actually Looks Like
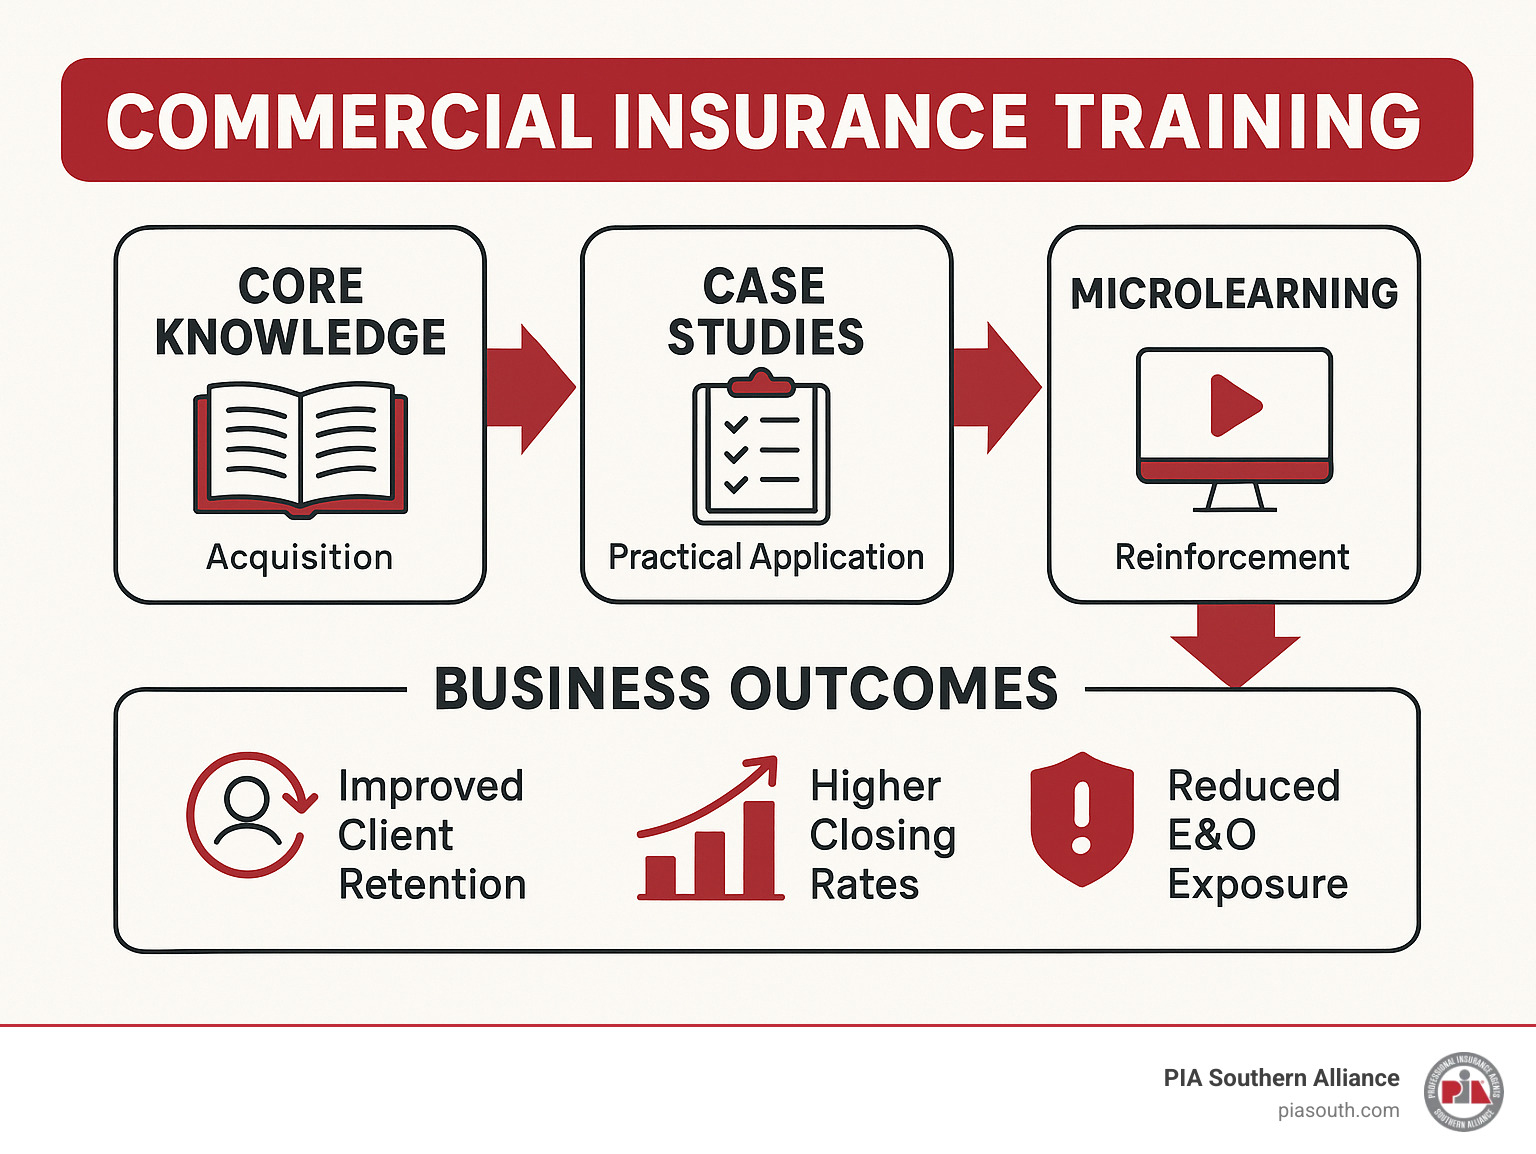
I've spent more years than I care to count watching people get thrown into commercial insurance work with zero preparation, then expected to bind coverage on their first day. It doesn't end well. Commercial Insurance 101 Training is the formal introduction to how commercial policies work, who they cover, and what happens when something goes wrong. The training itself is usually pretty basic. Most programs cover the difference between a business owners policy and a commercial general liability policy, how limits work, what an endorsement actually does, and the basics of subrogation and waiver of subrogation. That's it for the first session. Everything after that is where people start making expensive mistakes. The standard path is to work through a carrier's own training materials or an independent program like pre-licensing courses combined with internal onboarding. I'd recommend starting with the carrier portal for whichever line you're assigned to. Get the basic forms, read the declarations page of a real policy, and then go back and understand what each section means. Don't just memorize terms. Understand what the words actually do in practice. One thing that catches most beginners off guard is how much commercial insurance is state-specific. A standard CGL form in Texas is not identical to one in California. The ISO forms are a baseline, but every state files its own amendments. If you're putting together training for a new agent or underwriter, build in at least two weeks for state-specific rule absorption before they touch a live book of business. I've seen people skip this step and later realize they didn't know their state had eliminated broad form property coverage for certain classes of insureds without ever understanding why a quote was declining.
What You'll Actually Learn
A proper program covers policy structures first. You need to understand the four main parts of a CGL policy: the coverage grants, the exclusions, the conditions, and the declarations. That's where everything lives. The exclusions are what protect the insurer, and knowing them cold is what separates someone who can place a risk from someone who gets called by a claims adjuster three weeks after binding a policy that shouldn't have been bound. Then comes commercial property. Actual cash value versus replacement cost. Coinsurance is the big one here. It's the single most misunderstood clause in commercial insurance, and it's also the one that produces the most unpleasant phone calls after a loss. The formula is straightforward, but people skip reading it until it costs them a claim payout reduction of forty percent or more on a property claim. I had a situation a few years back where a client filed a fire claim on a warehouse and the adjuster applied the coinsurance penalty because the insured had undervalued the building by roughly thirty percent. The training materials barely dwell on this. The real lesson comes later when you're the one explaining to the agent why their insured is only getting partial payment. Commercial auto is another area where beginners gloss over the details. Schedule of coverage vs. any auto vs. scheduled autos matters more than most trainees realize. A mistake here can mean a vehicle that should have been covered isn't, or vice versa. It's easy to miss until a loss happens on an unscheduled truck that was being used for business purposes.
Practical Workarounds From Real Experience
Here's a specific edge case I ran into repeatedly during training and early career. New agents and even some experienced producers would call a risk and ask for a quote on a general liability policy, then hand over a W-2 classification code without any additional context. The quoting system would accept it, bind the policy, and months later a slip and fall claim would surface where the insured operated equipment that their NAICS code didn't reflect. The coverage was technically there, but the premium was based on a completely different risk class. The underwriter would downgrade the policy mid-term or even non-renew, and the producer would be left scrambling. The workaround is simple but not obvious from a basic training module. Always ask two additional questions before submitting a quote for commercial lines: what does the business actually do on a day-to-day basis, and do they own or lease any vehicles, equipment, or machinery that isn't listed on their standard operations. I started carrying a one-page checklist that I made agents fill out before any quote submission. It took about three extra minutes per account and it prevented at least a dozen misclassifications in my first year alone. The training program won't tell you to do this. It's something you pick up from watching the same mistake get repeated.
Get the Full Details
Counter-Intuitive Things That Aren't Taught Early
First, the cheapest policy is almost never the right one. During training, beginners obsess over finding the lowest premium. What they should obsess over is whether the coverage actually responds when needed. A policy with a $1 million limit sounds impressive until you realize the occurrence limit is $500,000 and the aggregate is also $500,000. Now every claim eats into the same bucket. The premium difference between that policy and one with a $1 million aggregate might be thirty dollars a year. The exposure difference is enormous. Second, endorsements matter more than the base form. Most commercial policies are built from ISO forms and then modified through endorsements to fit the specific risk. A blanket blanket burglary endorsement, an equipment breakdown endorsement, a cyber liability endorsement — these can completely change what's covered. Beginners often review the base policy form and miss the endorsements that alter the core coverage. I've seen claims denied because the insured thought they had coverage for stolen tools and equipment, but the endorsement that provided that protection was never attached to the policy.
Where Training Falls Short
Most entry-level commercial insurance training is weak on claims handling and strong on quoting mechanics. You'll learn how to generate a quote faster, but you won't learn how a claim actually flows through the system. You won't learn what a reserved rights letter looks like or why an adjuster might send one. That comes from doing it, usually after you've made a mistake that cost someone money. The other gap is understanding commercial workers compensation experience modification factors. The mod factor is what determines your final premium based on your claims history relative to your industry peers. Beginners rarely grasp how a single serious claim can inflate a mod factor for three full policy years. Training programs tend to treat this as a sidebar topic rather than the critical pricing lever it actually is.
A Note on Continuing Education
Once you complete initial training, keep going. The CIC and CIS designations from the Institutes are worth pursuing if you plan to stay in this space long-term. They cover commercial lines in enough depth that you stop guessing and start understanding. Online resources from ISO, CPCU materials, and carrier webinars are all useful. Don't rely on a single training source. The industry moves slowly but the regulations and forms change enough that stale knowledge will surface at the worst possible moment. If you're building a training program for a team, include a section on common audit findings from carriers. Producers who make the same errors repeatedly end up on audit lists. Learning what those errors look like before you encounter them personally is worth more than any general policy overview. I wish I'd seen a document listing the top ten filing mistakes carriers flag during audits before I started dealing with them myself.