What Actually Works in Commercial Insurance Sales Training
Most programs waste time on theory nobody uses. The brokers who close consistently did it because they practiced the hard conversations first, not after they had "learned" the product line. I watched a trainer spend forty-five minutes on ISO codes during an onboarding session while the new rep hadn't yet spoken to a single prospect. It's a common pattern.
Why Commercial Insurance Sales Training Often Fails New Reps
The issue isn't that people can't learn. It's that training programs teach quoting before they teach qualifying. A rep who knows how to run a submission but can't identify a serious risk in a first conversation burns through thirty minutes with a prospect who was never going to buy. That's the typical rookie mistake.
The sequence matters more than the content. When you flip the order and make the rep practice disqualifying leads before they ever open a quoting system, the whole training clock shrinks. I've seen reps who would have quit after three weeks of dead calls stay engaged when they realized early that most leads aren't worth their time anyway.
Here's a specific problem I ran into repeatedly: small commercial brokers love to send reps through generic sales courses that treat property insurance the same way as professional liability. One of my reps, fresh out of a bootcamp program, walked into a manufacturer meeting armed with coverage talk that didn't fit. The client was asking about equipment breakdown and business interruption triggers tied to supply chain exposure. The rep launched into a standard D&O pitch. The meeting lasted eleven minutes and went nowhere.
The workaround was simple but rarely taught. I pulled a one-page cheat sheet mapping common industry verticals to their actual pain points. Manufacturing got equipment breakdown first. Healthcare got cyber and medical professional lines first. Construction got GL and auto with inland marine add-ons first. The rep used that sheet for every subsequent call and came back two weeks later with a proposal that actually matched what the client needed.
The Core Structure That Actually Moves Revenue
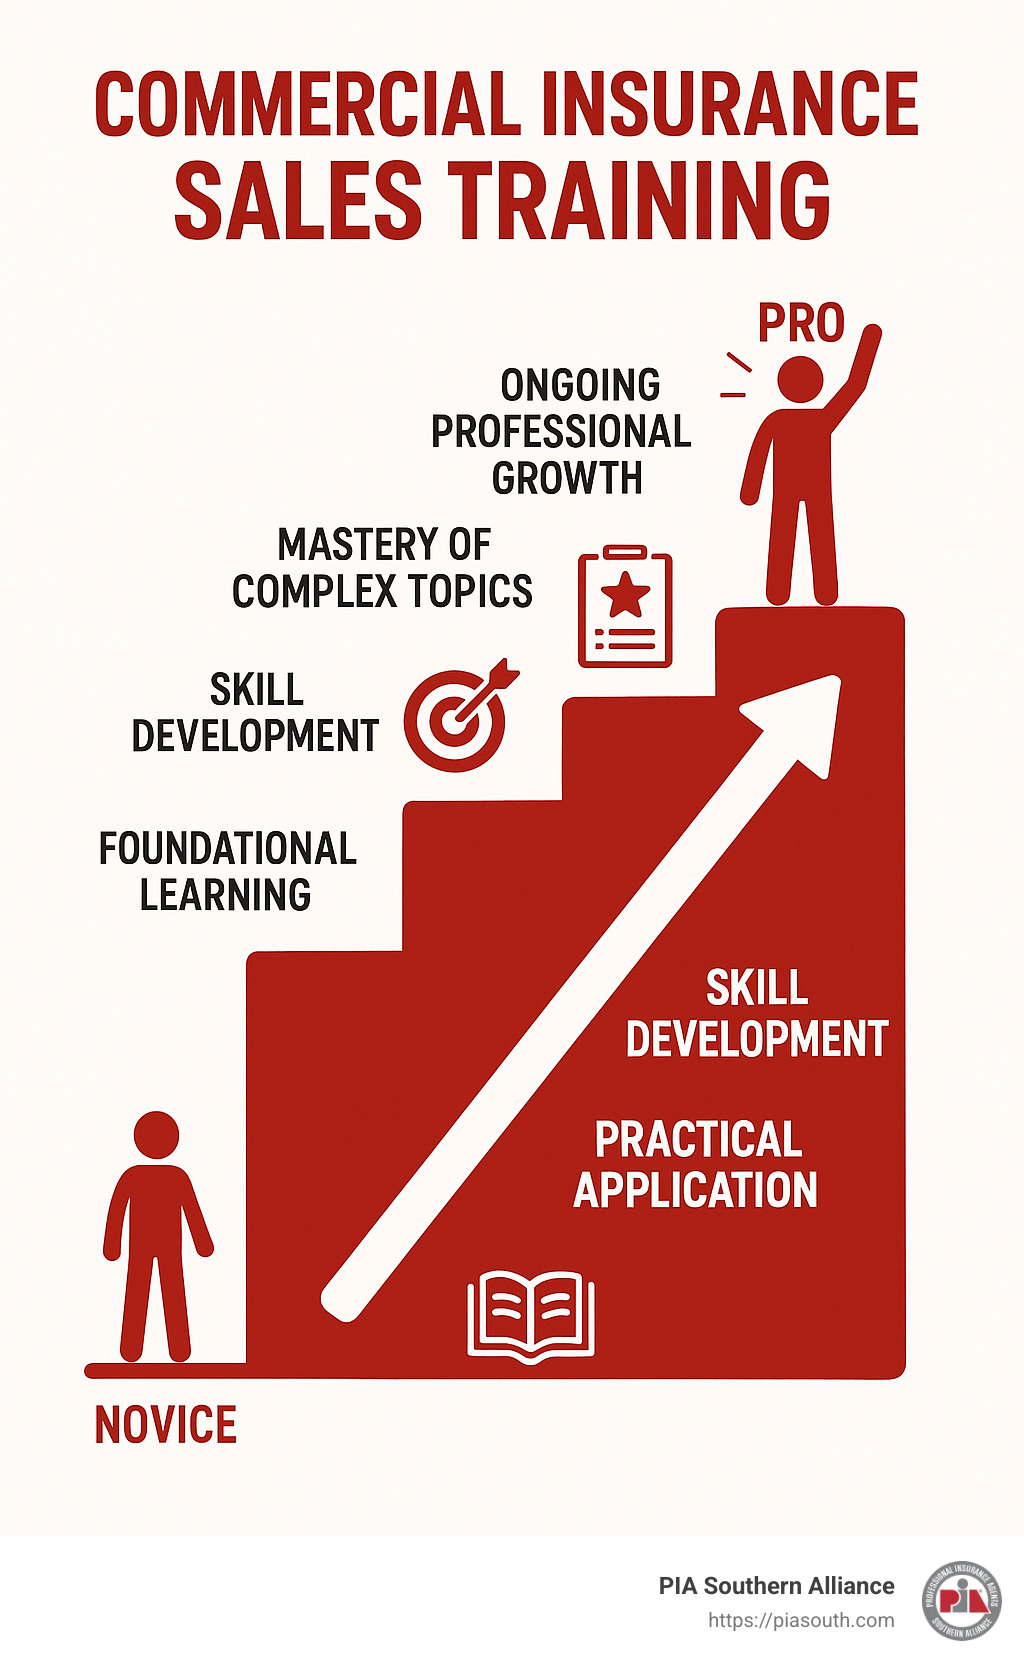
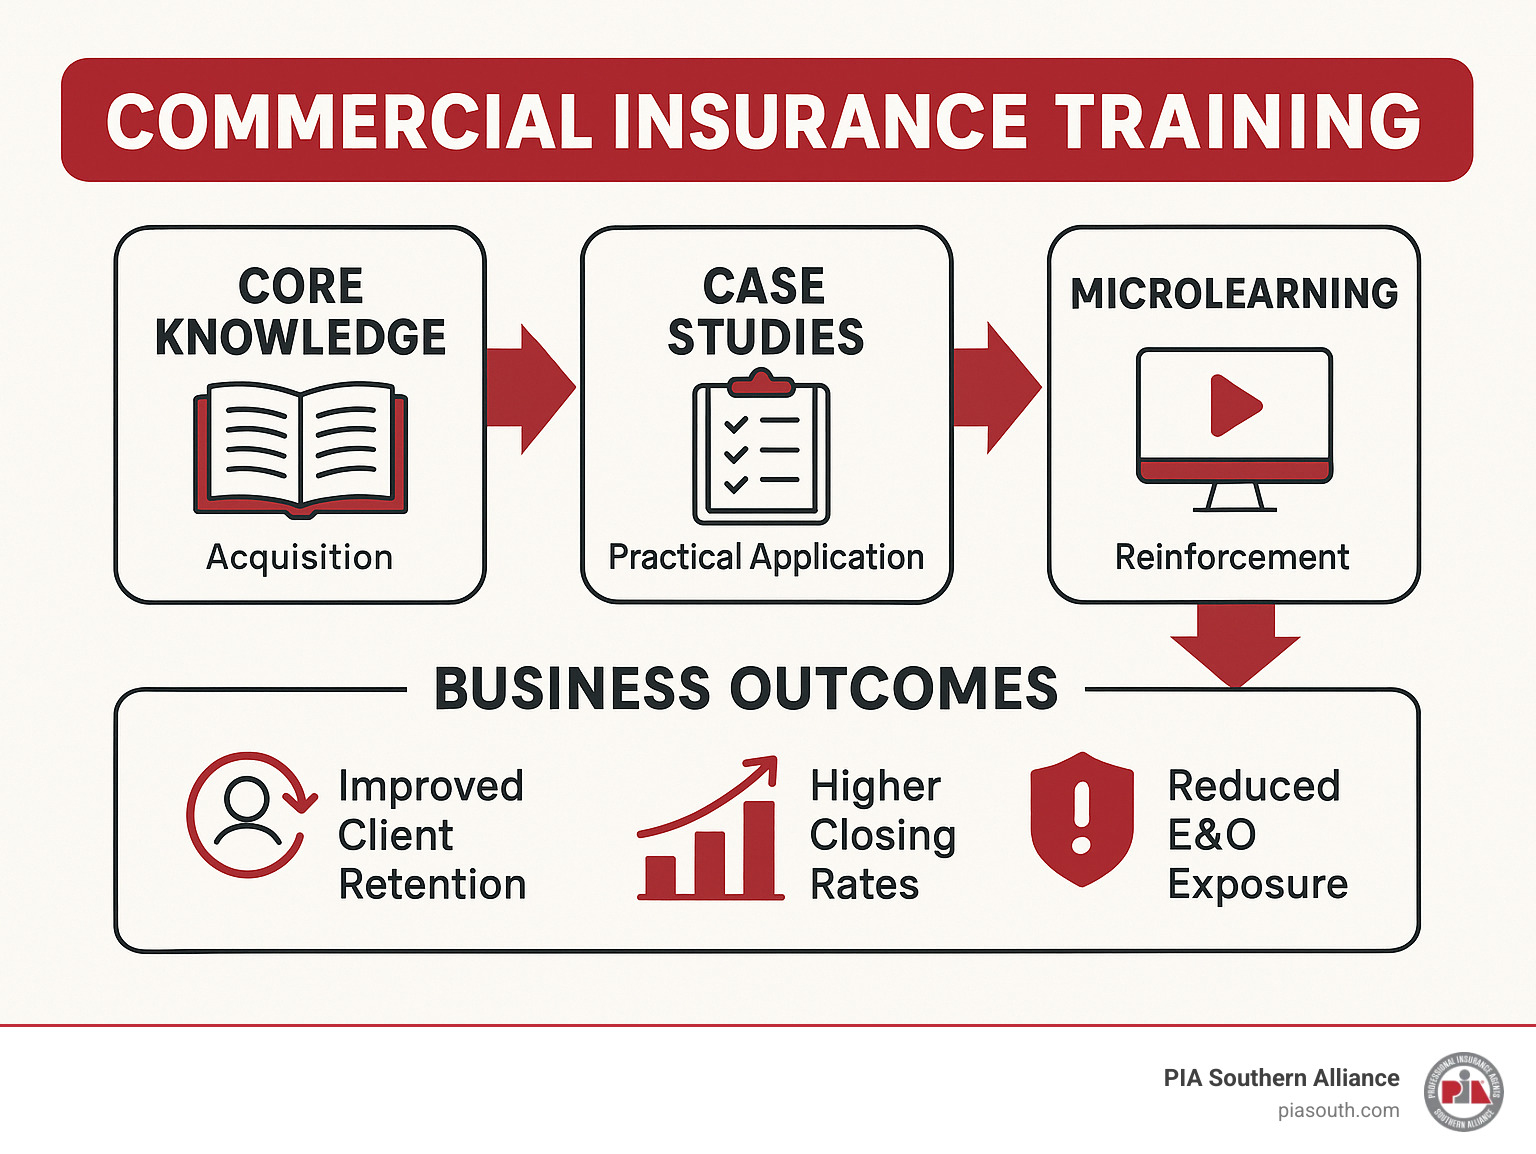
A workable training pipeline has three stages, and most programs skip straight to stage two without checking stage one.
Stage one is prospect literacy. Reps need to understand what makes a commercial lead worth pursuing. This means they can read a basic financial statement, recognize red flags in a company's growth story, and ask the right discovery questions before they ever mention a premium or a deductible. It's not optional. I've had reps miss a $40,000 annual book because they didn't catch that a retail client had three locations with different ownership structures, which changed the entire underwriting picture. Stage two is risk analysis and needs assessment. This is where most training falls apart. Reps are given product brochures and told to memorize coverages. What they actually need is practice reading loss runs, interpreting OSHA records, and asking the kinds of questions that reveal exposure gaps. A restaurant owner who says they need general liability might actually need a food contamination endorsement and liquor liability. You won't find that out until you ask the right questions in the right order. Stage three is presentation and close. At this point, the rep should already know enough about the prospect to tailor the conversation. Training should focus on how to walk a business owner through a coverage summary without overwhelming them with jargon. The best reps I've worked with kept their presentations under ten minutes and spent the rest of the time answering questions. They didn't talk at clients. They talked with them.
Commercial Insurance Sales Training for Different Experience Levels
New reps need something very different from someone who's been in the field for five years and is trying to move into commercial lines. A veteran agent switching from personal lines doesn't need to learn how to build rapport. They need to learn how to read a balance sheet and understand what a certificate of insurance really means in a contractual context.
The training path should reflect that gap. I've put experienced producers through a two-week commercial immersion that focused entirely on underwriting guidelines, risk selection, and submission writing. They learned the products through case studies instead of lectures. Meanwhile, a brand-new hire spent six weeks just doing role-play exercises before they ever touched a carrier portal.
There's no universal timeline. Some people absorb commercial concepts quickly because they come from a financial services background. Others struggle with the language because they've never worked in B2B sales. The training has to adapt, and most programs don't do that.
Practical Tools That Actually Get Used
The best training programs give reps tools they'll reference while working, not binders they file away. A quick-reference guide for common commercial lines covers, a decision tree for determining which sub-lines apply to a given industry, and a template for initial discovery calls are the three things that show up in real workflow.
I built a simple spreadsheet that tracks lead source, industry, estimated annual premium range, and competitive landscape. Reps update it after every call. It sounds basic, but it forces discipline. You can't qualify properly if you aren't writing down what you learned. I've seen reps forget critical details from a conversation because they relied on memory alone. That's how deals slip.
Carrier portals vary widely. Some are intuitive. Some take weeks to master. Training should include hands-on time in each system you use, not just a tour of the interface. I had a rep spend three days trying to figure out why a quote wasn't submitting. The problem was a missing NAIC code on the entity form. The portal gave no error message. He would have saved himself three days if he'd practiced building submissions during training instead of learning by doing it live with actual prospects.
Common Pitfalls That Kill Momentum
The biggest trap is treating training as a finite event instead of an ongoing process. Insurance products change. Underwriting guidelines shift. Carriers modify ratings. A rep who finishes a program and never revisits the material falls behind within six months.
Another pitfall is over-reliance on scripting. Scripts help when you're nervous, but they also make reps sound robotic. Commercial buyers can spot a rehearsed pitch instantly. The best approach is to teach principles, not word-for-word scripts. Give reps a framework for conversation flow and let them fill in the details naturally.
Price-focused objections are the third major hurdle. New reps default to discounting when a prospect pushes back on premium. That's the wrong move. Commercial insurance is a risk transfer product, and price is only one factor. A rep who can articulate why a higher deductible with stronger limits made sense for a specific client outperforms one who simply lowers the rate.
When Commercial Insurance Sales Training Doesn't Work
Some situations can't be trained out of a rep. If someone lacks curiosity about how businesses operate, no amount of coursework will make them effective in commercial lines. Commercial insurance is fundamentally about understanding risk in a business context. Without that interest, the rep will surface-level every conversation.
Remote-only training also has limits. Role-play over Zoom doesn't capture the same dynamics as in-person practice. Body language, tone shifts, and the ability to pivot mid-conversation are harder to develop through a screen. I've found that hybrid models work best: online modules for product knowledge, followed by in-person sessions focused on live practice and feedback.
There's also the issue of manager involvement. Training fails when the rep's supervisor doesn't reinforce what was taught. If the manager isn't reviewing call recordings, providing real-time feedback, or setting realistic activity expectations, the training erodes quickly. I've seen solid onboarding programs undone by a manager who treated the first ninety days as a probationary period instead of a development period.
The numbers matter too. A rep generating fewer than three qualified conversations per day during training is usually struggling for reasons unrelated to the program itself. Whether that's lead quality, territory assignment, or personal fit, the training won't fix it. Recognizing that early and adjusting assignments or moving the rep to a different role saves everyone time.