Building a Working Commercial Lease Analysis
Most people approach lease analysis by opening a spreadsheet and starting to plug numbers in. That is backwards. You need to understand what the lease is actually doing before any cell contains a formula. I spent years watching deals get buried under templates that looked impressive but missed the actual economic substance. The document itself is the source of truth. Everything else is a translation layer. A commercial lease is not a single number. It is a collection of obligations, triggers, and timing clauses that interact in ways most people miss on the first read. The lease itself will bury critical details in definitions, exhibits, and supplemental agreements. Your template needs to surface all of them. The core components you must extract are the base rent amount and its escalation schedule, the operating expense reimbursement structure, the CAM reconciliation process, tenant improvement allowances and build-out obligations, rent abatement windows, options to extend or renew, co-tenancy clauses, exclusivity restrictions, and the maintenance responsibilities split between landlord and tenant.
That last piece, the maintenance split, is where deals quietly shift value. A lease that appears to have identical base rent can have a $40,000 per year difference in actual cost depending on whether the tenant is responsible for roof maintenance or the landlord is. I once analyzed a Class B office lease that looked favorable on paper. The tenant was paying triple net with no cap on CAM reconciliations. The landlord's operating expense pass-throughs came in 22 percent above budget in year three because of a rooftop HVAC replacement that was never disclosed during negotiation. The lease didn't require landlord notification of capital expenditures exceeding a threshold. That gap cost the tenant roughly $18,000 more than the comparable property down the street with a $50,000 annual CAM cap.
The Practical Workflow for Building Your Commercial Lease Analysis Template
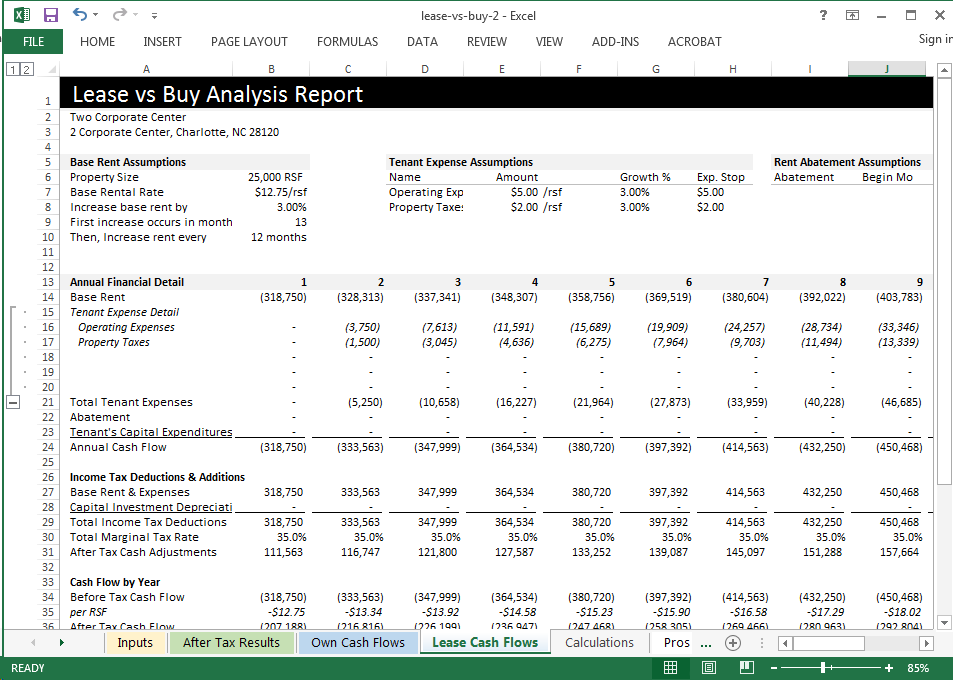
Start by pulling the full lease package. That means the main agreement, all amendments, estoppel certificates already executed, and any subordination agreements. People routinely forget the amendments and work off the original document, which means the base rent, term length, and renewal options are all wrong from the start. Once you have the complete set, create a clause index. This is not optional. Go through every page and tag each paragraph with a brief description of what it covers. I use a simple numbering system: R for rent provisions, O for operating expenses, T for term and timing, A for amendments and alterations, and M for maintenance responsibilities. This index becomes your map when you hit a conflict between clauses, which happens far more often than people expect. After the index, extract the financial data into structured rows. Each row should represent one distinct financial obligation or benefit. Columns should include the clause reference, the dollar amount, the frequency, the escalation mechanism, and any caps or limitations. Here is where most templates fail. They create one row labeled "Base Rent" and put a single number in it. If the rent escalates annually by 3 percent with a five-year step-up to 8 percent after year five, that single row is useless. You need at least two rows covering different periods, and preferably one row per escalation step so you can model cash flow accurately.
Get the Full Details

The next step is calculating the effective rent. This is the most misunderstood metric in commercial leasing and the one most people get wrong in their templates. Effective rent is not average rent divided by months. It accounts for free rent periods, tenant improvement allowances, escalation timing, and the time value of money when you discount future payments. A lease offering three months of free rent on a twenty-four month term does not have rent that is simply 12.5 percent lower. The savings come at the beginning of the term, and the remaining payments carry the full base amount. Discounting these cash flows changes the effective rate enough to matter on a ten-year lease. I built a template that handled this properly for an industrial warehouse deal. The landlord offered six months of abatement on a twelve-month initial term with annual 4 percent escalations. A naive calculator would spread the abatement evenly across the term and show a flat discount. My template ran each payment period individually, applied the abatement only to the months it covered, and escalated the remaining payments according to the schedule in the lease. The difference between the two methods was $11,200 in present value over the life of the lease. That is the kind of gap that shows up as a deal killer in negotiations if you catch it early.
Using a Commercial Lease Analysis Template for Side-by-Side Comparisons
Once you have one lease modeled correctly, the template becomes valuable for comparing multiple properties or terms. You can layer in different scenarios: keeping the same base rent but negotiating a higher CAM cap, trading a longer free rent period for a lower escalation rate, or accepting a shorter renewal window in exchange for atenant improvement contribution. The comparison grid should show net cost per square foot, total occupancy cost over the expected hold period, and the net effective rate after all concessions and escalations. Add a column for risk factors, which is where you note things like uncapped operating expenses, missing co-tenancy provisions, or ambiguous renewal notice deadlines. Those items do not have dollar values attached easily, but they carry real cost if triggered. One thing I learned the hard way: leases often contain cross-default clauses between spaces in the same building. If a tenant occupies two units and one lease defaults, the other lease can be terminated by the landlord. Most standard templates do not account for this. I started adding a separate section for portfolio-level risks after a client lost access to their second location because a financing issue on the first triggered a default under a cross-default provision they had never noticed. The clause was in section 14.3, buried between subsections about assignment restrictions.
Where These Templates Break Down
They break when the lease is unusually structured. Standard templates handle sequential escalations, percentage rent, and basic operating expense pass-throughs fine. They do not handle revenue-sharing arrangements, percentage rent with breakpoints, phased occupancy, or leases tied to consumer price index adjustments with caps and floors. If you encounter a lease with a CPI-based rent escalation clause, you need to manually model each adjustment based on historical index values and the specific formula in the lease. No generic template will do this automatically. Another limitation is that templates assume the lease text is the final word. In practice, verbal agreements made during negotiation sometimes contradict the written document. Verbal modifications are not enforceable in most jurisdictions, but they create real expectations. Tenants have walked into buildings expecting concessions that were never written into the lease because the landlord's legal team removed the language before execution. Your template can note these discrepancies, but it cannot resolve them. That requires going back to the negotiation documentation or getting a formal amendment. The biggest bottleneck is data entry accuracy. A template is only as good as the information fed into it. I have seen analyst errors where the renewal option date was entered one month early, causing the model to suggest extending occupancy by an extra year in a rising market. In another case, a $2 per square foot per year escalation was entered as a one-time increase instead of recurring annually. That error understated total occupancy cost by approximately $34,000 over a ten-year term on a 5,000 square foot space. Manual verification against the lease text is non-negotiable. There is no shortcut that replaces reading the actual document.
What to Look for Beyond the Numbers
A complete analysis goes beyond cash flow. The non-financial provisions often determine whether a lease is functional or a liability. Examine the relocation clause. If the landlord can move your tenant to a different space in the same building, that can destroy foot traffic for a retail operation even if the new space is physically identical. Check the assignment and subletting terms. A lease that prohibits all subletting without landlord consent, and gives the landlord unilateral discretion to approve or deny, can trap you if your business needs downsize or restructure. The quiet enjoyment clause matters more than people assume. A weak version lets the landlord enter the premises for inspections or repairs at any time with minimal notice. A strong version requires reasonable notice except in emergencies and restricts entry to business hours. For a medical office tenant, constant interruptions during patient hours are not an inconvenience. They are a revenue problem. Insurance requirements are another area where small wording changes create large cost differences. A lease that requires the tenant to maintain general liability at $2 million per occurrence versus $1 million per occurrence and $2 million aggregate can double your insurance premium. Some leases require the tenant to name the landlord as an additional insured on every policy. Others only require it on the general liability policy. The difference in administrative burden and cost is measurable, and it varies significantly between lease documents from different landlords.
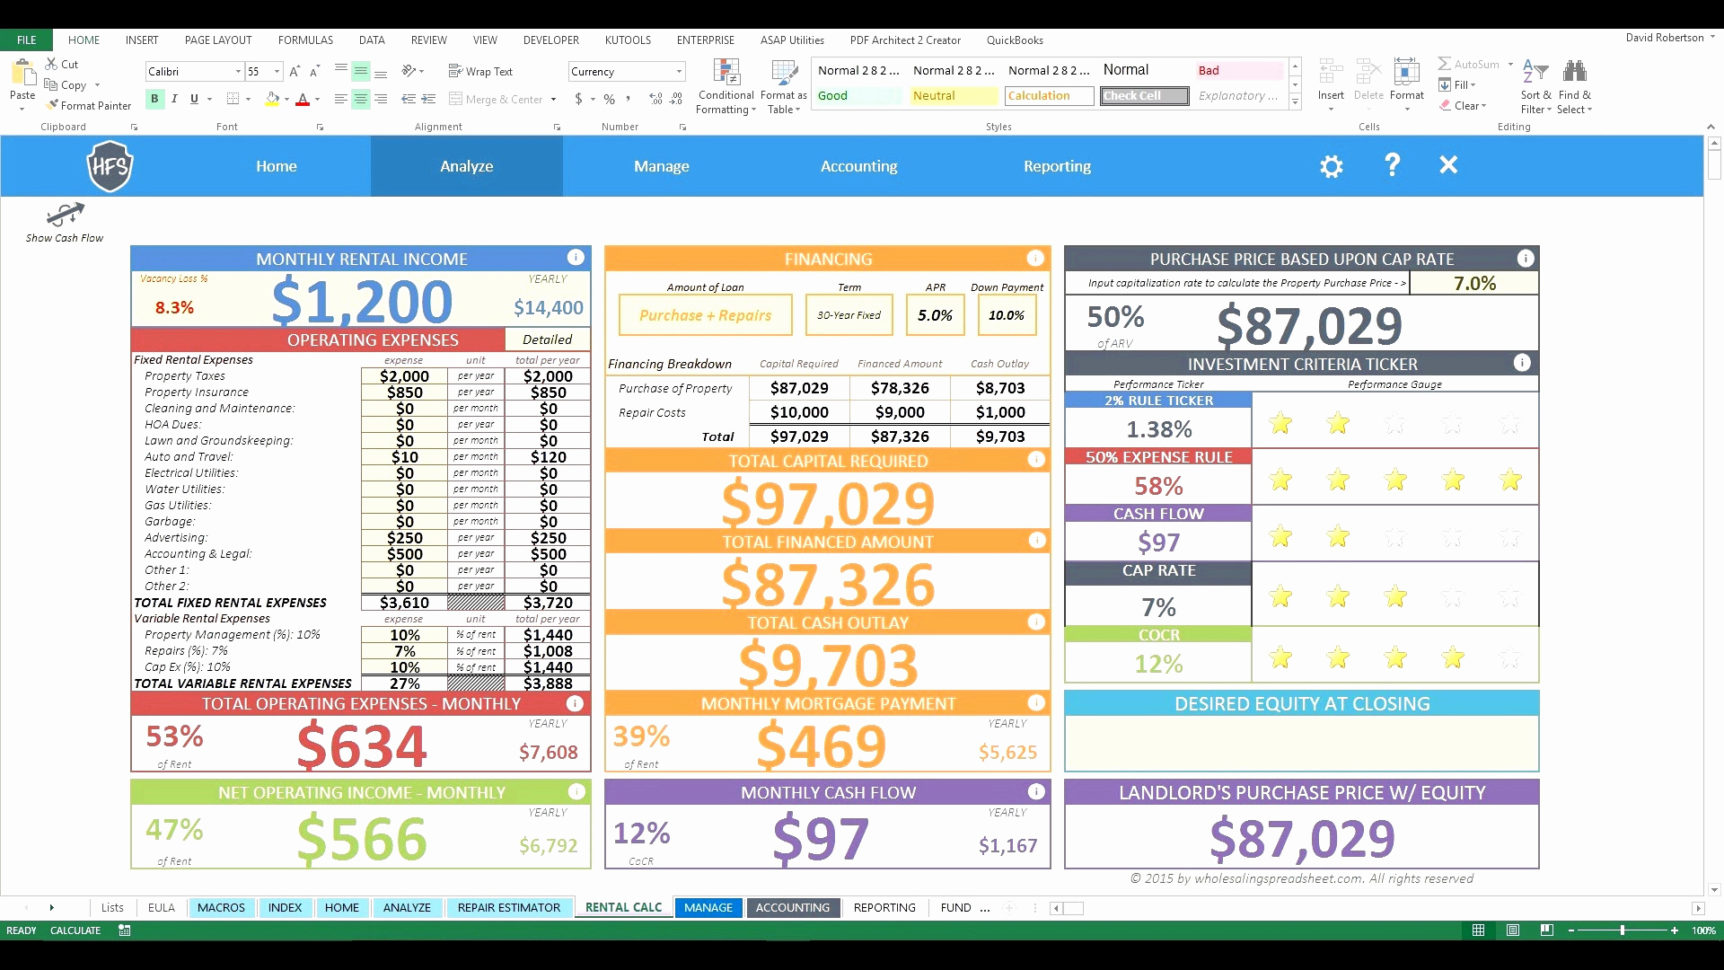
If you want a starting point for organizing this analysis, you can download a working Commercial Lease Analysis Template that covers the cash flow modeling, clause extraction, comparison grid, and risk notation sections I described. It is built for direct input from lease documents and includes notes on common problem areas flagged throughout this guide.