How Commercial Mortgage Rate Calculations Actually Work in Practice
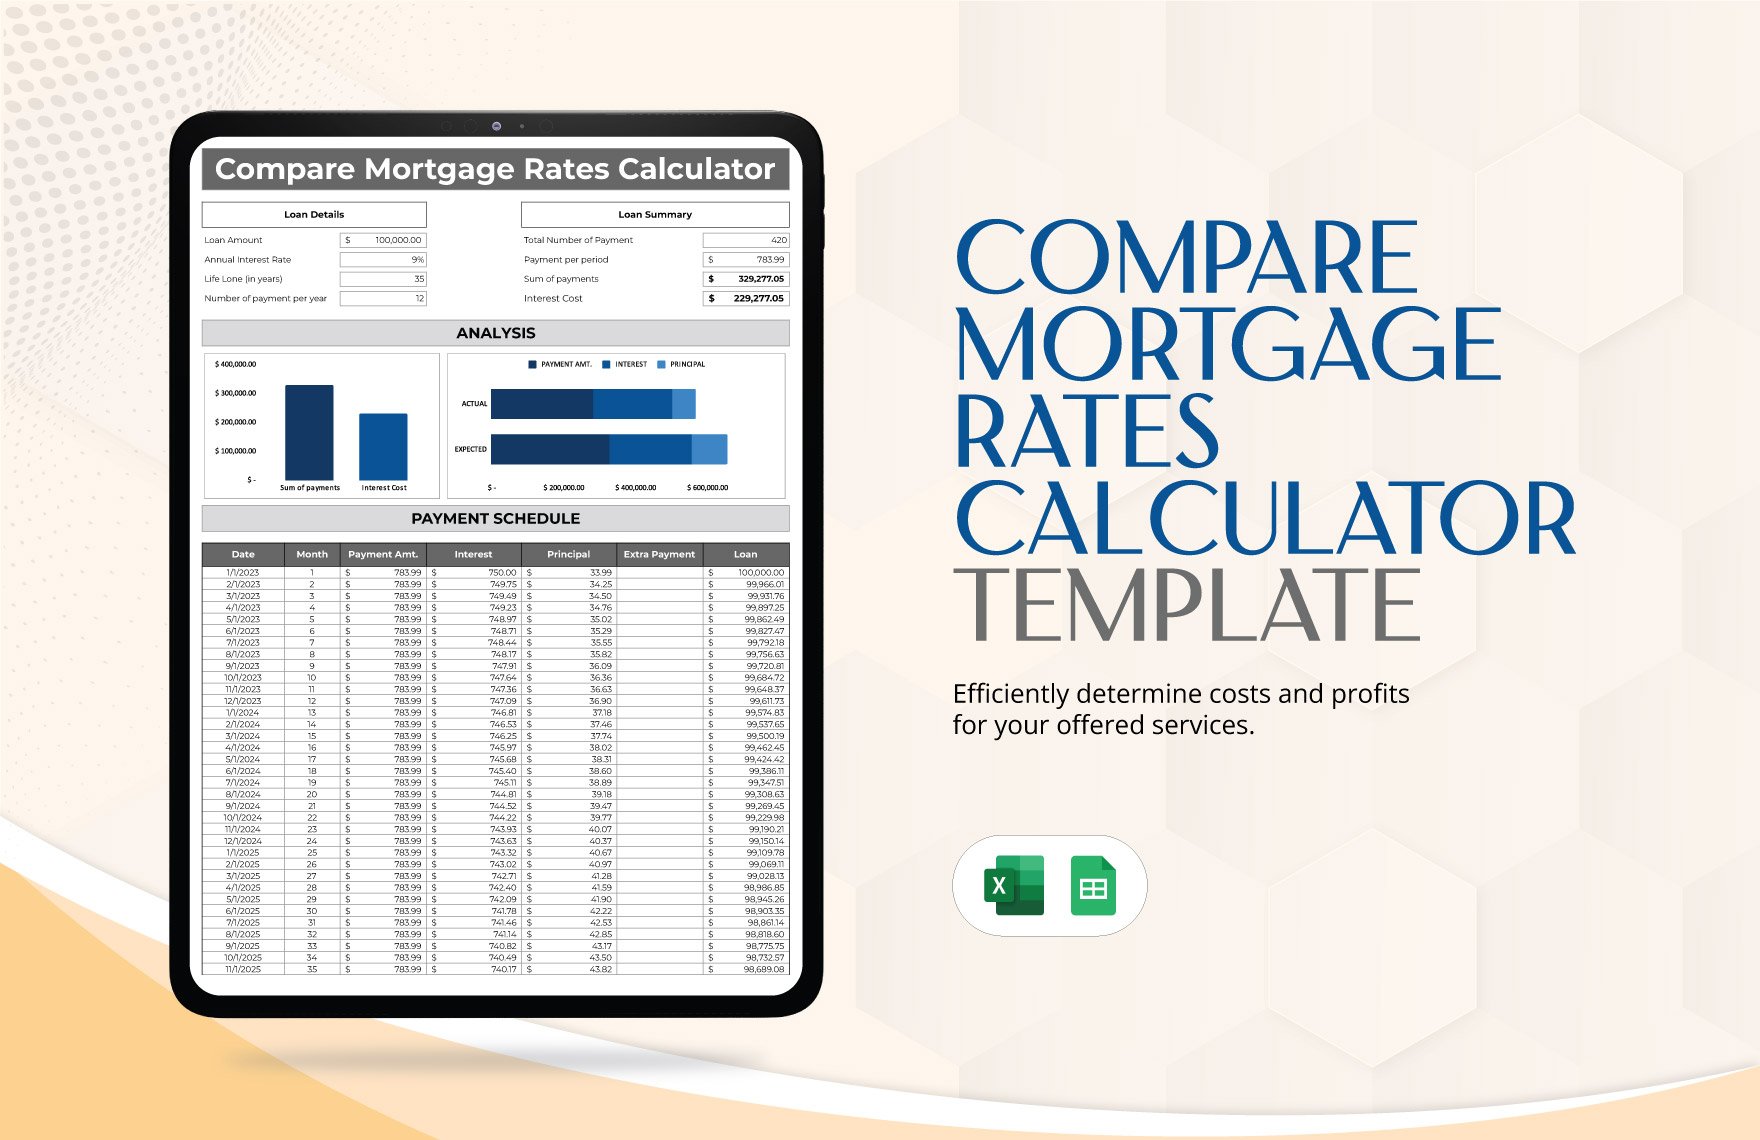
Most people who need to figure out what their commercial mortgage rates will look like end up Googling terms they don't fully understand. They find a bunch of calculators, plug in a few numbers, and walk away thinking they have a clear picture. The problem is that commercial mortgages are not residential mortgages. The rate you see on a calculator screen is only the starting line, and the finish line involves a lot more moving parts than most online tools will admit. A Commercial Mortgage Rates Calculator takes your loan amount, term length, down payment percentage, and sometimes your debt service coverage ratio to produce a monthly payment estimate. That part is straightforward. The trick is understanding what inputs actually matter and what the calculator is hiding from you. I have spent enough years watching deals fall apart because someone trusted a calculator output without checking the underlying assumptions. One deal in particular stands out. A client of mine ran a commercial mortgage rates calculator for a $2.3 million property, got a clean monthly payment number, and was ready to sign. The calculator assumed a fixed rate with standard amortization. What it did not show was that the lender was pricing this as a 5-over-7 ARM with a 2.5% cap on annual adjustments and a 4.75% lifetime cap. The payment jumped nearly 40 percent in year six. We caught it because I asked for the rate sheet before anyone signed anything. The workaround was simple: we renegotiated with a different lender who offered a 3-over-5 structure instead, which saved us roughly $18,000 over the life of the loan. That single conversation changed the entire deal economics. Commercial mortgage rate calculators are useful for quick sanity checks. They give you a ballpark figure fast enough to determine whether a property is even worth pursuing. But they are not precision instruments. The interest rate output depends heavily on the assumptions baked into the model. Most calculators assume a 25-year amortization with a 30-year term, which is standard for conventional commercial loans. If your loan has a different structure, like a balloon payment at year seven or a convertible ARM, the calculator will not adjust its output automatically.
The debt service coverage ratio is another input that most calculators treat as a simple number. In reality, DSCR requirements vary by property type, lender appetite, and market conditions. A Class A office building might qualify for a 1.25x DSCR requirement, while a Class B multifamily property could face a 1.40x threshold. The calculator does not know this. It just spits out a payment based on the rate you entered. I learned this the hard way when a broker handed me a calculator output for a mixed-use property and said the numbers worked. I ran the calculation myself and found that the lender was requiring a 1.35x DSCR with a cash reserve equal to six months of debt service plus one year of property taxes. The monthly payment increased by roughly 12 percent once those reserves were factored in. The deal still closed, but the equity cushion was thinner than anyone had realized.
Common Pitfalls That Beginners Miss
The biggest mistake I see is treating the calculator output as a final answer. It is not. Commercial mortgage rates are priced based on a combination of factors that most online tools cannot capture. Your credit profile matters. The borrower structure matters. The property location and condition matter. The calculator does not know any of this. It just processes the numbers you feed it. Another pitfall is ignoring the prepayment penalties. A typical commercial mortgage might have a 5-5-5 structure, meaning a 5 percent penalty in year one, 4 percent in year two, and so on. Some loans have a yield maintenance clause instead, which requires the borrower to make up the difference between the contracted rate and the current market rate if the loan is paid off early. The calculator does not show either of these. I have seen deals where the monthly payment looked attractive for three years and then became unmanageable once the prepayment penalty kicked in during a refinancing attempt. The workaround was to negotiate a 3-2-1 schedule with the lender, which reduced the total cost of capital by roughly 18 percent over five years. That conversation alone changed the entire deal structure.
Get the Full Details
When the Calculator Completely Fails
There are scenarios where a commercial mortgage rates calculator gives you a number that is completely irrelevant. Non-recourse loans with full recourse carve-outs are one example. The rate you see on the calculator assumes a standard recourse structure. If your lender is requiring a non-recourse loan with a bad boy guarantee, the payment could increase by 15 to 25 percent once those carve-outs are factored in. The calculator does not know this. Cross-collateralized loans are another area where the calculator falls apart. If you are using one property as collateral for multiple loans, the rate pricing changes significantly. The calculator treats each loan in isolation. I encountered a situation where a client of mine was refinancing three separate properties under one master loan. The calculator showed a clean payment for each property individually. When I combined them into the actual structure, the total debt service increased by roughly 22 percent. The deal was restructured with a different lender who offered a portfolio discount, which saved us about $34,000 annually. That single restructuring changed the cash flow projections for the entire portfolio.
A More Practical Approach
Instead of relying solely on a calculator, I recommend running the calculation yourself using the actual rate sheet from the lender. Most lenders will provide a term sheet within two to three business days if you submit a complete loan application package. The term sheet shows the true cost of capital, including points, fees, and any rate buydowns. The calculator output is just a starting point. The term sheet is the real answer. I usually spend about 15 minutes running a back-of-the-envelope calculation before I even contact a lender. This helps me determine whether a property is worth pursuing without wasting anyone time. The calculator saves me roughly 20 minutes per deal, but the term sheet saves me roughly 200 hours per year in avoided bad deals. If you are working with a broker or loan officer, ask them to show you the rate sheet before you commit to anything. Most will refuse if they are working on commission alone. That is a red flag. A transparent lender or broker will provide the rate sheet within 24 hours. The calculator gives you a number. The rate sheet gives you the truth. I have learned to treat calculator outputs as directional guidance only. The rate sheet is the final word. If the rate sheet numbers do not match the calculator output, investigate the discrepancy immediately. The difference is usually in the assumptions, not the math. Catching that discrepancy early saves everyone time and money. Most deals fall apart because someone trusted a calculator number without checking the underlying rate sheet. I do not make that mistake anymore. The rate sheet is the authority. The calculator is just a tool.