Why Most Commercial Property Calculators Give You Bad Numbers
I've spent enough time building spreadsheets and reviewing brokerage proposals to know that the average commercial property calculator is mostly decorative. They look clean. They spit out a cap rate and a cash-on-cash return. And then someone signs a lease or buys a building based on numbers that are off by 12 to 18 percent because the model assumed everything would go exactly as planned.
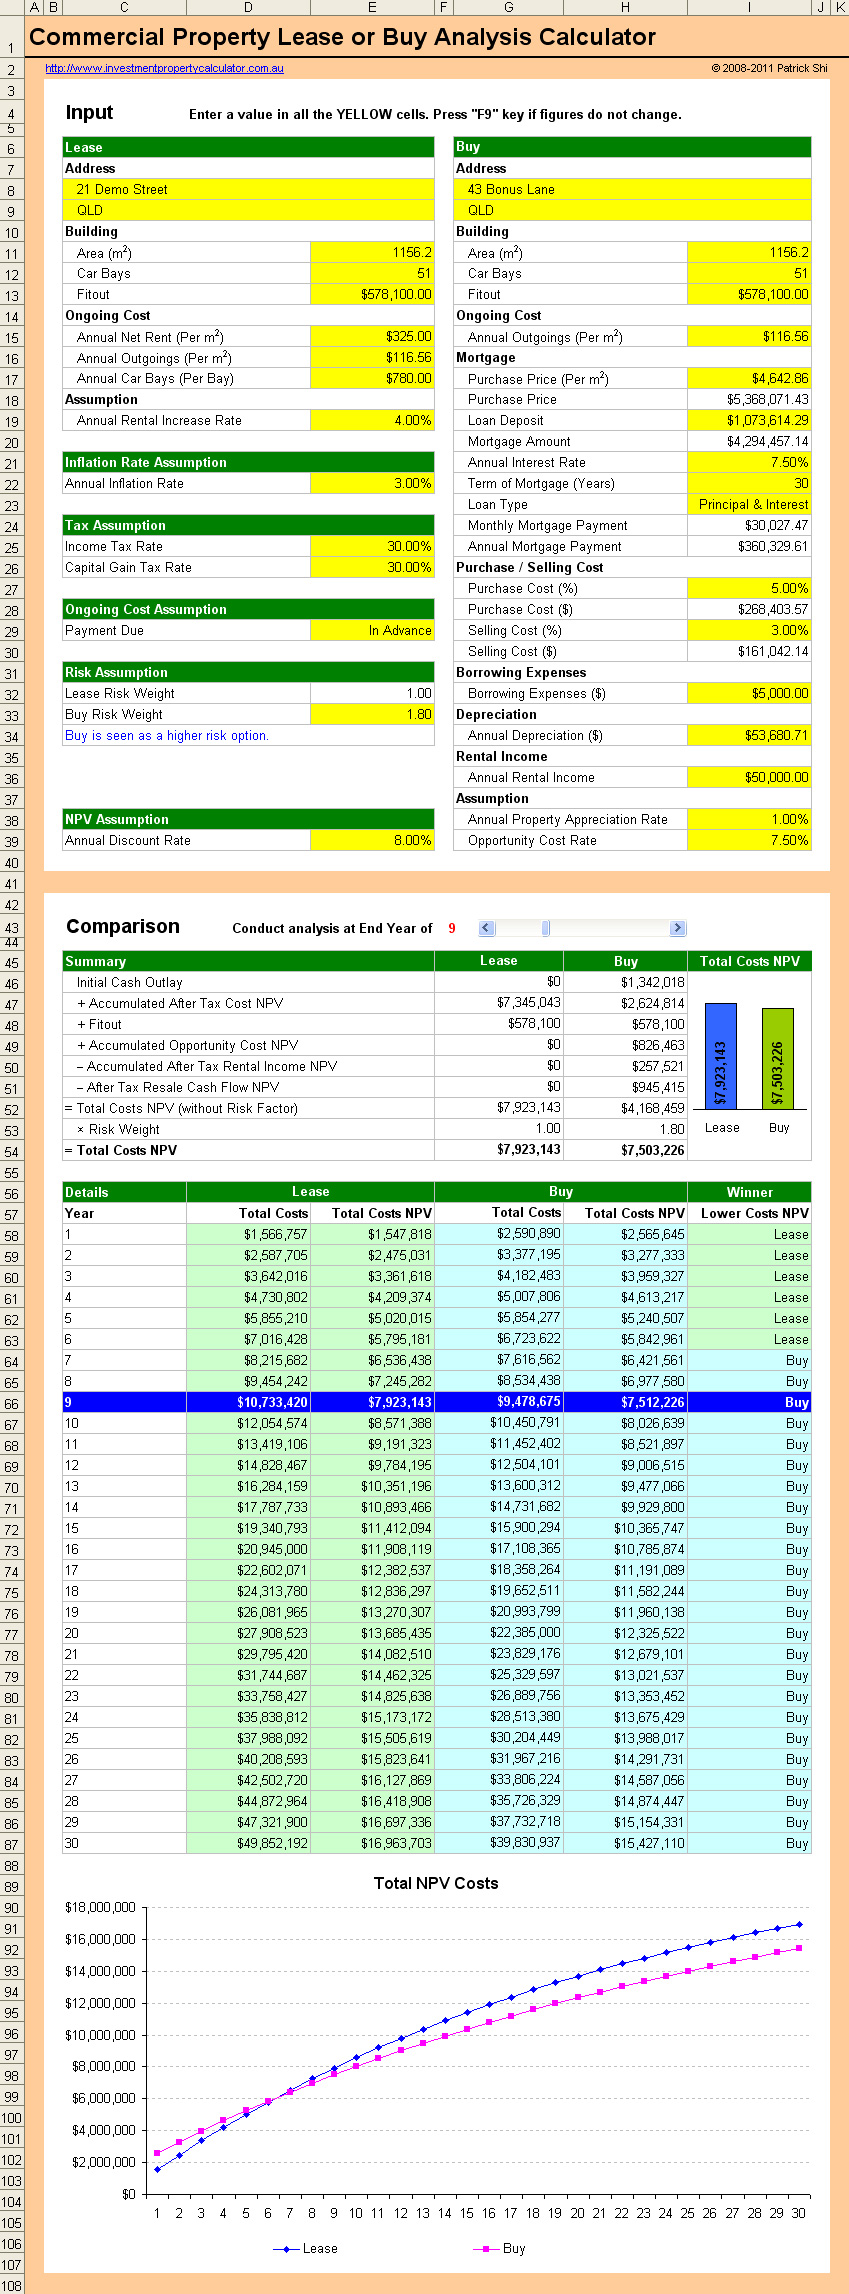
A Commercial Property Calculator is really just a structured way of organizing revenue assumptions, operating expense inputs, financing terms, and exit scenarios into projected returns. That's it. The value isn't in the output numbers themselves. It's in making sure every input is grounded in actual market data rather than optimistic guesswork.
How to Actually Build One That Works
Start with a blank sheet. Pick your property type first because the line items change completely depending on whether you're looking at multifamily, retail, office, or industrial. A triple net lease model for a single-tenant industrial building has maybe four expense line items. A five-story Class B office in Minneapolis has thirty-two.
The revenue section needs a vacancy schedule, not just a static number. Put in a year-by-year ramp if the building isn't fully stabilized. I worked on a regional shopping center deal where the seller reported 82 percent occupied and the calc came back with a decent NOI. We dug into the leases and realized two anchor tenants had nine months left before renewal, and the rest of the tenant mix was mostly short-term pop-up shops. The actual stabilized vacancy was closer to 41 percent. Using that instead of the reported number cut the projected yield from 9.4 percent down to 6.1 percent. The deal fell apart immediately once we ran the realistic version.
For operating expenses, use actual property-level data whenever it exists. If you don't have it, pull from CoStar or local commercial brokers, not Zillow or LoopNet. Those consumer-facing sites inflate expenses because they include capitalized improvements and one-time costs.
Here's something most people miss when they're building their first commercial calc: the difference between NNN and gross leases completely changes how you model expenses, and most templates don't account for this properly. In a triple net lease, the tenant pays property taxes, insurance, and maintenance on top of rent. Your calculator should have a toggle that switches the entire expense structure rather than just manually deleting line items. I built a tool for a client that let us flip between NNN and gross within the same model, and it took about three hours to code that switching logic. We saved maybe forty hours per quarter after that.
Financing is where the big errors happen. People plug in the interest rate from today's market and call it a day. You need to build in a rate lock period assumption and a refinancing scenario for years three through five. The spread between the acquisition rate and the refi rate can swing your equity multiple by two points, sometimes more.
The Edge Case That Almost Cost Us a Five Million Dollar Mistake
We were evaluating a small multiplex in Tulsa and the calculator showed a strong return. Everything looked fine until I noticed the property tax line was pulling from a 2019 assessment. The county had reassessed the entire neighborhood after a new highway interchange opened nearby, pushing the tax basis up by 34 percent. The calc was using the old basis because the seller hadn't updated the financials.
The fix was simple. We pulled the current taxable value from the county assessor's website and replaced the line item. The cash flow dropped enough that we adjusted our offer by almost $120,000. The seller thought we were being greedy until we showed the assessment records. They accepted the lower price.
This happens constantly. A lot of calculators don't flag when your expense inputs are stale. You have to build that check into the model yourself or catch it manually.
What These Calculators Get Wrong Every Time
Commercial Property Calculator tools tend to underestimate stabilization timelines. They assume year one occupancy equals year two occupancy equals year three. Real markets don't work that way. Vacancy drifts, tenants leave without notice, and rent rolls are lumpy. Model a realistic occupancy ramp even if it means your early years look less attractive. The late years will still be stronger because you're compounding on a higher base.
Another common flaw is ignoring tenant improvement allowances and leasing commissions. A standard retail lease might budget six months of free rent plus a $15 per square foot TI allowance. That's a real cost that comes out of your income in the first year or two. Most basic calculators don't have a line item for it, so the numbers look better than they actually are. Put it in. Factor it into your hold period analysis.
Insurance costs are another moving target that most models treat as static. Commercial property insurance premiums have increased significantly since 2021, especially in states like Florida and Texas where climate risk has reshaped the market. Budgeting the 2019 premium rate in 2025 is a fast way to overstate your net operating income.
A Practical Workflow That Saves Time
Build your master template once. Keep the core structure stable. When you get a new property, copy the template, rename it, and fill in the actual numbers. Don't rebuild from scratch every time. I have a standard set of tabs: assumptions, rent roll, operating expenses, financing, projections, and sensitivity analysis. The whole thing takes about twenty minutes to set up for a standard commercial property if I already have the lease data in front of me.
The sensitivity tab is worth the extra effort. Run your base case, then shift vacancy by plus and minus five percent, shift operating expenses by ten percent, and shift the exit cap rate by fifty basis points. Four scenarios. It takes about eight minutes to set up and tells you which assumption is driving your return the most. Usually it's the exit cap rate or the vacancy assumption. Knowing that helps you focus your due diligence.
I also recommend exporting your final numbers to a PDF with the assumption sheet included. When you're presenting to investors or lenders, they'll ask where each number came from. Having the assumptions documented with your sources saves you from scrambling later.
When to Use an Alternative Approach
If you're analyzing a large institutional-grade asset with over two hundred units or a portfolio of mixed-use properties, a spreadsheet calculator starts to show its limits. The data volume gets unwieldy and the chance of a formula error increases. At that scale, dedicated proptech platforms like Yardi Voyager or Buildium make more sense. They have built-in compliance checks and can pull actual rent roll data from your management software.
For a standalone single-tenant NNN deal under a million in value, a well-built spreadsheet is faster and more transparent. You control every assumption. There's no black box hiding your inputs.
The bottom line is that a Commercial Property Calculator is only as good as the data you feed it. The math itself is straightforward algebra. The hard part is knowing what numbers to trust and having the discipline to run sensitivity scenarios instead of celebrating a pretty base case.
Gallery Commercial Property Calculator
Commercial Lease Calculator Lease Vs Buy Commercial Property
Commercial Property ROI Calculator
Commercial Property Value Calculator Australia at Angela Bates blog
Commercial Property Rent Calculator
Commercial Property Insurance Calculator - 4MeNearMe.com