Why most people run the wrong numbers in a Commercial Real Estate Calculator
I spent four years working on underwriting for small multifamily deals before I figured out that the spreadsheet calculators everyone uses are actually kind of broken. Not useless, but broken in ways that cost real people money if they don't know what they're doing. The problem isn't the calculator itself. It's that most templates are built by people who've never had a real tenant vacate mid-year and leave a unit empty for 90 days while you figure out whether to repaint or just replace the carpet. Here's what happens when you feed optimistic numbers into a Commercial Real Estate Calculator: you get a clean internal rate of return that looks great until actual rent rolls come in six months later and you realize you're underwater. I saw this exact thing happen to a client of mine last fall. We were looking at a four-plex in Columbus, Ohio. The asking price was $680,000 with listed rents totaling $3,800 per month. The seller's rent roll showed zero vacancies. The calculator spit out a 14.2% cash-on-cash return. That was before you even factored in the usual five to eight percent vacancy rate on a market with 7.3% available units. After running the same deal with realistic vacancy, deferred maintenance reserves, and a proper CapEx schedule, we were looking at negative cash flow in year two. We walked away. The deal still looked fine on paper to the seller because they were using a template without understanding the inputs.
How to actually use a Commercial Real Estate Calculator
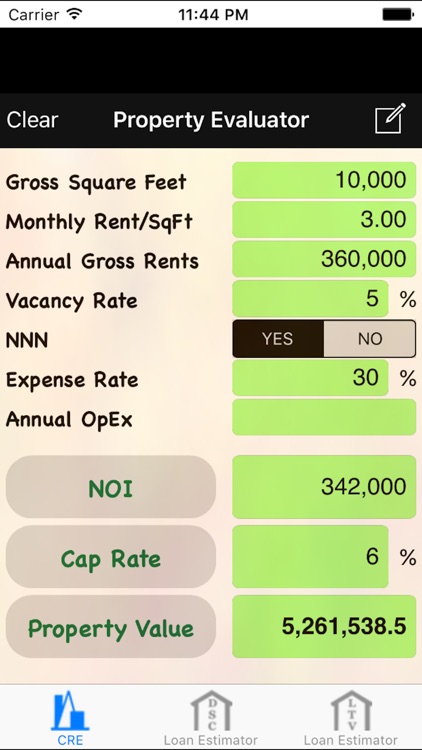
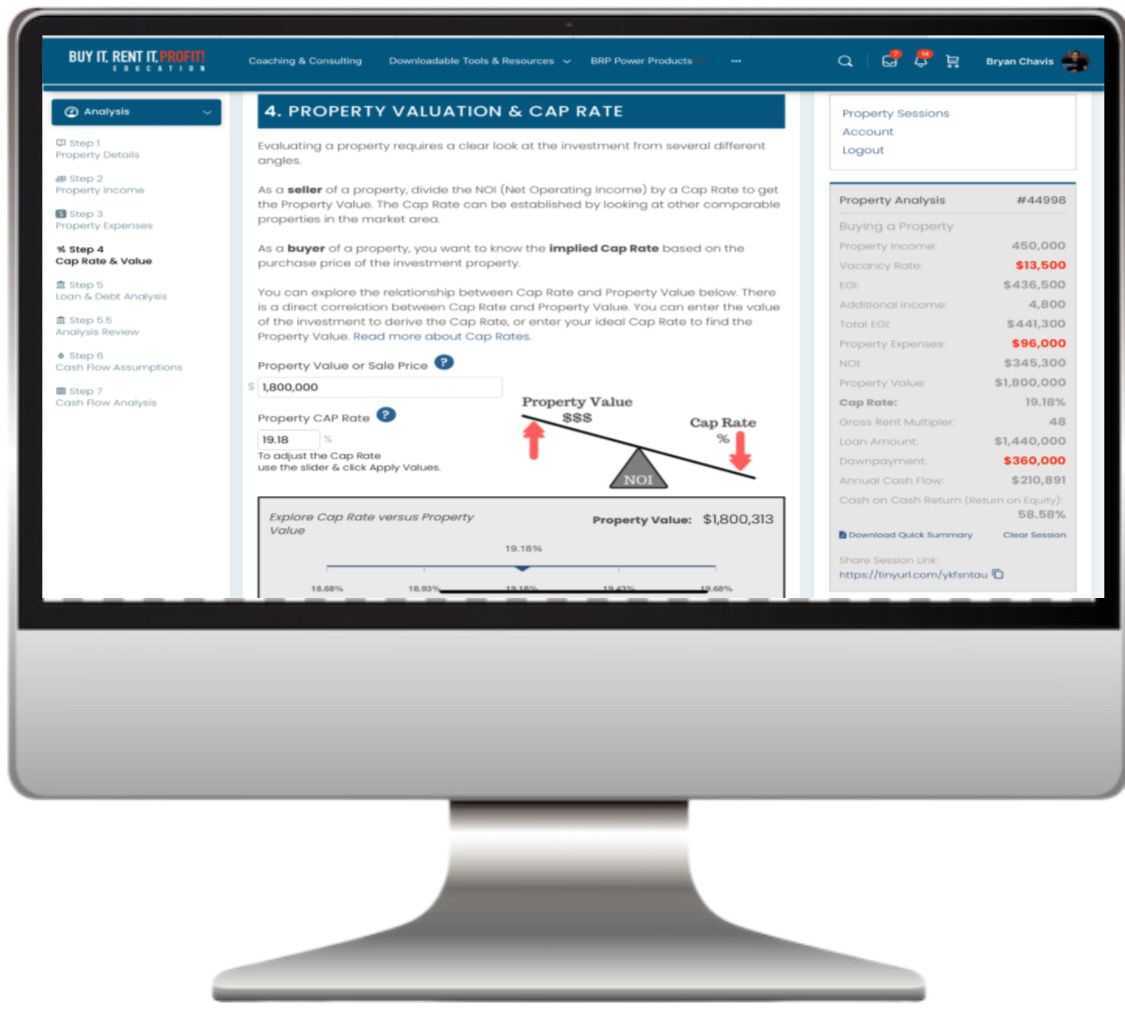
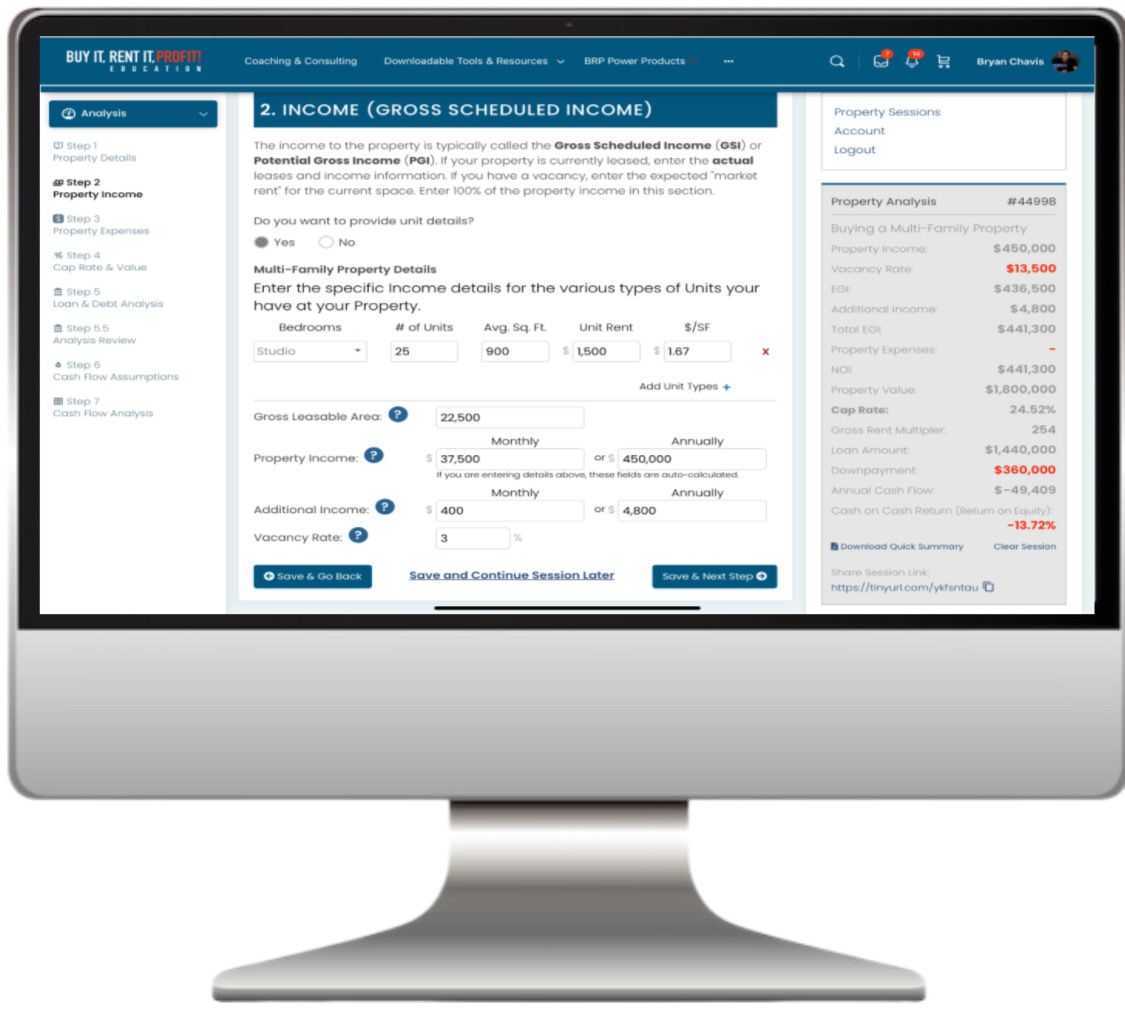
Start with gross scheduled income, not whatever the listing says the property is making. Gross scheduled income is the total rent if every unit were occupied at full market rate. From there you subtract vacancy and credit loss. I use six percent for multifamily in most markets unless there's something special about the asset or the location. For net lease retail, you might go lower if you have a long-term tenant with a solid credit rating, but for anything triple-net with a single tenant, you need to evaluate the tenant's financials separately rather than just assuming the income is guaranteed. Next, you add other income. Parking fees, laundry, storage units, pet rent. This is usually ten to fifteen percent of total income but it's rarely included in basic calculator templates. Then you get to operating expenses and this is where most people mess up. Property management is typically five to eight percent of gross income if you're self-managing, or eight to twelve percent if you hire a property manager. Insurance for a small multifamily in a midwestern market runs about $2,500 to $4,000 annually depending on coverage. Property taxes vary wildly by municipality. You need to look up the actual tax bill for the property, not guess. Repairs and maintenance is usually three to five percent of gross income. Utilities depend on whether they're owner-paid or tenant-paid. If you're the owner paying water and trash, budget accordingly. Net Operating Income is gross income minus operating expenses. It does not include debt service. This is the number that matters for valuation. Price divided by NOI gives you the cap rate, which tells you whether the deal is priced right relative to the market. If the area is trading at five percent cap and this deal comes in at seven percent, something is probably wrong with it or it has a temporary anomaly driving the number up.
For cash flow analysis after you have NOI, you subtract debt service. That means your monthly mortgage payment based on the loan amount, interest rate, and term. The difference between NOI and debt service is your pre-tax cash flow. From there you'd factor in income taxes if you're doing a full personal return analysis, but most investors stop at cash flow because depreciation and amortization create enough complexity on their own.
Get the Full Details
The edge cases that break standard calculators
I ran into a specific problem recently with a commercial condo unit in a mixed-use building. The calculator I was using didn't account for common area maintenance charges separately from property taxes. The building had CAM fees of $4,200 annually that were listed in the disclosure documents but the calculator template treated them as part of operating expenses without highlighting them. That meant my NOI was overstated by exactly $4,200, which changed the cap rate by roughly 1.2 percentage points. For a $900,000 purchase, that difference is about $11,000 in perceived value. I ended up building a custom spreadsheet that pulled CAM, insurance, and property tax line items from the offering memorandum and compared them against the local market average for similar buildings. The CAM fees were 30 percent above the neighborhood median, which suggested the building was either over-managed or the owner was subsidizing amenities that weren't reflected in the rent. Either way, the deal wasn't going to work at the asking price with those expense ratios. Another problem I keep seeing is with 1031 exchange timelines. People use a calculator to determine whether a replacement property will generate enough income to support their new loan, but they forget that the exchange timeline means they can't shop around for the best financing terms. They lock into a rate because they're close to the 180-day deadline. A calculator can't account for that pressure. The numbers look fine on paper but the financing costs end up eating the spread. There's also the issue of rent growth assumptions. Most templates assume a flat two to three percent annual increase. That's reasonable for stabilized assets in stable markets. But in markets where rents are growing at seven or eight percent year over year, using historical data instead of the template default can dramatically change the five-year projection. I once underwrote a self-storage deal in Raleigh where the template showed a mediocre return because it assumed three percent growth, but the market was seeing six percent increases. Adjusting the assumption brought the IRR from eleven percent to seventeen percent. The deal was real. The calculator was just outdated for that market.
When the calculator fails completely
There are scenarios where no calculator will help you. Ground-up development is one. You can input construction costs, expected rents, and vacancy, but the model breaks down the moment you hit a supply chain issue or a zoning change. I worked on a project where lumber prices spiked 40 percent during construction and the original pro forma was completely irrelevant. Another is adaptive reuse, converting an office building to residential. The square footage calculations change entirely, the mechanical systems are different, and the cost per rentable foot often doubles from what you'd expect. Standard calculators don't have fields for those variables. Situational value is another blind spot. If a property has a tenant on a below-market lease that's about to expire, the current income doesn't reflect the true earning potential. A calculator will show you the present value based on existing leases. It won't tell you whether you should hold the tenant or re-lease at market. That requires market research, not a spreadsheet. Similarly, if the property is near a planned transit expansion or a major employer moving into the area, the calculator can't factor in future demand shifts. You need local knowledge for that. If you're doing a quick preliminary screen, a Commercial Real Estate Calculator is fine. It can get you from zero to a rough number in about ten minutes and help you decide whether to dig deeper. But for any deal where you're within five percent of walking away, you need to build a custom model or hand it to someone who has underwritten similar assets in that specific market. The generic tools are good for filtering, bad for final decision-making.