Setting Up a CRE Model That Doesn't Fall Apart When You Open It Six Months Later
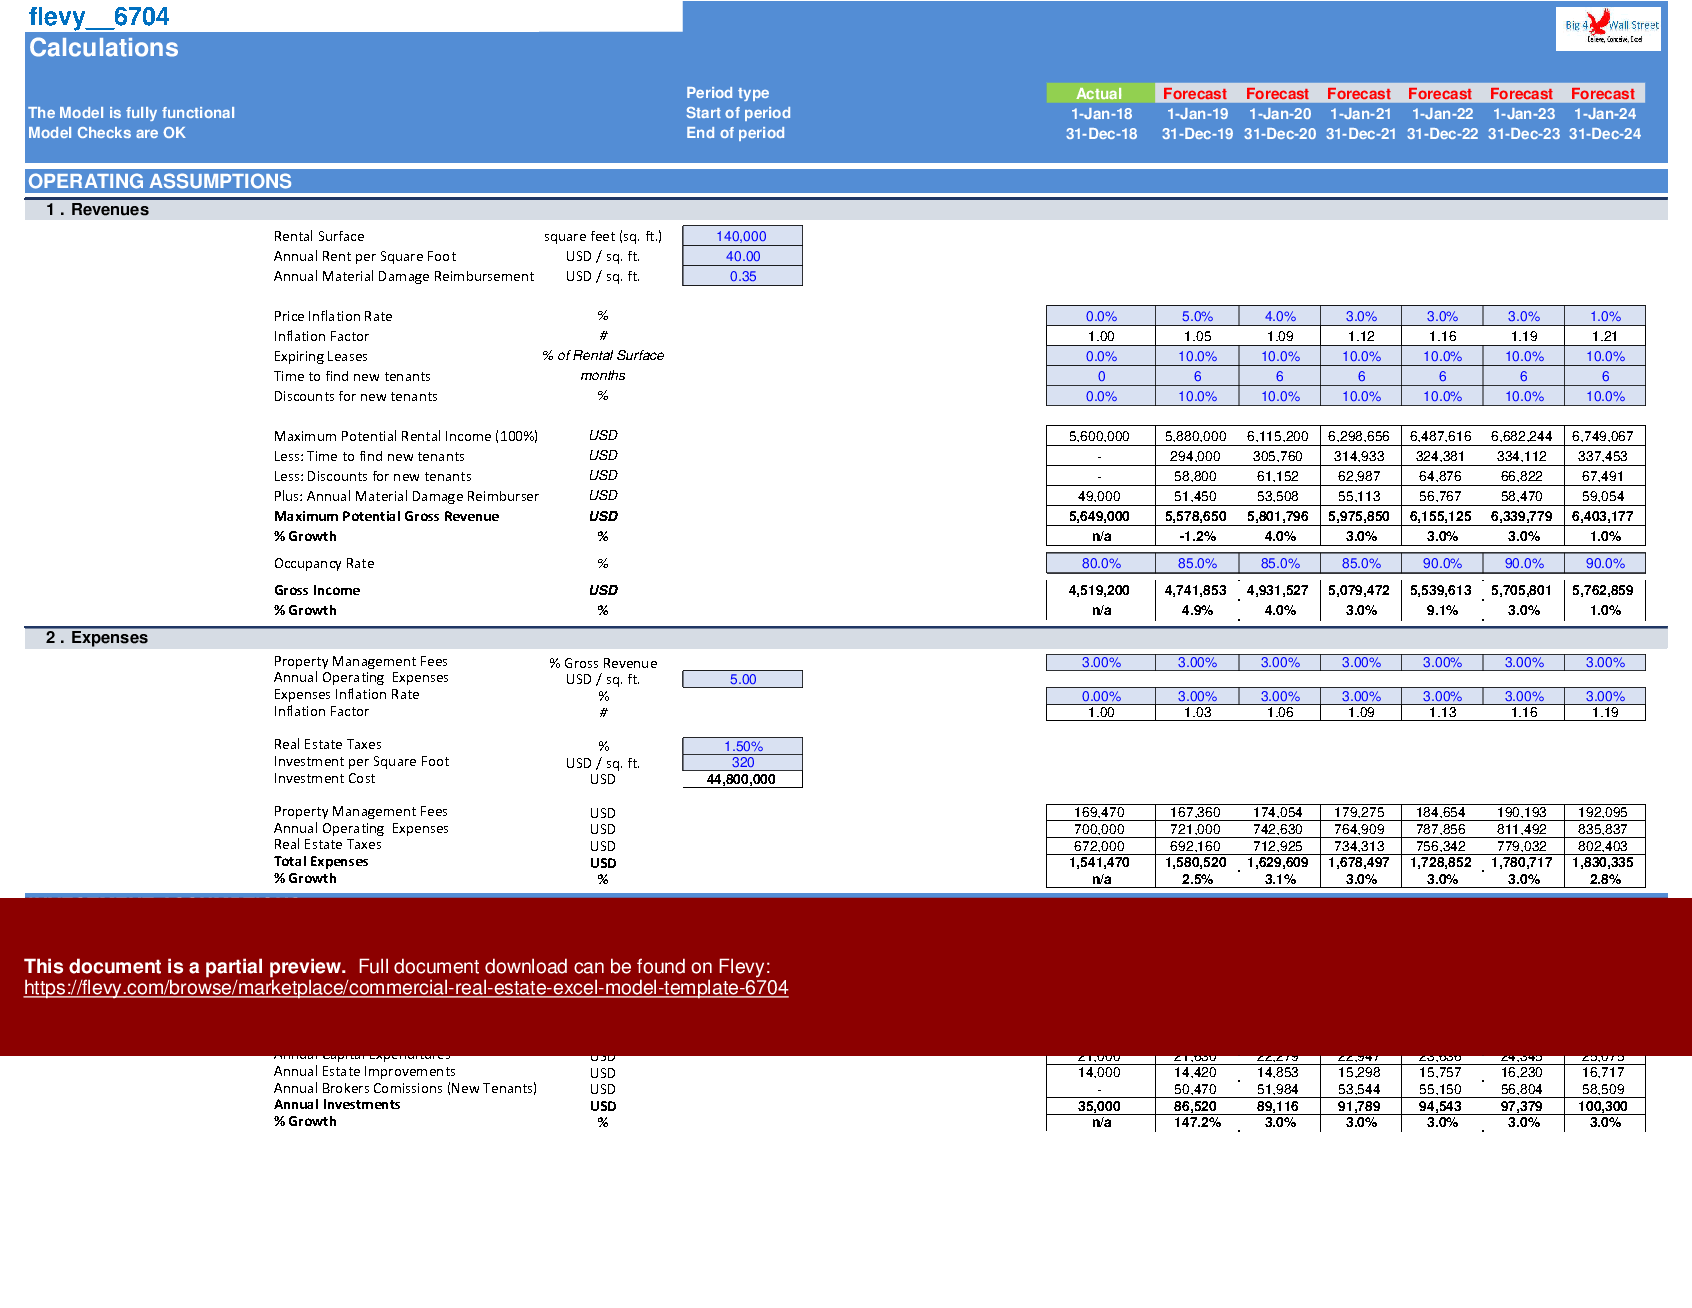
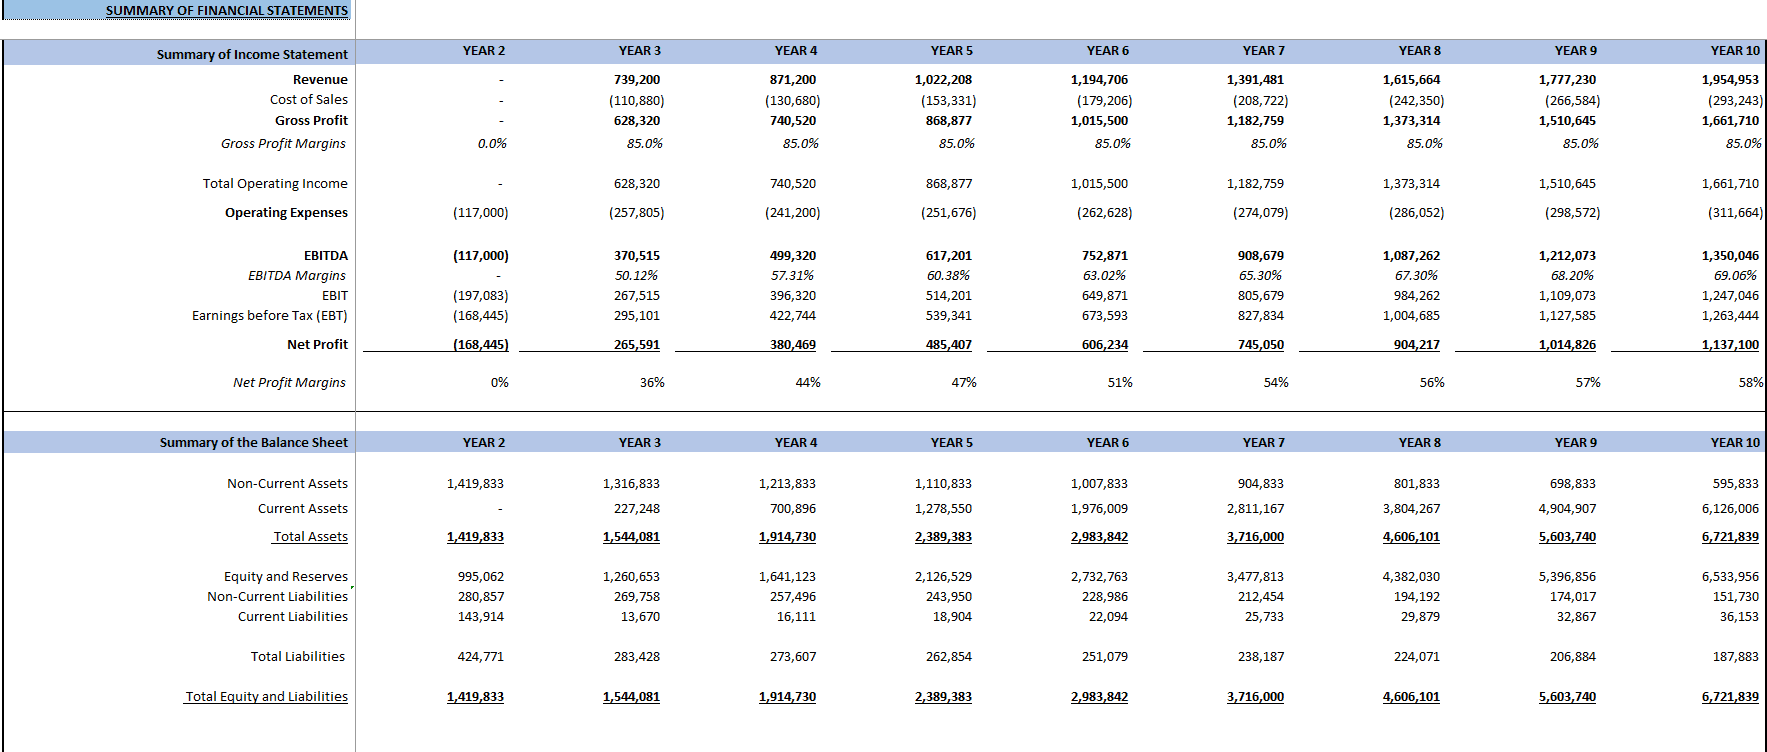
Most commercial real estate financial modeling beginners build a spreadsheet that looks correct until a single cell reference breaks during a stress test. I watched a junior analyst spend three days tracking down a $400,000 discrepancy that came from a sum() range that didn't include a newly added expense line. He had manually entered subtotals instead of using dynamic ranges, which is probably the most common mistake I see in entry-level models. The fix is straightforward: never sum more than ten cells by hand, and never assume a range won't grow. Start by defining your output before you write a single formula. In practice, you need at minimum a five-statement model linking the income statement to the balance sheet and cash flow statement, plus a schedule for each major input category. The schedules are where most models die. Depreciation schedules, amortization schedules, debt service calculations, tax impacts — these should be their own tabs with clear inputs at the top and outputs referenced by every other tab. When you change an interest rate assumption in month three, it should ripple through the entire model without requiring you to find and update ten different places.
Commercial Real Estate Financial Modeling: Building the Operating Statement
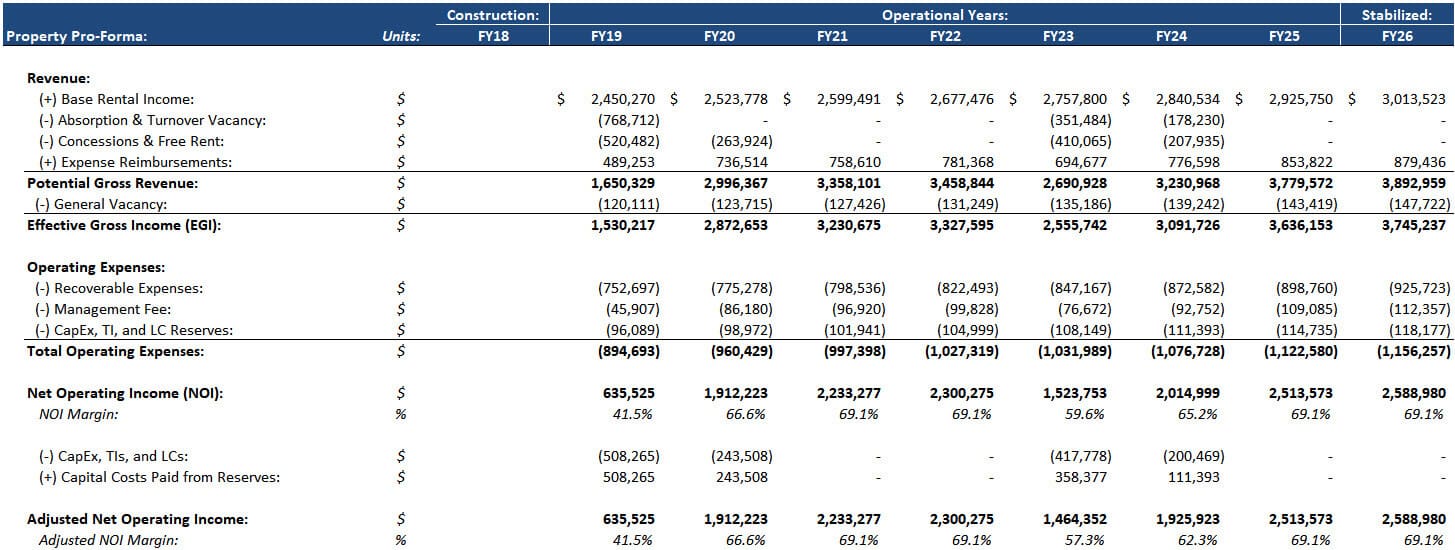
The NOI calculation is deceptively simple, but the devil is in the expense recovery structure. Most class-B multifamily and retail properties operate on some form of proportional expense recovery, which means your revenue model needs to account for tenant reimbursements separately from base rent. I modeled a 120-unit apartment complex where the landlord recovered 78% of operating expenses based on leased square footage. The mistake most people make is applying the recovery to the wrong expense categories or calculating it on gross rather than netrecoverable expenses. Your model should have a dedicated section showing what expenses are recoverable, the recovery percentage, the lease-up schedule, and then the actual dollar amount flowing into revenue. For ground rent or percent rent situations in retail, you need to model both the fixed component and the variable component separately, then combine them. A strip center with a $15 per square foot base rent and 5% of gross sales above a natural breakpoint requires a sales projection table that drives the variable portion. Don't use a flat growth rate assumption across all tenants. I learned this the hard way when I assumed 3% annual sales growth for every retailer in a portfolio and the model returned a cap rate that was off by forty basis points from market. The high-traffic anchor tenant was projected to grow at 6% while the medical office tenant should have been 2%. Specificity matters here more than speed.
Debt Schedules and Equity Waterfalls
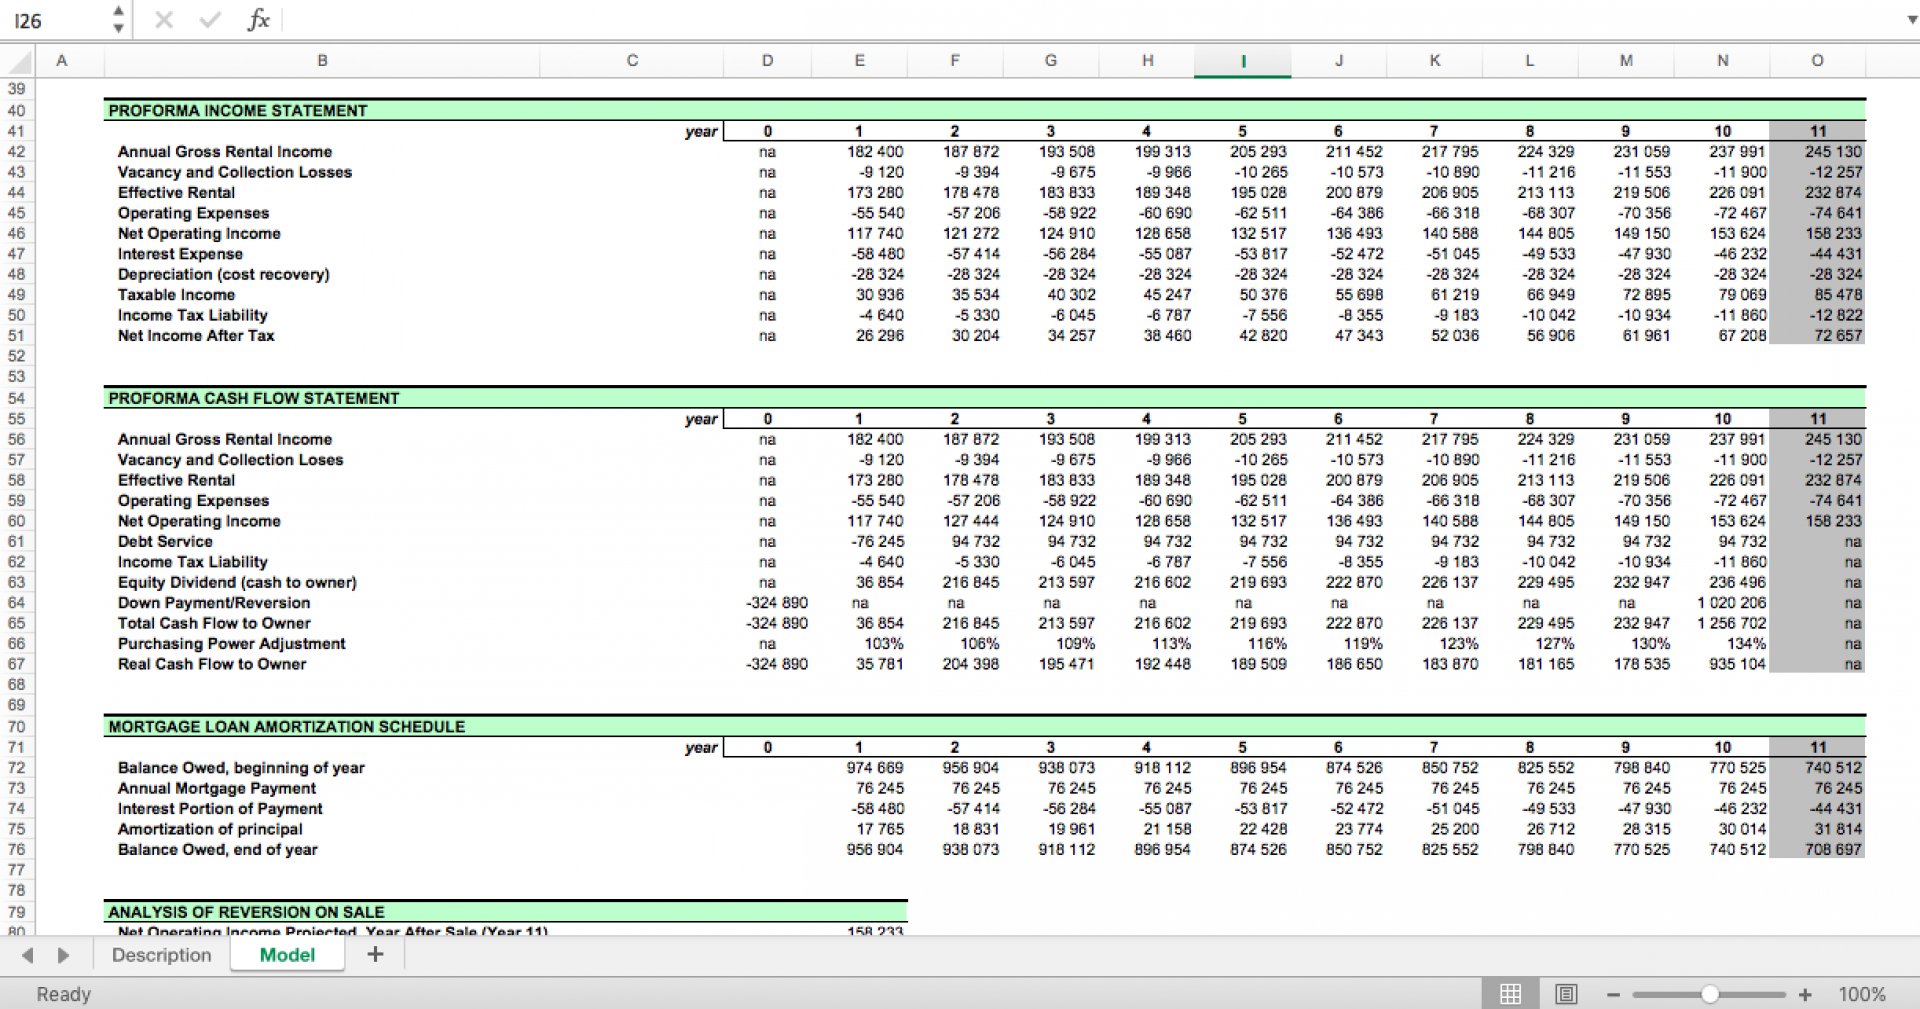
The debt schedule is where models either work beautifully or become impossible to debug. A standard amortizing commercial loan with monthly payments, a fixed or floating rate, and a balloon payment at years seven through ten needs a proper amortization table built in the model. Use the PMT function for the periodic payment, then track principal and interest separately each period. For floating rate debt, you need a separate interest rate assumption tab with reset dates and margins that update automatically. I built a model for a mixed-use development with two separate CMBS loans, one floating and one fixed, each with different amortization periods. The floating rate loan reset quarterly, and I initially forgot to align the reset dates with the model's cash flow timing. The debt service coverage ratio came out wrong by 0.15 on every quarter after a rate reset. The workaround was building a dedicated reset date lookup table that pulled the correct rate for each period based on the Treasury yield curve plus the loan margin. Equity waterfalls in multifamily and industrial deals typically follow a promoted structure with a preferred return hurdle. A standard deal might return 8% annually to equity holders until the hurdle is met, then split profits 70-30 between sponsors and investors, moving to 60-40 after a catch-up threshold. These structures get complicated fast when you add differential waterfalls by asset class, or when there are multiple equity tranches with different return preferences. The rule I follow is to model each equity tranche separately with its own cumulative return tracking, then apply the waterfall logic at the aggregate level. Building it as one massive formula produces results you can't verify. Break it into pieces: calculate total cash available, allocate to each tranche up to its hurdle, then distribute the remainder according to the promotion schedule. If the math doesn't reconcile to the total, you'll know immediately where the error lives.
Get the Full Details
Exit Assumptions and Sensitivity Analysis
The exit cap rate assumption is the single most impactful variable in any CRE model, and it's also the most likely to be wrong. I've seen models use a static 6.5% exit cap on a property that ultimately sold at 7.2% because market conditions tightened during the hold period. The difference between those two numbers changed the equity multiple from 2.1x to 1.6x, which is the difference between a returning fund and a losing one. Build your exit scenario with three assumptions: a base case, a tight case, and a wide case. Use current market comps for the base, add 50 to 100 basis points for the tight case, and subtract the same for the wide case. Don't overcomplicate this with dynamic cap rate models based on interest rate corridors unless you're modeling a portfolio at scale. For a single asset, three static scenarios are sufficient and far more transparent. Sensitivity analysis in CRE doesn't require Monte Carlo simulations. A simple data table showing how the IRR changes across a range of exit cap rates and occupancy assumptions gives you more actionable information than a probabilistic model that pretends to know the future. I typically build a dual-variable data table with occupancy on one axis and exit cap on the other. The output cells show IRR and equity multiple. This takes about twenty minutes to set up properly and saves hours of revision when a sponsor asks "what if we're wrong about the cap rate."
Common Pitfalls That Break Models
Hardcoding numbers inside formulas is the first thing to eliminate. Every input should live in an assumptions tab with a single cell reference used everywhere else. I once inherited a model where the property tax rate was embedded in twelve different formulas across six tabs, and someone had changed it in three places but missed nine. The property tax line item was understated by roughly $180,000 annually. Use cell references, not constants, for everything except calculated fields. Another frequent issue is inconsistent time periods. Some schedules will use monthly data and others will use quarterly, and the model will silently produce wrong answers when you blend them. Pick one frequency for the core model and convert everything else to match. Monthly is standard for cash flow timing, quarterly for financial statement presentation. Use a clear mapping between the two rather than trying to force everything into one period. Depreciation schedules often get simplified too aggressively. Straight-line depreciation over thirty-nine years for non-residential property is technically correct for tax purposes, but your model should track cumulative depreciation separately from book value, because the sale of the asset depends on adjusted basis, not just original cost. I modeled a 40-unit apartment complex where the sponsor wanted to see the impact of cost segregation on the sale timeline. The original model showed a clean 39-year depreciation schedule, but cost segregation reclassifies approximately 20% of the basis to shorter-life assets, which accelerates depreciation and creates a larger gain upon sale. Building that adjustment required a separate depreciation subgroup with different recovery periods, and it changed the IRR by nearly a full percentage point compared to the simplified version. That matters when you're making a buy-or-pass decision.
The biggest structural limitation of most CRE models is that they assume linear cash flows within each period. In reality, rent collections are staggered, expenses hit at different times, and capital expenditures don't arrive in uniform increments. A monthly model smooths over these timing differences, which is acceptable for underwriting but misleading for actual deal execution. If you need precision at the property level, switch to a daily cash flow model for the final twelve months before acquisition and the final year before disposition. The effort is worth it for transactions over fifty million dollars because the timing of a single large capex can shift which equity distribution gets taxed as ordinary income versus capital gain. If you want a template to start from, the standard approach is to build five tabs minimum: assumptions, operating statement, debt schedule, depreciation schedule, and financial statements. Add a sensitivity tab and an exit analysis tab before you present anything to investors. That structure covers the vast majority of underwriting scenarios without becoming unwieldy. Anything beyond that usually means you're solving a problem the deal doesn't actually have.