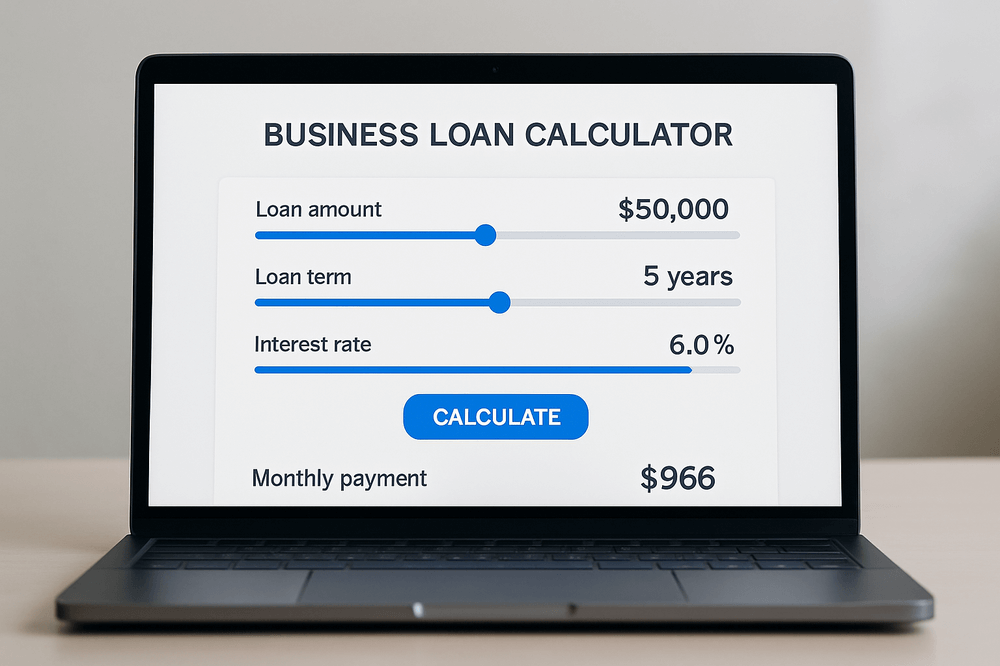
How Commercial Loan Calculators Actually Work
A Commerical Loan Calculator takes four inputs and produces a monthly payment number: principal amount, annual interest rate, loan term in years, and sometimes a balloon payment amount. The math underneath is standard amortization. You divide the annual rate by 12 to get your periodic rate, multiply the term by 12 for total periods, and plug everything into the formula. That's it. The calculator does the arithmetic so you don't have to. The formula looks like this: Monthly Payment = P × [r(1+r)^n] / [(1+r)^n - 1]. P is the principal. r is your monthly rate. n is the total number of payments. Any online calculator uses this exact same formula. The output isn't magic.
Using a Commerical Loan Calculator Correctly
Enter your numbers in the right fields. Make sure the interest rate is annual and the term is in years. If the calculator asks for the compounding frequency, commercial loans usually compound monthly. Some options let you add extra payments or select a balloon structure. Toggle those based on your actual loan terms, not the defaults. Here's the part most people skip: verify the output against a manual calculation at least once. I've seen online calculators return values that were off by $40 to $80 per month depending on how they handled rounding intermediate steps. That difference adds up over a 10-year commercial term. Take one calculation, compute it yourself in a spreadsheet with the same inputs, and compare. If the numbers match, you can trust the tool going forward. If they don't, pick a different calculator or build your own. Some tools also show a full amortization schedule. That table matters more than the single monthly payment number. Look at how the principal and interest split changes over time. Early payments are mostly interest. Later payments shift toward principal. This pattern doesn't change based on your loan type, but it affects your cash flow planning significantly in the first 24 months.
What These Calculators Miss
They miss the fees. Real commercial loans carry origination points, application fees, appraisal costs, legal fees, and sometimes servicing charges. An origination point is one percent of the loan amount. On a $500,000 loan, that's $5,000 paid at closing. The calculator won't fold that into your payment. It only calculates principal and interest. You have to add those costs separately to understand your true cost of borrowing. They also miss prepayment penalties. Many commercial loans have a yield maintenance clause or a fixed-period prepayment penalty. If you refinance early or sell the property before year three, you could owe thousands more than a simple calculator suggests. I learned this the hard way on a $1.2 million SBA 7(a) loan in 2019. The calculator showed a comfortable monthly payment of about $11,400. The actual cost of refinancing six months early included a yield maintenance penalty that added roughly $18,000 to the exit cost. The monthly payment looked fine. The exit didn't. Another gap: debt service coverage ratio. Lenders require your net operating income to exceed your annual debt service by a certain margin, usually 1.25 times. A calculator gives you the payment. It doesn't tell you whether the property actually qualifies. Run the numbers the other direction after you get your payment figure. Divide NOI by annual debt service. If the result is below 1.20, expect a tough underwriting process regardless of what the calculator says.
Get the Full Details

When to Build Your Own Instead
Sometimes you need more control than a web tool provides. If you're modeling multiple scenarios, comparing adjustable-rate structures, or incorporating variable rent roll assumptions, a custom spreadsheet saves time in the long run. Set up three input cells for loan amount, rate, and term. Use Excel's PMT function for the payment. Add columns for principal portion, interest portion, and remaining balance each month. Copy the formula down 120 or 360 rows depending on your term. It takes about 15 minutes to build and then you never have to re-enter the same inputs twice. The PMT function in Excel works like this: =PMT(rate, nper, pv). Rate is monthly rate. Nper is total payments. PV is the loan amount entered as a negative number so the result comes out positive. Simple. Repeatable. Under your control. Another scenario where a third-party tool falls short involves balloon payments. Some commercial loans require a large lump sum at the end of a shorter amortization period. Standard calculators handle this if you have the right field. Many don't. You'll need to calculate the remaining balance at the balloon date manually or find a specialized tool. The remaining balance equals the present value of all remaining scheduled payments, calculated at your original interest rate.
Practical Limitations to Keep in Mind
These calculators assume a fixed rate unless you tell them otherwise. Adjustable-rate commercial loans change with market indexes. The payment you see today might not be the payment you have next year. Some advanced calculators offer ARM modeling with adjustment caps and margins. If yours doesn't, you'll need to recalculate manually after each rate reset or use a tool that supports periodic re-amortization. Another limitation is assumption of perfect payment history. The calculator assumes you pay on time every month. Late payments, payment deferrals, or temporary interest-only periods change the actual cost. If your loan has a seasoning period or graduated payment structure, standard amortization math breaks down and the calculator output becomes unreliable. Finally, commercial loans often involve mixed-use properties or partial owner-occupancy. The lender may apply different debt service requirements based on occupancy percentage. A calculator treating the entire loan as a single number won't reflect those nuances. You need to model each occupancy category separately and combine the results.
For quick estimates and initial screening, an online Commerical Loan Calculator gets you in the right ballpark. For actual underwriting decisions or refinancing analysis, take the output and layer in the fees, penalties, DSCR requirements, and structural details that the calculator leaves out. The payment number is the starting point, not the finish line.