Building Credit History From Nothing
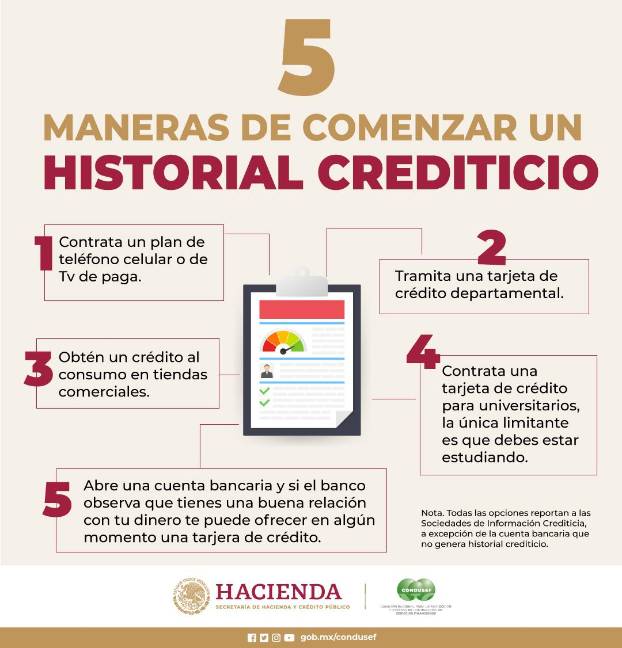
Most people get handed a credit report by someone else. Lenders see a number and decide in seconds whether you exist to them or not. The number is just a summary of your payment behavior, but it takes years to generate and about ten minutes to tank. I spent three years fixing a mix-up on a utility account that someone else filed under my Social Security number back in 2019. Took four phone calls and a faxed copy of a government ID to get it removed. That delay pushed my first real loan approval six months past where it should have been. The process starts with identity establishment, which sounds dramatic but really just means the bureaus need to connect your name, address, and Social Security number to an account. A secure, straightforward path for Como Hacer Historial Crediticio is to open a secured credit card or become an authorized user on a family member's old account. Both methods work, but they produce different results on your report and that distinction matters more than most people realize.
Como Hacer Historial Crediticio: The Practical Path
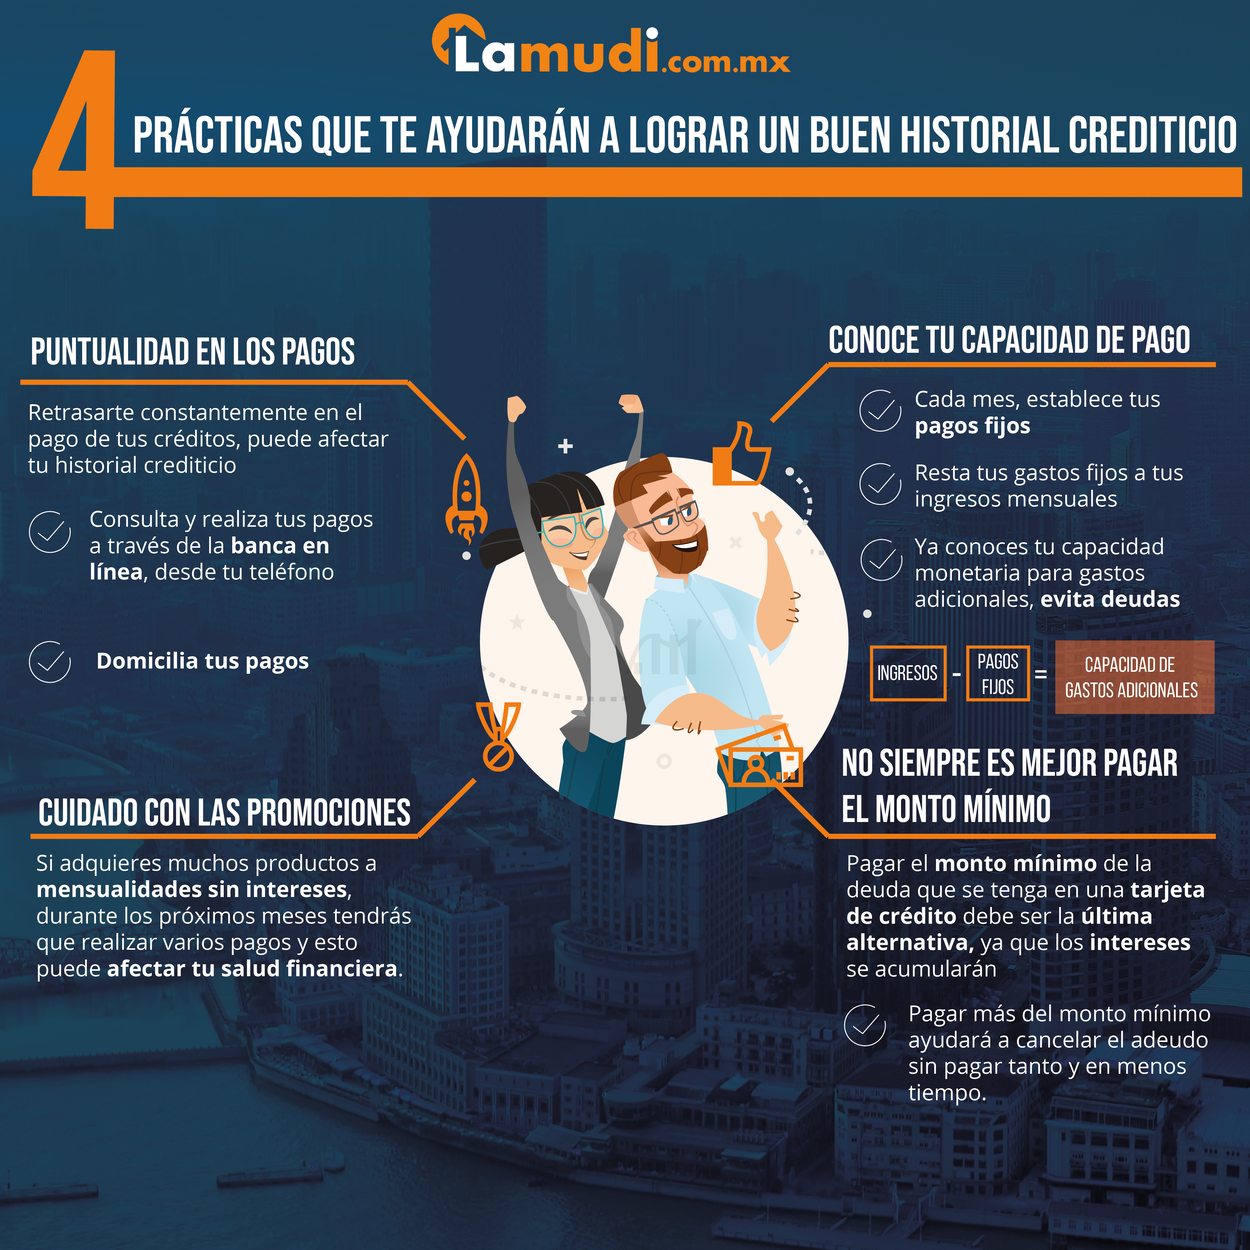
A secured card requires a cash deposit that becomes your credit limit. You put down five hundred dollars, you spend five hundred dollars, you pay it off every month. After about twelve to eighteen months of on-time payments, most issuers will transition you to an unsecured card and return the deposit. Discover and Capital One both do this without making you ask. The trap here is that some secured cards report to only one or two of the three major bureaus. Before you apply, check which bureaus the issuer reports to. TransUnion, Equifax, and Experian are the big three in the United States, but a card that only hits two of them leaves a gap that will show up when you later apply for an apartment or auto loan. Becoming an authorized user works differently. The primary account holder adds you to their existing credit card, and the account age and payment history of that card flow onto your report as well. This can generate a credit history in a matter of days instead of months. The catch is that you do not control the primary holder's behavior. If they miss a payment, it shows up on your report too. I had a friend whose father added him as an authorized user on a card that had been open for twenty years with perfect payments. Three years later the father stopped paying during a layoffs period, and my friend watched his own score drop forty points in a single month. Not recoverable until the late payments aged out, which takes seven years. Credit builder loans are the third common route. A credit union or online lender locks your money in a savings account while you make fixed monthly payments. Once the loan is paid off, you get the funds back. Self, for instance, offers this through direct deposit and automated payments. The downside is that these loans typically charge higher effective interest rates than you would pay on a traditional installment loan because the lender is capturing the float on your deposited money. Over a twelve-month period on a thousand dollar loan, you might pay somewhere between eighty and one hundred fifty dollars in fees, which works out to roughly eight to fifteen percent APR depending on how you calculate it. That is steep for what is essentially forced savings, but the reporting to all three bureaus makes it worthwhile if you have no other options.
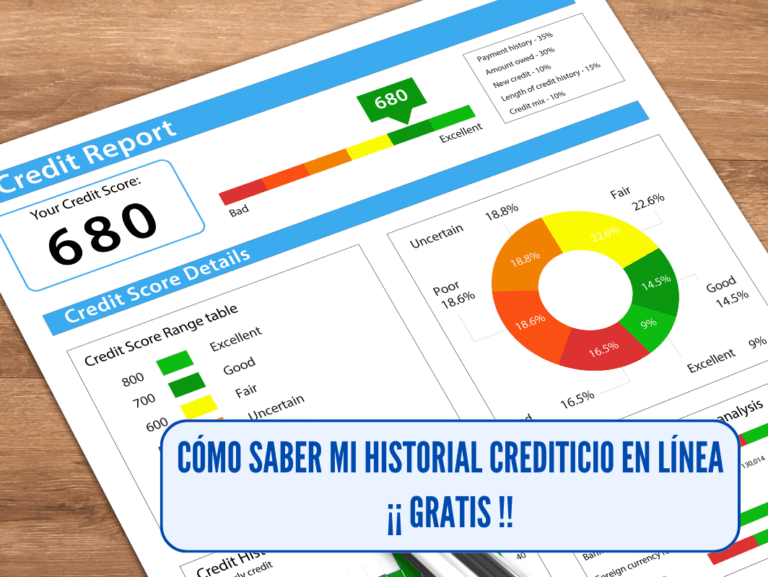
The scoring models themselves are where people get confused. FICO and VantageScore both exist, and they weight factors differently. Payment history dominates both at about thirty-five percent, but FICO looks at the depth of your credit mix while VantageScore weights utilization and total balance more heavily. This means the order in which you add accounts can change your score trajectory. Opening a secured card first, waiting six months, then adding a credit builder loan usually produces a smoother climb than doing both simultaneously, because the latter spikes your hard inquiries and makes your profile look thin across categories.
Get the Full Details
What Nobody Tells You About Credit History
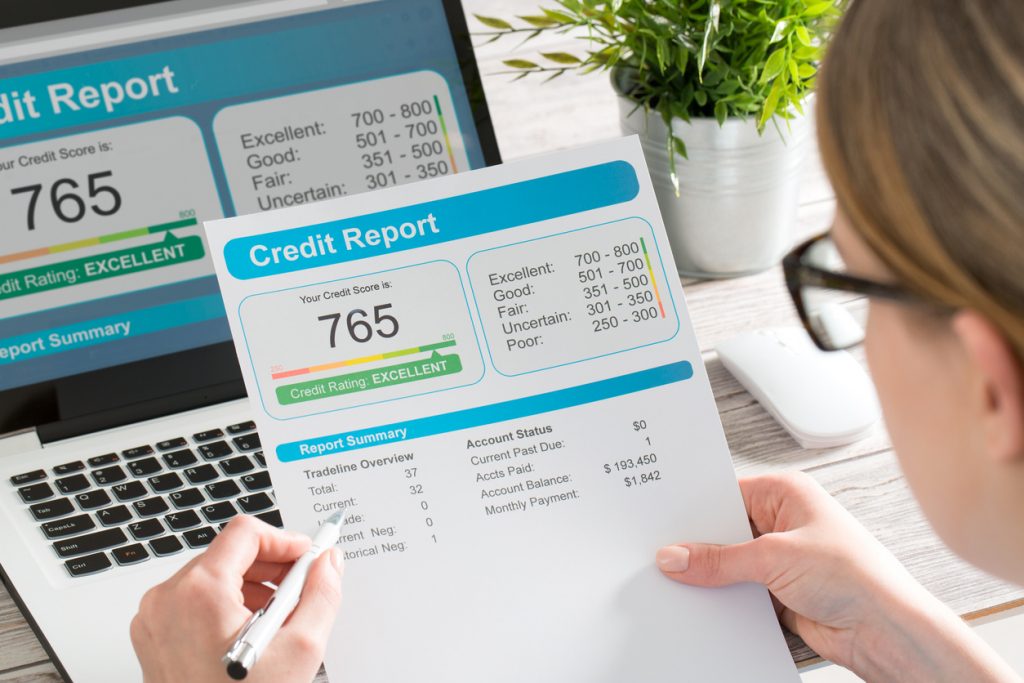
The most counter-intuitive thing I have seen repeatedly is that having no credit is actually worse than having thin credit with one or two minor blemishes. A brand new file with zero negative marks still scores around five eighty to six hundred depending on the model, but a file with one thirty-day late payment from two years ago and otherwise solid behavior often scores higher. Why? Because the scoring models penalize inactivity more than they penalize old, resolved mistakes. A thin file tells the model nothing about how you handle risk under pressure. A file with one resolved delinquency shows you recovered from it. It sounds backwards, but it is exactly how the algorithms are calibrated. Another thing that trips people up is the difference between utilization rate and total debt. A person carrying five thousand dollars in credit card debt with a ten thousand dollar total limit has a fifty percent utilization and will be crushed. Another person carrying five thousand dollars in debt across fifty thousand dollars in total limits has ten percent utilization and looks fine. The total available credit matters more than the raw balance amount. This is why people who max out a single card while also having unused cards elsewhere still get penalized heavily. The scoring model calculates overall utilization, not per-card utilization, and most people do not realize this until they see the numbers. Hard inquiries deserve a straightforward explanation too. Applying for credit generates a hard pull, and each one dents your score by roughly five to ten points. The damage fades within twelve months and the inquiry drops off your report entirely after two years. But applying for five cards in a thirty-day window compounds the effect because most scoring models treat multiple applications for the same type of credit within a short window as a single inquiry for scoring purposes. Still, the cumulative hit from five separate applications is real even if the model bundles them. Space your applications out by at least sixty days if you can.
When The System Fails You
Not every situation resolves cleanly. File freezes and disputes take time. The Fair Credit Reporting Act gives bureaus thirty days to investigate a dispute, but in practice they often take the full thirty days and sometimes longer if the creditor does not respond promptly. During that window, your score may dip or stagnate because the disputed item remains listed. I once waited eleven weeks for a collection account to be removed after a creditor failed to verify the debt during the dispute process. The bureau eventually deleted it, but by then I had already been denied for a mortgage because the item sat there through the underwriting review. Identity theft creates a different problem entirely. If someone opens an account in your name, it contaminates your entire file, not just the fraudulent account. The fraudulent trade line drags down your score, and resolving it requires filing a police report, sending documentation to the bureaus, and sometimes writing formal dispute letters to each creditor involved. This can take three to six months to fully clear. The workaround I learned the hard way is to place a fraud alert or security freeze immediately upon suspicion. A fraud alert is free and lasts one year. A security freeze is permanent until you lift it. A freeze prevents any new account from being opened in your name, which stops the bleeding while you clean up the damage. Mixing accounts across different bureaus can also create gaps. Some lenders report only to TransUnion. Others report only to Experian. If you build credit through lenders that only report to one bureau, you may end up with a strong file at one agency and a thin file at another. When a landlord runs a comprehensive three-bureau pull, the unevenness becomes obvious. The solution is to intentionally diversify your reporting across all three bureaus from the start. Use a secured card that reports to all three, a credit builder loan that reports to all three, and an authorized user arrangement on a card that reports to all three. It takes more coordination upfront but saves significant pain later.
The bottom line is that building credit history is mechanical, not magical. It requires consistent payment behavior over time, strategic account placement, and patience while the models accumulate enough data to produce a stable score. There is no shortcut that does not carry a cost, and some shortcuts carry costs you will not see until you are standing in front of a loan officer who sees red flags your score alone does not show.