Checking Your Credit Report Without Losing Your Mind
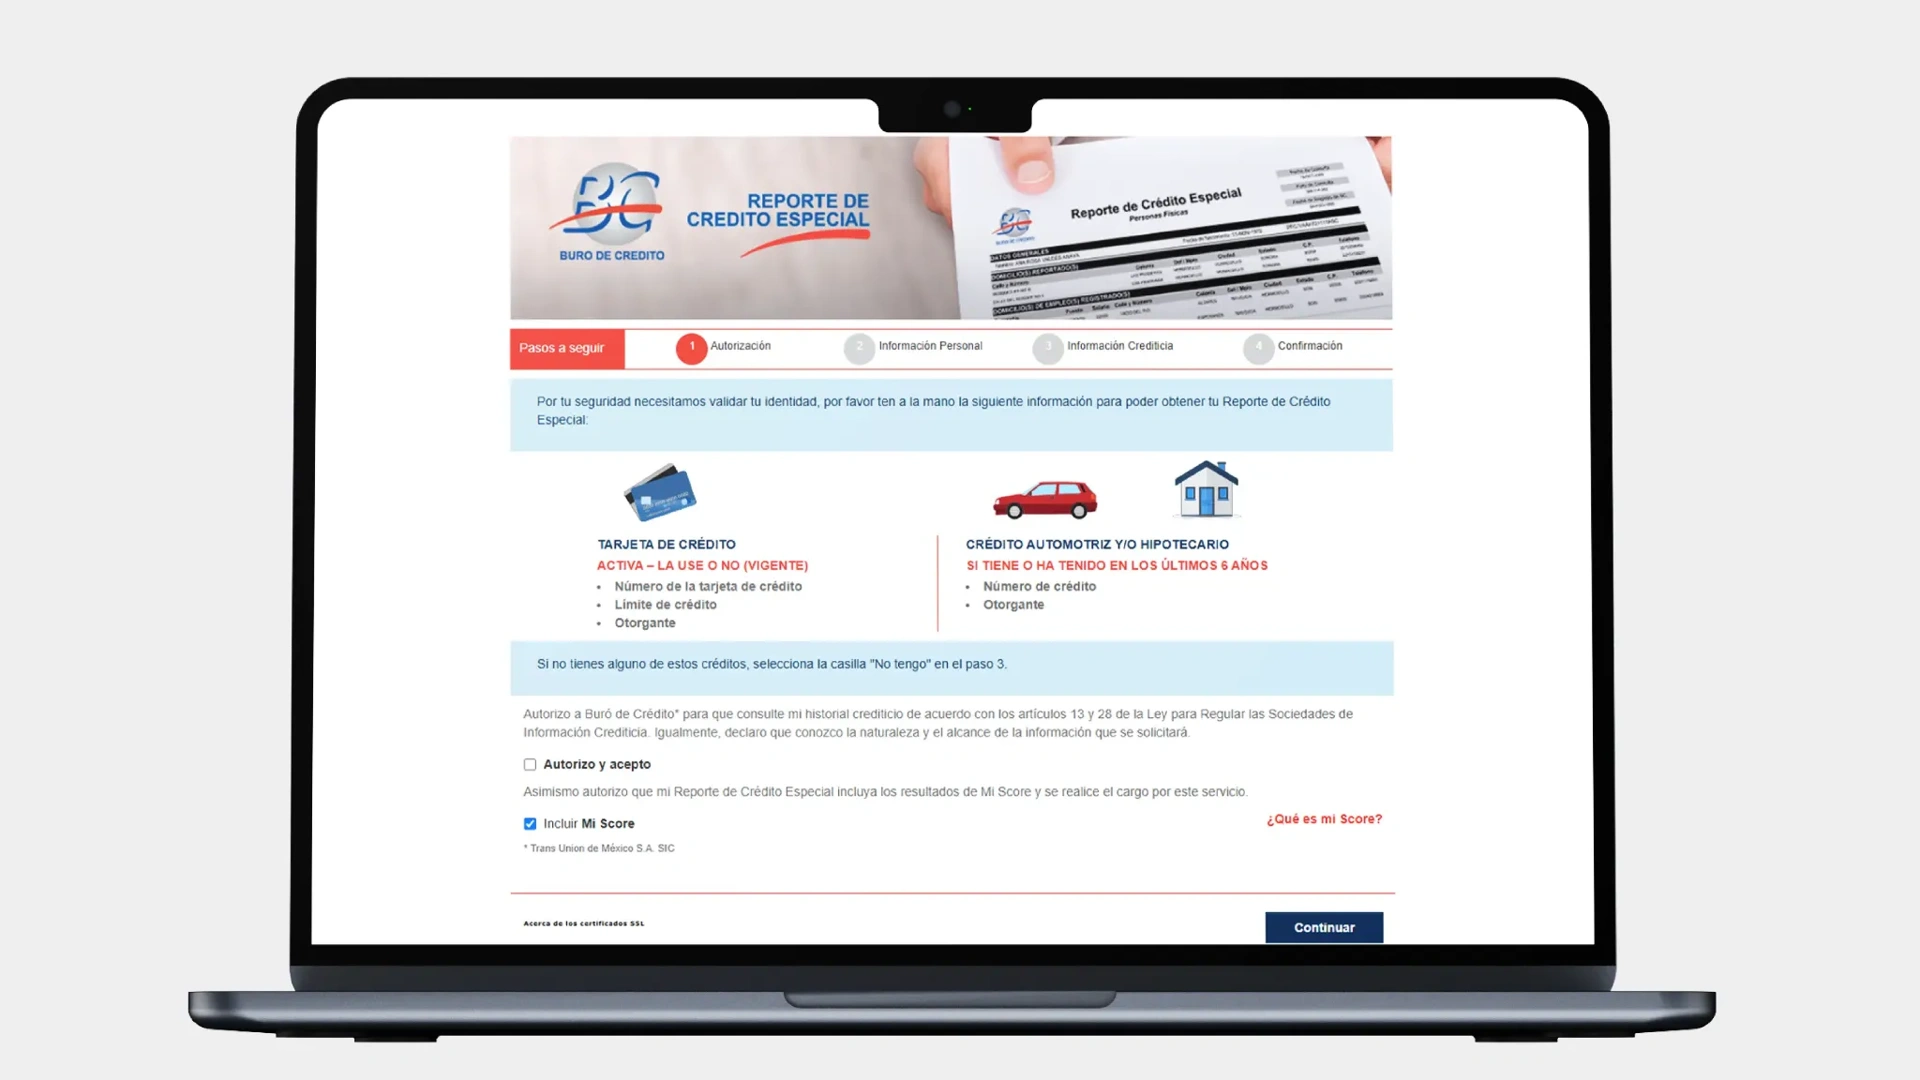
Most people don't realize they can pull their own credit report for free, and the ones who do usually get tripped up by the process because the websites are designed to sell you things. Here is how it actually works. In the United States, you are entitled to one free credit report per year from each of the three major bureaus — Equifax, Experian, and TransUnion — through AnnualCreditReport.com. That is the official government-authorized portal. There are three other sites that look similar but charge you for fraud monitoring and credit scores after a trial period. Do not get confused. I spent an afternoon in 2022 trying to pull my own reports because a mortgage lender told me my numbers looked off, and I ended up accidentally subscribing to a service that billed me $49 a month for six months. The site was AnnualCreditReport.com plus something called "AnnualCreditReport Pro" or some variation that lived on the same page. I caught it when my bank statement hit, which was exactly three weeks too late to fight the first charge before the next one came through. The workaround was calling the number on the back of my credit card, disputing the charge as unauthorized, and then going back to the actual AnnualCreditReport.com and ordering each bureau separately. It took forty-five minutes and two phone calls. After that, I just log in once every twelve months and do them all at once.
Como Puedo Saber Mi Historial Crediticio
For Spanish speakers, the question Como Puedo Saber Mi Historial Crediticio is really just asking about the same process, but there are additional layers most guides skip. If you have limited English proficiency, you can request your report in Spanish through the same AnnualCreditReport.com portal. The English-only version of that site does not offer a full Spanish translation, but each of the three bureaus produces reports in Spanish upon request if you call them directly. Experian's Spanish line is 1-888-397-3742, TransUnion has a dedicated Spanish service at 1-800-680-7289, and Equifax routes you through their main line but will generate a Spanish report if you specify that need. The wait times are longer — expect twenty to thirty minutes on hold during business hours, which run Monday through Friday from 8 AM to 8 PM Eastern Time. There is also the option of pulling your report through your bank or credit card issuer. Many major banks now offer free credit scores through their apps — Chase, Bank of America, Capital One, Citi — but these are usually FICO or VantageScore snapshots, not the actual credit report. A credit score is a three-digit number derived from your report. A credit report is the full document listing every account, inquiry, and negative item. You need the report, not the score, when you are trying to understand what is actually on file. I learned this the hard way when a auto loan application was denied and my credit card app only showed me a score of 712. I had no idea that one collection account from a 2019 medical bill was sitting there with a $340 balance. The score did not reflect the depth of the problem. The report did. One thing that trips people up constantly: your credit report and your credit score are two different things. Pulling your report does not hurt your score. Checking your own report generates a soft inquiry, which does not factor into scoring models at all. Hard inquiries — the ones a lender generates when you apply for credit — can drop your score by a few points each. So you can and should check your report regularly. Just do it through the official free channels, not the commercial ones that try to upsell you on identity theft protection.
Here is a detail nobody mentions unless they are a credit counselor: errors on credit reports are surprisingly common. The Federal Trade Commission estimated that about one in five consumers has at least one error on their credit report, and some of those errors are significant. I found a duplicate collection entry on my TransUnion report that doubled the negative impact on my score. It was a medical bill from the same provider, reported twice under slightly different account numbers. Disputing it required a written dispute letter with a copy of the bill and a demand for deletion. I sent it via certified mail with return receipt requested. The bureau had thirty days to investigate, and they removed the duplicate entry fourteen days later. My score jumped 23 points. That was worth the hour of work and the $12 in certified mail supplies. Another counter-intuitive fact: paying off a collection account does not remove it from your credit report. It updates the balance to zero and changes the status, which is better than nothing, but the entry itself stays for seven years from the date of first delinquency. Some newer scoring models, like FICO 9 and VantageScore 3.0 and 4.0, ignore paid collections entirely, but most lenders still use older versions. So a paid collection still hurts more than an unpaid one in many cases because it signals the pattern even if the debt is resolved. The only way to truly remove a negative item before seven years is if it is inaccurate. Verify everything before you pay anything. When you request your report, you will get a detailed breakdown. Pay attention to the "public records" section and the "accounts" section. Public records include bankruptcies, tax liens, and civil judgments. Bankruptcies stay for ten years. Tax liens, if they appear, stay for seven years from the payment date. Most other negative items — late payments, charge-offs, collections — stay for seven years from the date of the first missed payment that led to the negative status.
Get the Full Details
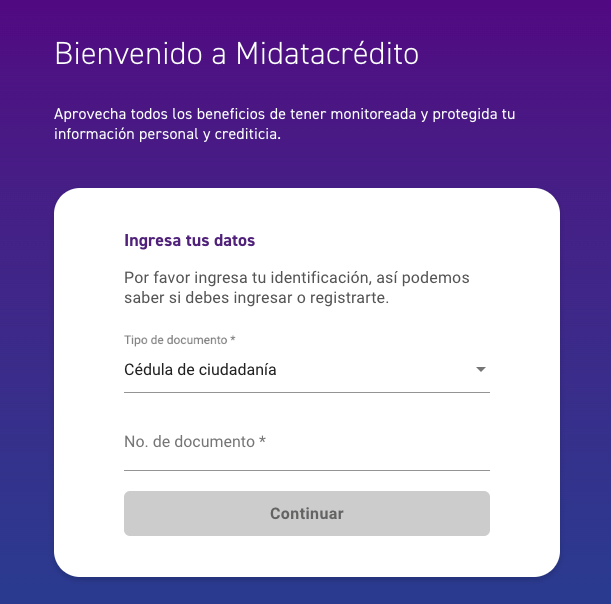
If you are reviewing a report for the first time, start with the accounts section and look for anything you do not recognize. An account you never opened is a sign of identity theft. A account in collections that you already paid is a reporting error. A late payment from three years ago that is actually from last month is a data error. Each of these requires a different dispute process, but the mechanism is the same: file a dispute with the bureau that reported the item, provide documentation, and wait for the investigation. Under the Fair Credit Reporting Act, the bureau must respond within thirty days and either correct or confirm the item. If they confirm it and you still disagree, you can add a statement of dispute to your file that future lenders will see. The biggest bottleneck in this whole process is the verification step. AnnualCreditReport.com will ask you to verify your identity using personal information that may have changed. Wrong address, wrong Social Security number format, or a name change that has not been updated across all bureaus will cause the request to fail. I had this happen twice in my first round of requests. Each time, I had to call the bureau directly, provide a copy of my driver's license and a recent utility bill, and manually place the report order. It added about an hour to the process. If your request keeps getting rejected, switch to calling the bureau directly instead of re-submitting online. There are services that promise to remove negative items for you. Credit repair companies. They operate on a legal technicality — the Fair Credit Reporting Act gives you the right to dispute inaccurate information, and these companies file disputes on your behalf. The problem is that they cannot do anything you cannot do yourself, and they typically charge $80 to $150 a month. I watched a friend pay over a thousand dollars to a credit repair service that ended up doing the exact same thing he could have done by mailing certified letters from his kitchen table. The only time these services make sense is if you have a very complex dispute situation involving multiple bureaus and multiple errors, and even then, the ROI is questionable.
For most people, the free annual report is enough. If you are actively working to improve your credit, pull a report every four months — one from each bureau, staggered — so you catch new errors quickly and track progress. The system updates on different schedules depending on the bureau. Equifax tends to update within 30 to 45 days of creditor reporting. Experian and TransUnion vary. There is no single update day, so checking every few months gives you a more complete picture than waiting a full year. If you want your actual credit score rather than just the report, you can get it for free from several sources. Credit Karma offers VantageScore 3.0 from TransUnion and Equifax. Experian provides a free FICO score through its app if you link a bank account. Discover gives a free FICO score to cardholders. These are accurate reflections of your current score, though they may differ slightly from the score a lender pulls because lenders use specific variants and update at different times. The free score tools are useful for monitoring trends but should not be treated as the definitive number you will get at loan closing. The bottom line is this: your credit history is public record in the sense that any authorized party can access it, and you have the legal right to review it yourself without paying a cent. The process is straightforward if you use the right channels. It gets complicated when you find errors or when your personal information does not match what the bureaus have on file. Those are the situations where patience and paper trails matter more than anything else.