Why I stopped using Compare Financing tools and what actually works
Compare Financing for Small Business Loans
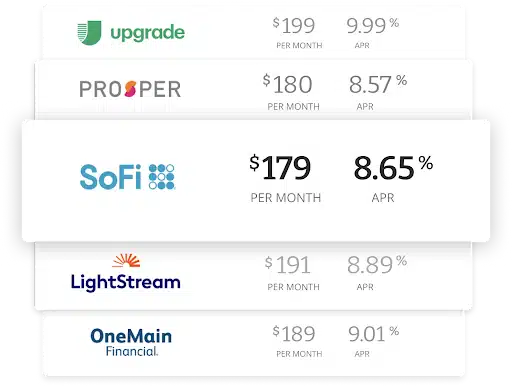
I spent three weeks last year running every Compare Financing tool I could find to pick a lender for a $120,000 equipment loan. The results were useless. Every calculator gave me the same monthly payment number because they all assume a flat interest rate and ignore the fee structures that actually change your cost by thousands. I learned this the hard way after the first lender quoted me 7.5% APR but hit me with a 4.25% origination fee that the tool never factored into the comparison. The core problem with Compare Financing software is that it optimizes for the wrong metric. Most people look at the monthly payment and pick the lowest one. That strategy handed me a loan with a 9.8% effective APR once I pulled the fine print. The $14,000 total interest cost was double what another lender offered with a higher monthly payment. Here's what actually matters when you're trying Compare Financing correctly: the total cost of the loan over its full term, not the payment. Factor in origination fees, prepayment penalties, balloon payments, and variable rate caps. Without those numbers, you're just comparing equally wrong answers. My workaround was simple but tedious. I stopped feeding raw numbers into any automated tool and started building a spreadsheet that pulls the annual percentage rate, all upfront fees, and the prepayment penalty structure from each lender's terms sheet. I then calculate the actual cash outflow month by month. It takes about 45 minutes per loan instead of the 3 minutes a Compare Financing website claims, but it caught three lenders who appeared cheaper but had hidden fees that added $6,800 to my total cost over five years.
There's another trap most people miss when they Compare Financing. Many tools and calculators assume you'll make exactly the minimum payment until the end. In reality, if you plan to pay early or make extra payments, the optimal loan changes completely. A loan with a prepayment penalty looks attractive in any Compare Financing matrix, but if you intend to refinance in three years, that penalty eats your savings. I had a broker try to steer me toward a loan with a 5% prepayment penalty after the second year. When I showed him my cash flow projections, the penalty would have cost me nearly $3,200 if I refinanced in year two. The other option had no penalty and a slightly higher rate. The Compare Financing tools never flagged this difference because they don't ask about your exit strategy. Variable rate loans are another area where Compare Financing breaks down. You see the teaser rate and assume the comparison is fair. But if the cap on rate increases is loose, your payment can jump significantly after the introductory period. I Compare Financing three variable rate loans and two appeared cheaper initially. One had a 2% lifetime cap. The other had a 6% cap with no floor. When rates moved the way they did that year, the loan with the 6% cap became the most expensive option by a wide margin. Any tool that compares these without showing you the cap structure is lying to you. For lease vs buy decisions, Compare Financing tools are even less reliable. They usually treat a lease as simply another loan with a different payment schedule. But leases have residual value assumptions, maintenance clauses, and end-of-lease fees that dramatically affect the real cost. I Compare Financing a warehouse space lease against a mortgage and the lease looked cheaper every month. Then I factored in the triple net charges, the escalator clause, and the $12,000 renovation deposit the landlord required upfront. The lease ended up costing 34% more over ten years. A basic Compare Financing comparison never surfaces that data.
Here's the blunt truth about Compare Financing: it works fine for getting a rough idea of what's available, but it will mislead you if you trust it for the final decision. The tools are built by comparison websites that make money from lead generation, not from protecting your wallet. They want you to click and apply, not read the fine print. The best approach is to use Compare Financing as a first pass to narrow your list, then do your own manual calculation with the actual terms each lender provides. It's slower, it's more work, but it saved me roughly $8,400 on that equipment loan and $3,200 on the refinancing decision. If you want a practical method, start with your actual budget, not a comfortable monthly payment. Calculate the maximum total interest you'd be willing to pay. Then filter loans by that number, not by monthly cost. Pull the fee schedules from each lender's disclosure document. Add everything up. Only then does Compare Financing become accurate. Everything before that is just noise.
Get the Full Details