The Math Behind Borrowing Less Money
I keep seeing people run two loan quotes side by side and trust their gut on which looks better, then wonder why the monthly payment still stings. The problem is usually that they are comparing principal amounts or nominal rates without normalizing the other variables. A proper comparison needs the interest rate, the term, the compounding frequency, and any fees folded into one number. Most calculators of this type ask for three inputs: the annual percentage rate, the loan amount, and the repayment term in months. Some also let you add closing costs or origination fees. The output is a monthly payment figure and a total cost of borrowing. You run the same three numbers for each offer and look at the difference in monthly payment and total interest paid. Here is how the core calculation works. The monthly rate is the annual percentage rate divided by twelve. The number of payments is the term in months. The monthly payment formula is the loan amount multiplied by the monthly rate, divided by one minus one plus the monthly rate raised to the negative number of payments. Total cost is the monthly payment times the number of payments plus any upfront fees. This is standard amortization math, nothing secret about it.
I found a practical edge case last year when comparing two mortgage offers from different banks. Both quoted the same nominal rate, but one used daily compounding and the other used monthly compounding. The calculator I was using assumed monthly compounding for both, so it showed them as identical. The daily compounding loan actually cost more over the life of the loan because interest accrued faster between payment dates. I had to adjust the effective annual rate myself by applying the formula for daily compounding: one plus the nominal rate divided by three hundred sixty-five, raised to the power of three hundred sixty-five, minus one. Once I did that, the calculator gave me the right answer. Another issue I run into often is fee handling. Some lenders roll points into the rate and quote a lower number, while others keep points separate and show a higher rate with an upfront cost. If you only look at the rate without the fee structure, the cheaper rate can end up costing more overall. Always add origination fees, discount points, and appraisal costs to the total before comparing. There is also the matter of prepayment penalties. A calculator will not show you this unless you enter it explicitly, but it can change the outcome dramatically if you plan to refinance or sell early. One loan might have a lower monthly payment but a five percent prepayment penalty in year two. That penalty wipes out any savings from the lower rate if you move within that window.
What many people miss is that the compare tool is only as good as the data you feed it. Lenders sometimes quote teaser rates that reset after six months. If you do not include the adjusted rate and the new payment schedule, the calculator will show you a picture that disappears halfway through the loan. Always read the fine print on rate locks and adjustment periods before you run the numbers. I also recommend running a sensitivity check. Change the interest rate by half a percent and see how much the monthly payment moves. This tells you how risky each offer is if rates shift or if your budget tightens. A loan with a slightly higher rate but a fixed structure may be safer than one that looks cheaper now but could jump significantly later. If you want a simple tool to handle this, search for an online Compare Loan Rates Calculator. Many are free and let you paste in multiple loan offers at once. Some even export the results to a spreadsheet so you can tweak the assumptions. I use one that lets me save scenarios, because going back to a previous quote is easier when you have the numbers recorded somewhere.
Get the Full Details
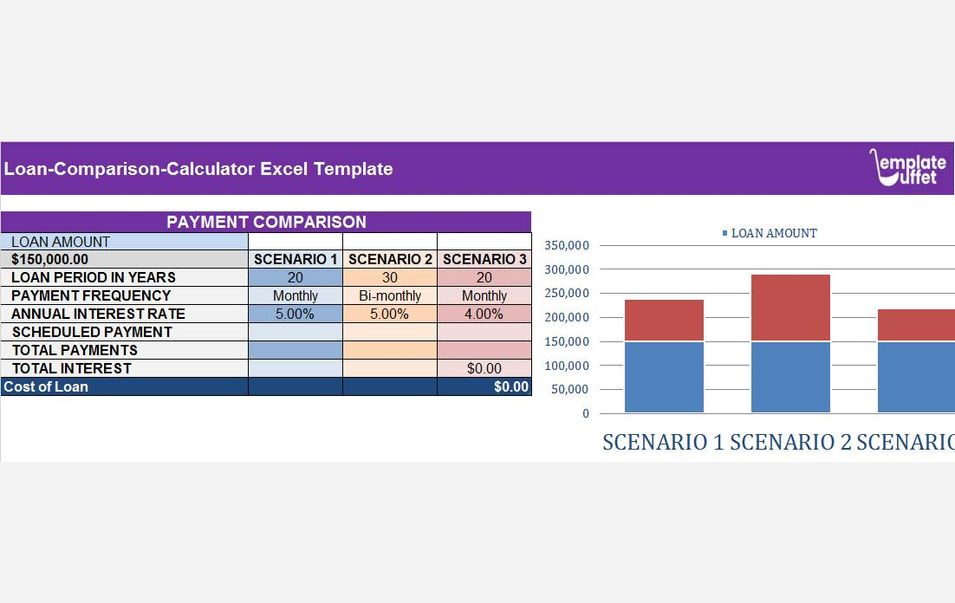
There are downsides to relying on these calculators alone. They assume you will make every payment on time, which is reasonable but not guaranteed. They do not account for changes in your financial situation, tax implications, or the opportunity cost of tying up cash in a down payment. Use them as a starting point, not the final word. A human review of the loan documents is still necessary, especially for large loans where a single misplaced decimal point can cost thousands. The bottom line is that the comparison math is straightforward, but the details matter. Run the numbers carefully, include all fees, adjust for compounding differences, and check for hidden costs like prepayment penalties. Then sleep on it before you sign anything.