How I Actually Use a Compare Mortgage Offers Calculator
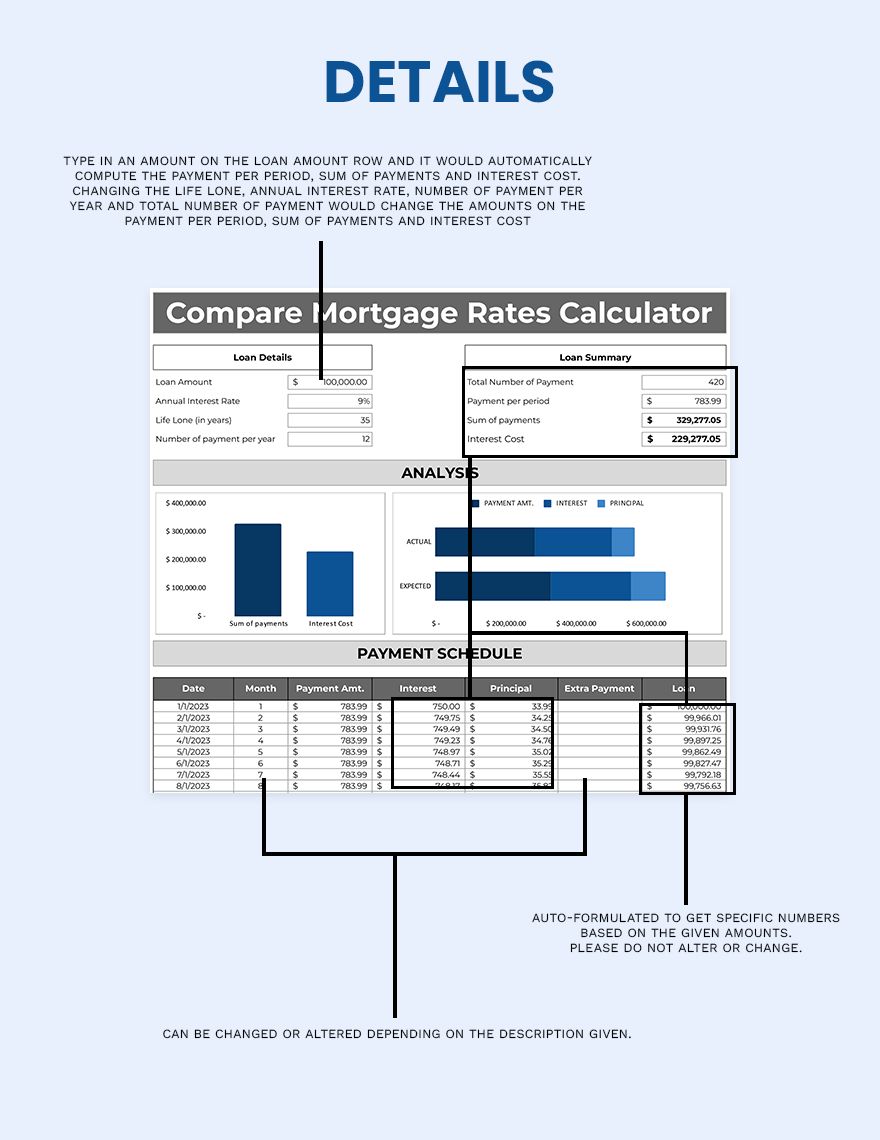
I spent about three years working in mortgage origination before moving to the advisory side, and I learned pretty quickly that most people do not understand how these tools actually work under the hood. They open one, type in some numbers, and call it a day. The problem is that the output from a Compare Mortgage Offers Calculator is only as useful as the inputs you feed it and the assumptions baked into the model. I am going to walk through what these tools do, where they fail, and what you need to look at before you hand your decision over to some screen. The basic idea is simple enough. You plug in loan amount, interest rate, loan term, down payment, property tax, homeowners insurance, and sometimes PMI or HOA fees. The calculator runs each set of numbers through an amortization schedule and gives you monthly payments plus total interest paid over the life of the loan. Some include closing costs. Most do not do a very good job of including closing costs properly. Here is the thing most people miss. The calculator will happily show you that Loan A costs $1,847 per month and Loan B costs $1,912 per month and declare Loan A the winner. But it might not be telling you that Loan A has an adjustable rate that resets in five years while Loan B is fixed, or that Loan A charges $6,200 in discount points while Loan B has zero points but a higher rate. The raw monthly number is only one slice of the pie. You have to pull up the loan estimates and compare the actual line items, not just the bottom line.
I remember one client who had pulled offers from four lenders and was about to pick the one with the lowest monthly payment because she used a Compare Mortgage Offers Calculator and the numbers looked clear. When I looked at the actual loan estimates, two of those lenders had bundled appraisal fees, processing fees, and document preparation charges into their quoted rates in a way that made the comparison meaningless. The lender with the second-lowest calculated payment ended up being $4,800 cheaper at closing and had a genuinely lower rate after adjustments. She would have picked the wrong one if she had only looked at the calculator output.
The Numbers You Actually Need to Plug In
Your loan amount is the principal. That is straightforward. Interest rate is what each lender quotes on the note. Loan term is usually 30 years or 15 years, though you will see 20-year and adjustable mortgages thrown in. Down payment determines your loan-to-value ratio, which matters because it affects whether you pay PMI. Property tax and insurance are estimates from the purchase contract or your current bill. PMI is required if your down payment is under 20 percent, and it typically runs between 0.5 and 1 percent of the loan amount annually until you reach 20 percent equity. Here is a detail nobody tells you about PMI calculations. Some lenders automatically drop it when you hit 78 percent LTV. Some require you to request removal at 80 percent. Others make you refinance to get rid of it. A Compare Mortgage Offers Calculator will almost never factor this in correctly because it does not know your payment history or your lender's specific policies. You need to know this before you do the comparison. Otherwise you are comparing two loans that appear equal on paper but cost very different amounts in reality once PMI gets removed at different times. Closing costs are the other silent variable. Federal law requires lenders to provide a Loan Estimate within three business days of your application, and that document breaks down every fee. Origination charges, appraisal, credit report, title search, title insurance, recording fees, transfer taxes, prepaid interest, escrow deposits. These can range from 2 to 5 percent of the loan amount depending on where you live and which lender you pick. A good calculator lets you enter closing costs as a separate field. Most cheap online ones do not. I usually take the calculator output and then build a separate spreadsheet that adds the actual closing cost numbers from each Loan Estimate so I can compare total cash needed at closing alongside monthly payment.
Get the Full Details
What These Calculators Get Wrong and When They Break
The biggest issue is that they assume your situation stays static. They do not account for rate changes, payment resets, tax assessments going up, or insurance premiums jumping. If you are comparing a 5/1 adjustable-rate mortgage against a 30-year fixed, the calculator will show you the ARM's discounted rate for five years and then just stop. It will not model what happens after the adjustment. You need to ask the lender for the fully indexed rate and run those payment projections yourself using the margin and the index they are tied to. I had a situation last year where a borrower was choosing between two lenders for a jumbo loan. The Compare Mortgage Offers Calculator showed one lender with a monthly payment that was $97 lower. But that lender was offering a rate buydown that only lasted for the first 12 months. After year one the rate stepped up and the payment jumped by about $210. The other lender had a slightly higher rate but no buydown, meaning the payment stayed flat. Over five years the first lender ended up costing roughly $3,400 more in total. The calculator did not flag this because the buydown period was buried in the rate sheet, not in the fields the tool asks for. Another common failure point is how prepayments are handled. If you plan to make extra payments or refinance in a few years, the total interest column in the calculator becomes misleading. A loan with a lower rate but heavy upfront points might look worse if you plan to sell before breaking even on those points. I calculate the break-even period for points manually. Take the total cost of the points and divide by the monthly savings they generate. If you plan to move or refinance before that number comes out, the points are a bad deal regardless of what the calculator says.
Practical Workflow I Use
First I collect the Loan Estimates from every lender. Not the rate quote sheets. The actual Loan Estimates. They are standardized documents now, so comparing line 2 through line 8 across lenders is straightforward. Then I feed the core numbers into a Compare Mortgage Offers Calculator to get monthly payment baselines. After that I build a side-by-side that includes total closing costs, break-even analysis for rate buydowns, and projected total cost over however long I expect the borrower to actually hold the loan. Usually that is five to ten years for most people, not the full 30. This process takes me about 20 minutes per borrower once I have all the Loan Estimates in front of me. Doing it by eye without any tool takes me about 45 minutes and produces worse results because I miss small fee differences. The calculator handles the arithmetic. The human part is deciding which numbers actually matter and catching the stuff the tool is not designed to show you.
When You Should Not Trust a Compare Mortgage Offers Calculator
If you are comparing loans from the same lender with the same product type, the calculator is fine. The marginal differences are small enough that the output is accurate. If you are comparing an FHA loan against a conventional loan, an ARM against a fixed, or a purchase against a refinance, the calculator becomes unreliable. The underlying structures are too different and the assumptions required to make them comparable introduce too many errors. In those cases the Loan Estimate documents are your real tool. Read them. Line by line. The calculator is a helper, not a decision maker. I also do not trust them for unusual cases. Self-employed borrowers with non-standard income documentation, VA loans with funding fees, construction-to-permanent loans, or portfolio loans from community banks. These products have fee structures and payment mechanics that standard calculators simply were not built to handle. I end up doing manual amortization schedules in Excel for those situations. It takes longer but it is the only way to be sure the numbers are right.