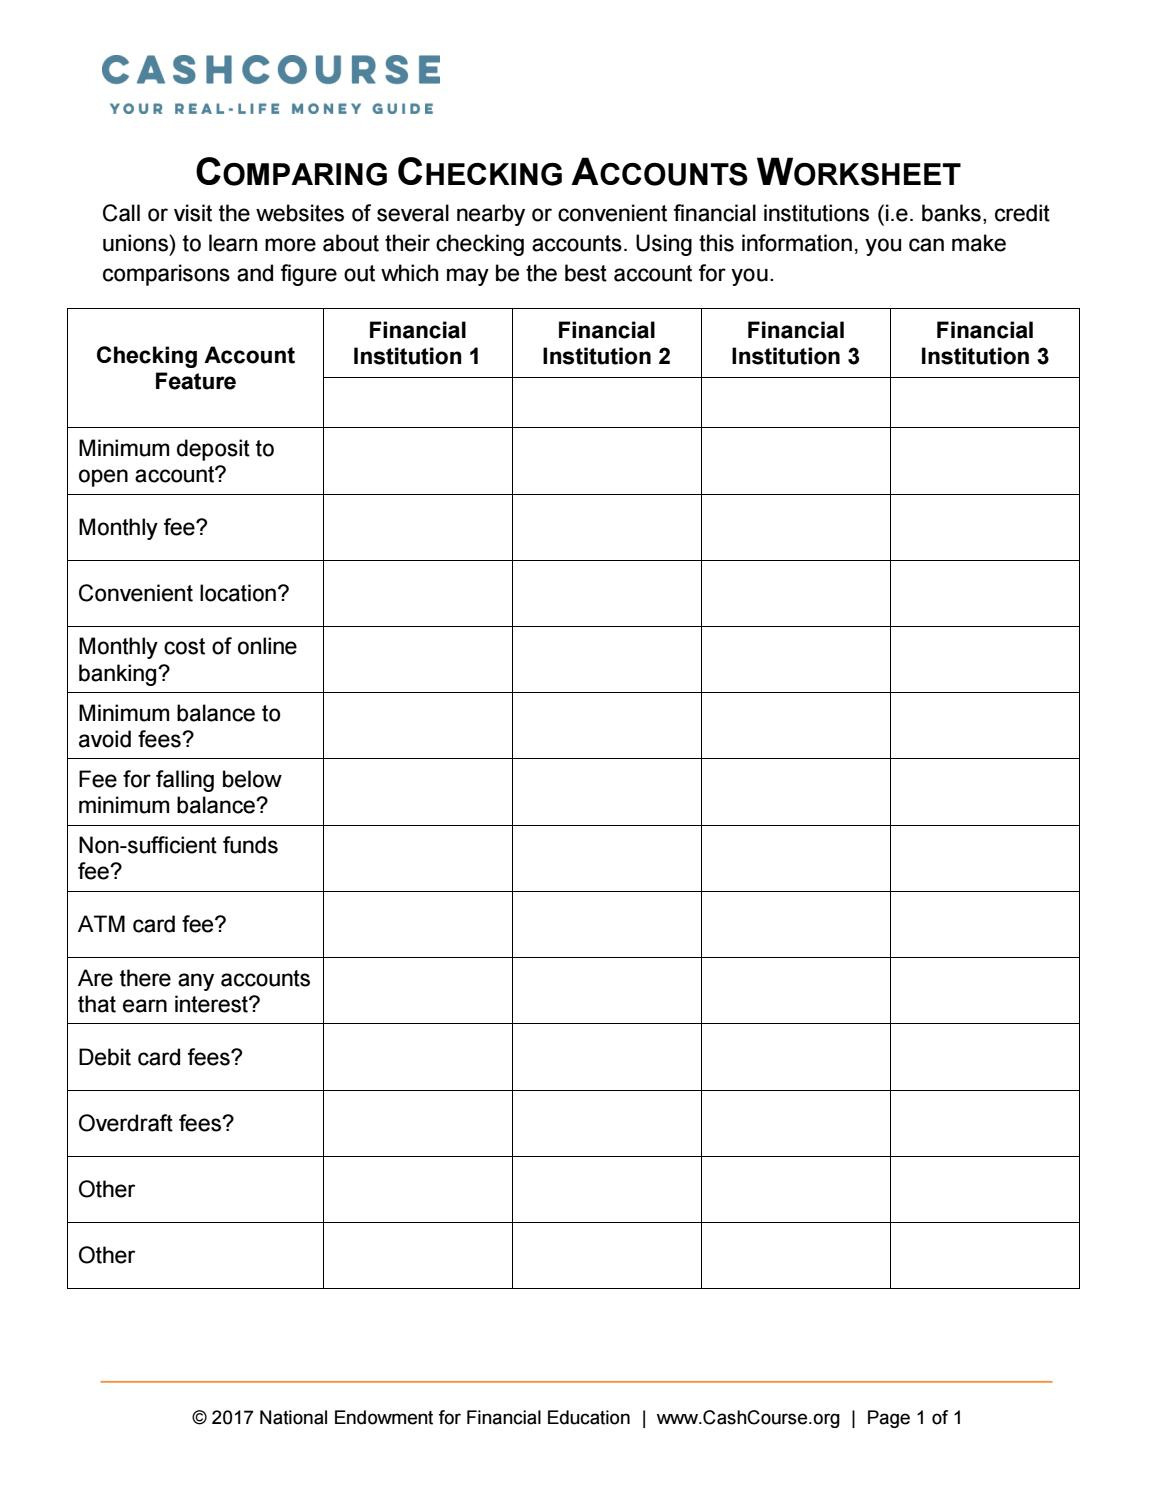
Here's how I actually compare checking accounts when I need to
The whole process starts with a spreadsheet, plain and simple. You can buy one at a finance site, make your own in Excel or Google Sheets, or just find one online and modify it. The Comparing Checking Accounts Worksheet is really just a structured way to lay out fees, interest rates, minimum balances, and required documents side by side so you're not trying to hold everything in your head. I keep a running file with about twenty rows and columns for monthly maintenance fee, overdraft fee, ATM fees, direct deposit requirements, minimum balance to avoid the monthly charge, APY if it's a high-yield account, and whether there's a paper statement fee. The last column is always "red flags" where I dump anything weird, like a $12 overdraft fee when the market rate is $35.
Comparing Checking Accounts Worksheet template walk-through
Set it up with each bank as a row. Columns go down the left: bank name, account type (basic checking, premium, student), monthly fee, fee waiver conditions, overdraft protection setup, interest rate, ATM access, mobile deposit limits, and foreign transaction fees. Fill each cell before you move to the next bank. Don't skim one and then come back later. You'll forget the details. One trick that actually matters: include the effective annual cost. Some banks advertise zero monthly fees but charge $5 per out-of-network ATM withdrawal and $2 for paper statements. If you use ATMs twice a month and get statements, that's $120 a year hidden in plain sight. I used to miss that until I built the annual cost column into my worksheet, multiplying monthly fees by 12 and adding per-transaction estimates. Here's a realistic edge case I ran into last year. A credit union was offering a lower stated fee than a national bank, but they had a tiered structure based on average daily balance. The worksheet looked better on paper until I plugged in my actual month-to-month balance swings. My average dipped below the threshold in March because of a large one-time payment, which triggered the fee that month. I ended up switching to an account with a higher flat fee but no balance requirement, and I saved about $47 annually after I accounted for the variance. The lesson: test the fee waiver with your real numbers, not your best-case scenario.
If you want a downloadable version, search for the template on banking comparison sites or use the one I keep updated on my personal site. Most of them are fine, but I recommend modifying any you find because the default columns rarely include the annual effective cost breakdown, which is the column that actually changes your decision.
Get the Full Details

What people consistently get wrong about this comparison
The first mistake is comparing nominal fees without adjusting for usage patterns. A $12 monthly fee sounds worse than a $5 monthly fee, but if the $5 account requires a $1,500 minimum balance to waive it and you rarely keep that much cash, the $12 account might end up cheaper overall. I've seen people pick the lowest advertised fee and then pay the minimum-balance penalty for three months straight. The second mistake is ignoring the interest rate difference. When rates are low it feels trivial, but on accounts with higher balances the APY gap compounds over the year. If one account pays 0.01% APY and another pays 4.25% APY and you keep $5,000 in it, that's roughly $210 in interest income per year, not including the fee savings from the higher-tier account. It's not dramatic in absolute terms for small balances, but it dominates the comparison when you're maintaining a real operating account. A third nuance that trips people up: fee structures change without much public notice. Banks announce new overdraft policies during open enrollment seasons, and the rates shift quietly in fine print. I had a client who switched because the worksheet showed a $3 overdraft fee versus the competitor's $35, and six months later the bank changed their policy to a flat $25 per incident regardless of balance. If you're doing this comparison annually, update the worksheet with current terms. The earlier numbers are only valid for the moment you filled them in.
Don't rely solely on the worksheet either. It's a decision aid, not a substitute for calling the bank. Sometimes the online info is outdated or omits a fee category. I always call customer support and ask specifically about hidden or conditional fees. They'll confirm whether the fee waiver requires direct deposit, autopay, or a minimum number of purchases. Write the answer in the worksheet right after the call so you have a timestamped record.
When the worksheet approach falls apart
There are cases where this method doesn't help. If you're comparing credit union accounts against large national banks, the fee structures are often incomparable because the credit union may not charge monthly fees at all and instead makes money on loan pricing. The worksheet will show a gap that looks like a clear win for the credit union, but you might be losing money elsewhere through higher insurance premiums or slower service. In those situations, factor in service quality and processing speed rather than just fees. Another scenario where the comparison breaks down is when you need a business account with merchant services, payroll integration, or multi-user access. The consumer worksheet doesn't capture those capabilities. Use a separate checklist for business features and run the fee comparison only after you've confirmed the account supports your operational needs. Combining the two on a single sheet muddies the decision.

Download and usage notes
I keep a clean copy of the Comparing Checking Accounts Worksheet available for anyone who wants it. It includes pre-built columns for the standard fees, the annual effective cost calculation, and a red-flags column for hidden conditions. You can also export it to CSV if you want to merge multiple bank comparisons in one master file. I update it whenever banks change fee structures, which happens more often than people realize. If you download it, fill it out with your actual spending habits, not idealized ones. Plug in your real monthly balance range, your typical transaction count, and the ATMs you actually use. The numbers you enter matter more than the template itself. A poorly filled worksheet gives a worse answer than no worksheet at all.
Quick practical summary
Build or use a worksheet, include the annual effective cost column, test fee waivers against your real balance patterns, call the bank to verify current terms, and remember that the lowest advertised fee is rarely the cheapest option once you factor in your actual usage. That's the part most people skip, and it's the part that determines whether you save money or just save time initially and lose it later.