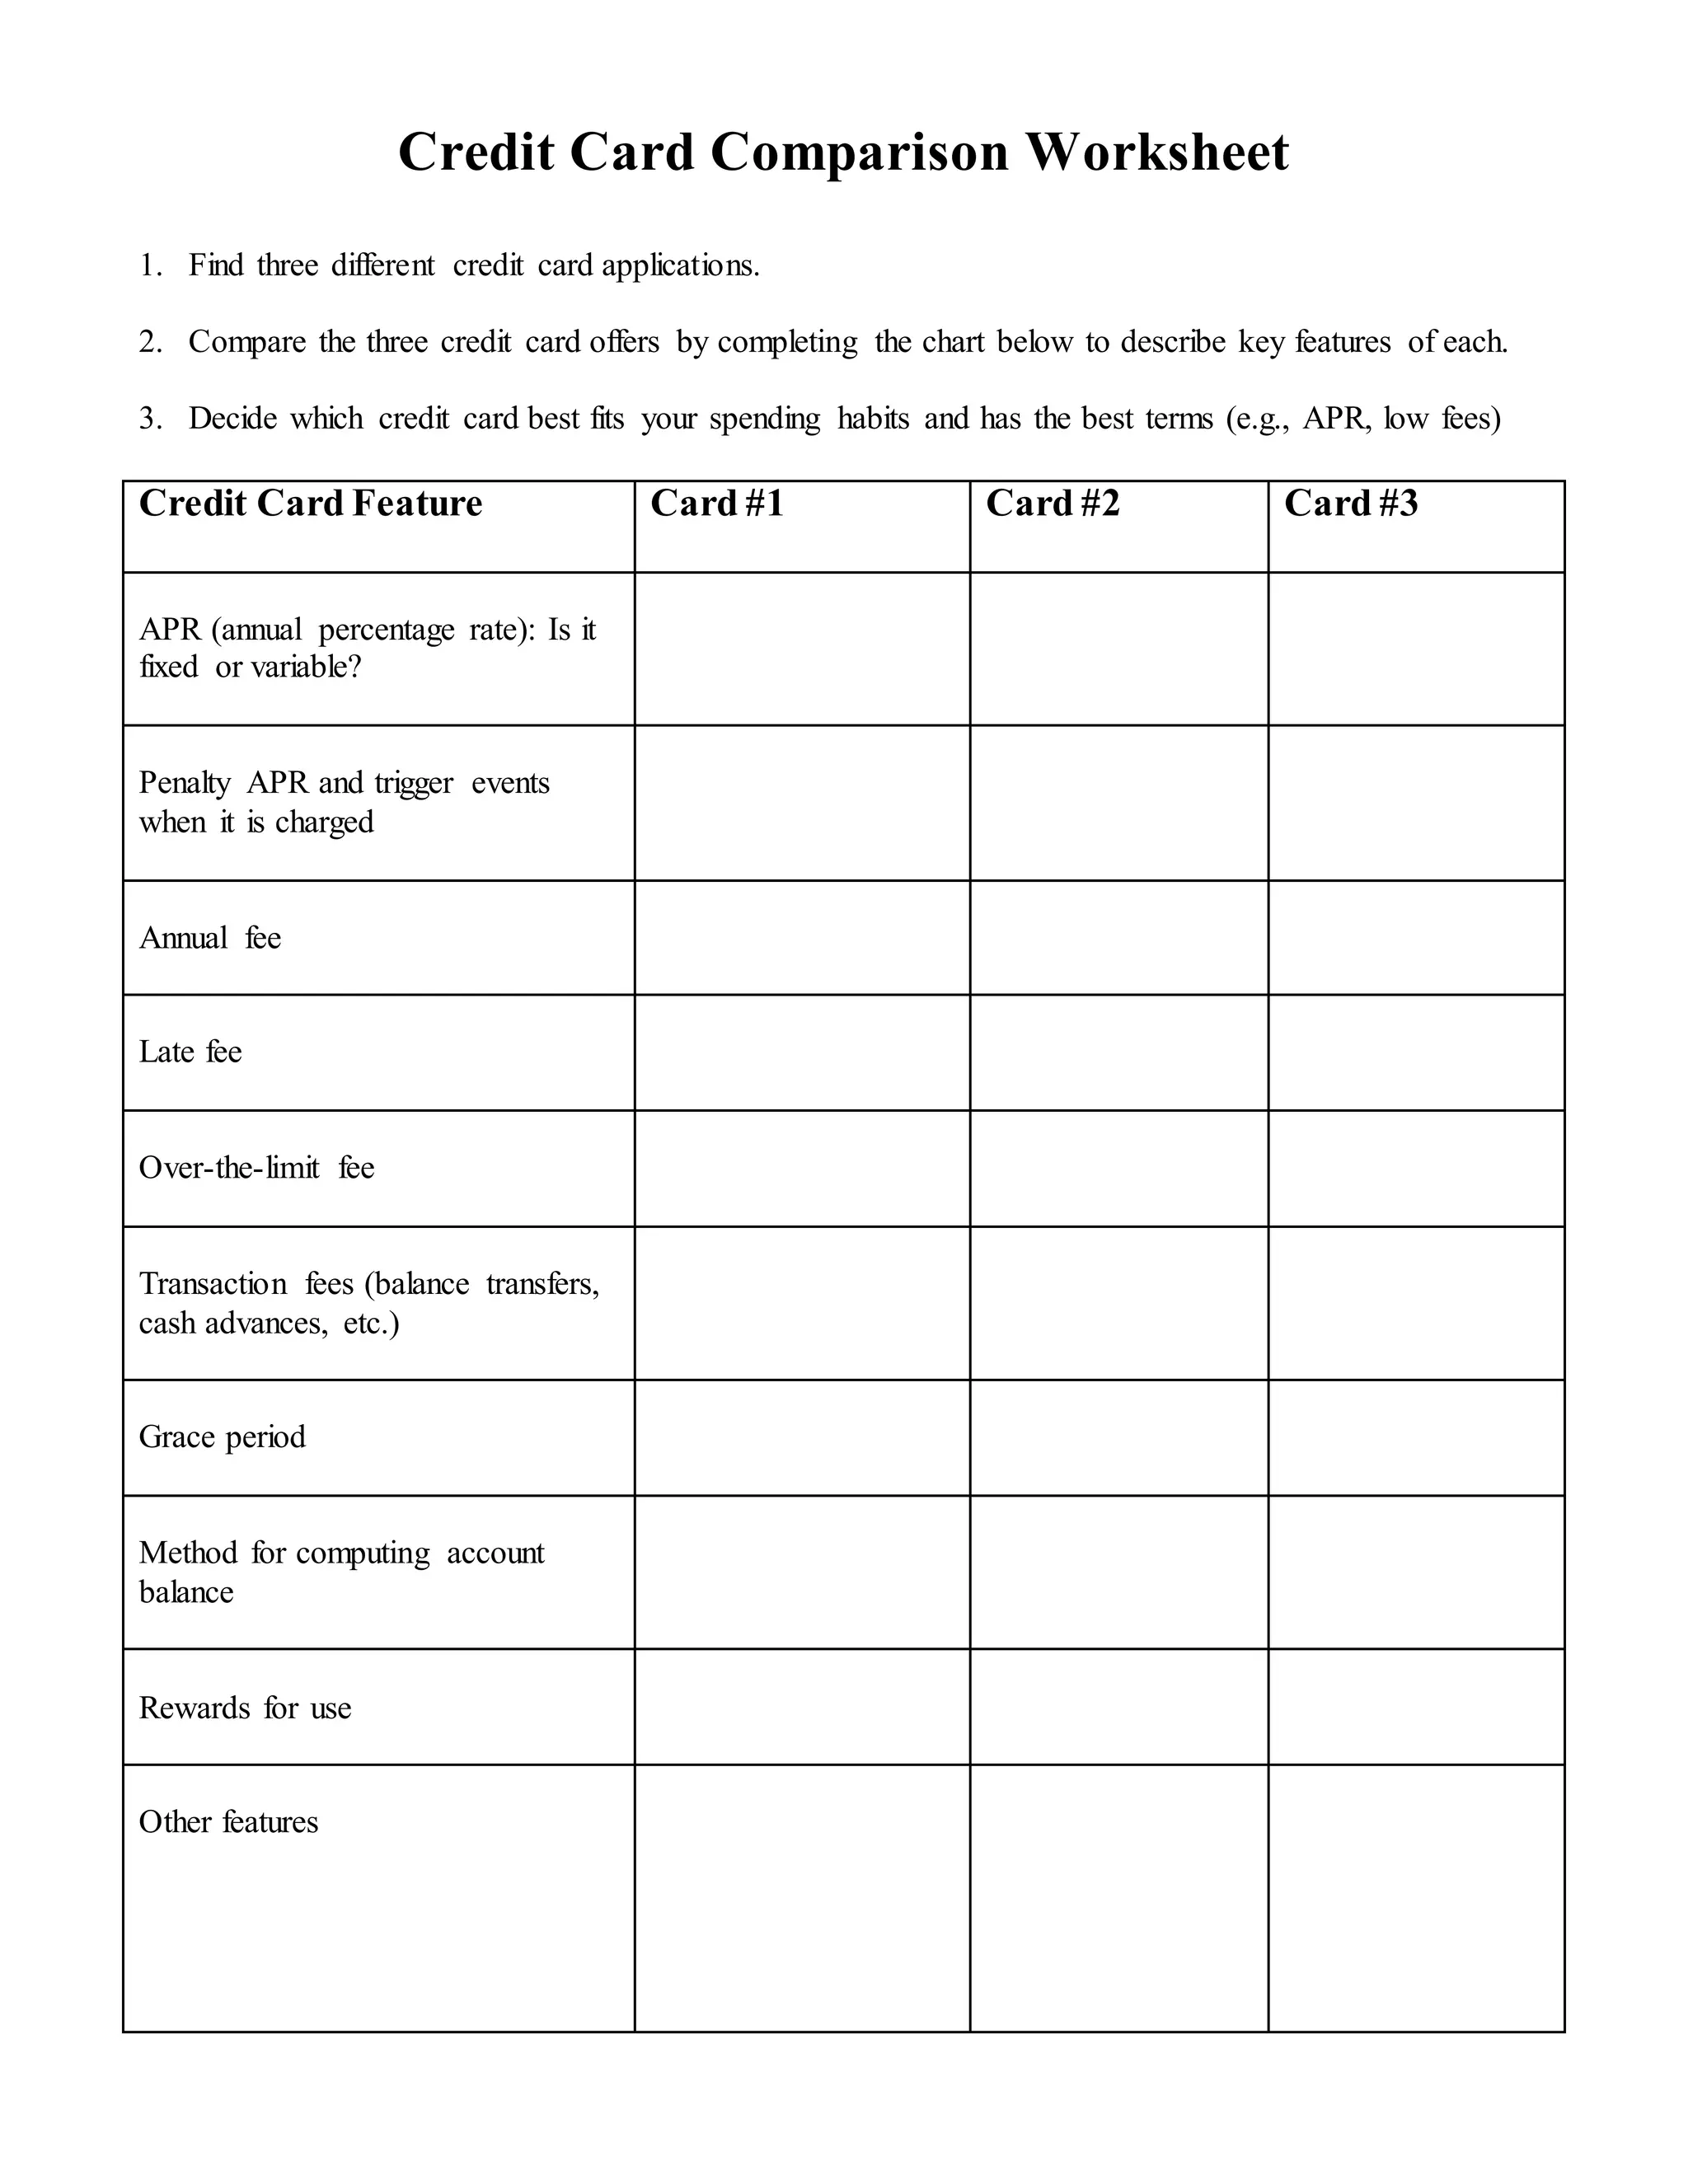
Why I Keep Making My Own Credit Card Comparison Sheets
I have been comparing credit cards for roughly fourteen years, mostly through spreadsheets I built myself because every third-party tool I found either buried the fine print or charged $20 a month to show me APR differences. The core problem is that credit card offers change constantly, and no single site keeps them all current. That is why a solid Comparing Credit Cards Worksheet remains the only way I trust to evaluate which card actually suits a given spending profile. The approach is not complicated, but the devil is in the details. You are not just comparing reward percentages. You are modeling actual annual spend across category buckets, plugging in promotional APR windows, annual fees, balance transfer costs, and foreign transaction fees, then projecting the result over a twelve-month period. A lot of people skip straight to the sign-up bonus and ignore the ongoing math, which gets them stuck with a card that looks great on the landing page but performs worse than a basic cash-back card once the promotion expires.
How to Build a Comparing Credit Cards Worksheet
Start with a clean spreadsheet. Set up column headers for: Card Name, Annual Fee, Ongoing Cash Back or Points Rate by Category, Sign-Up Bonus Value, Sign-Up Bonus Spend Requirement, Promotional APR Window, Standard APR, Balance Transfer Fee, Foreign Transaction Fee, and Effective Annual Value. That last column is where most people drop the ball, so I put it in first to remind myself it matters. Under each card, break down your estimated monthly spend by category. Grocery, dining, gas, travel, utilities, subscriptions, everything else. Weight these based on your actual previous statement averages, not your hopes. I learned this the hard way when I assumed my dining spend would stay elevated after I started cooking more at home. My original spreadsheet projected an extra $140 a year in rewards that never materialized. The fix was pulling my actual bank statements for the prior twelve months and using those as the baseline instead of estimates. Calculate the sign-up bonus value first, because that is usually the biggest single number. If a card requires $3,000 in spend over three months to unlock 60,000 points, and you know those points are worth about 1.2 cents each when transferred to a travel partner, the bonus is worth roughly $720. Factor in whether you would have spent that money anyway. If you were already going to hit $3,000 in three months on existing purchases, the bonus is free money. If you were only going to spend $800, you are manufacturing spend to chase a number, and that rarely ends well.
Next, run the ongoing reward calculation. Multiply each category spend by the corresponding reward rate. Sum them up. Subtract the annual fee. Add any category spending caps into the calculation. Some cards offer five percent back on rotating categories up to a quarterly limit, which sounds attractive until you realize you have to actively enroll each quarter and the cap is only $1,500. If your actual quarterly spend in those categories is $400, the rotation feature is mostly irrelevant. For cards with promotional APR, calculate the interest savings if you plan to carry a balance. A 0% APR for twelve months on a $2,000 balance at a standard 24.99% APR saves you roughly $250 in interest over that year. But balance transfer fees are typically five percent of the transferred amount, which eats into that savings. On $2,000 that is $100. So your real savings drop to about $150. Most people forget to subtract the transfer fee from the interest savings and overestimate the benefit by sixty percent. The effective annual value column ties everything together. It is the sum of your sign-up bonus (amortized if you spread it across years), your ongoing annual rewards, minus your annual fee, minus any balance transfer or foreign transaction costs you expect to incur. This single number lets you rank cards objectively instead of getting distracted by whichever one has the flashiest landing page.
Get the Full Details
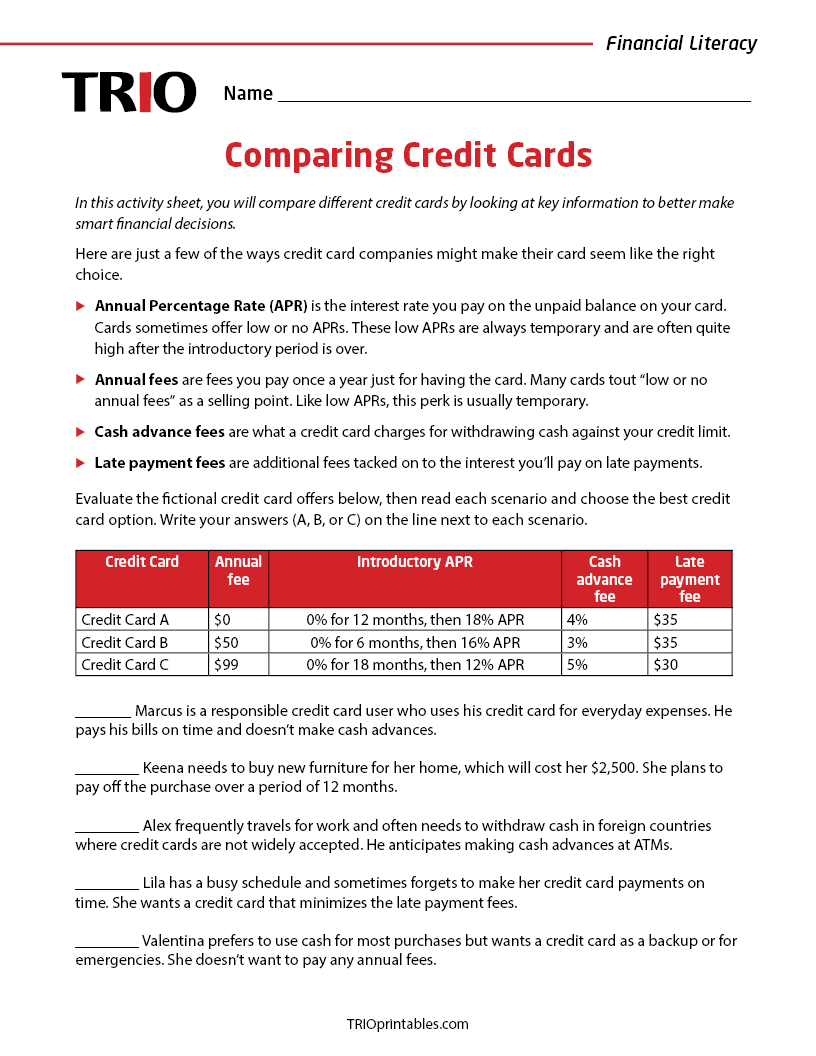
Here is a practical example. I compared three cards last year: one with a $95 annual fee offering 2% flat cash back, one with no annual fee but a complex rotating categories structure, and one with a $0 annual fee and 1.5% flat. The rotating card looked best on paper because it offered 5% on dining and groceries, but my actual dining and grocery spend only totaled about $1,200 per quarter. After capping out the rotation and applying the 2% card to the remaining spend, the flat 2% card actually edged out the rotating card by about $38 annually once I factored in the time cost of tracking categories and the minor risk of missing a rotation enrollment window.
Edge Cases That Break the Simple Model
Not every card fits neatly into a spreadsheet cell. I ran into a problem last spring with a card that offered elevated rewards for the first eighteen months, then dropped to a lower rate permanently. The standard twelve-month projection made the card look like the clear winner, but once I extended the model to twenty-four months, it fell below two alternatives. The lesson is to project at least two years into the future for any card with a limited-time elevated rate. Otherwise you are optimizing for a snapshot that does not reflect the actual lifecycle of the product. Another edge case involves annual fee waivers. Some cards waive the fee for the first year, then charge it starting in year two. If your worksheet does not account for the year-one waiver separately, you will miscalculate the long-term value by exactly one annual fee amount. This happens constantly with beginner-friendly cards, and it is easy to miss unless you explicitly model the first-year versus subsequent-year costs as separate line items. Limits also matter. A card promising high rewards on travel is useless if your actual travel spend is capped at $500 per billing cycle and you regularly exceed that. I once recommended a card to someone based on a spreadsheet that showed $400 in annual rewards, but the person maxed out the travel category cap within two months and was earning only 1% on everything above that. The real annual value was closer to $180. Always check the category limits before the reward projection.
What This Method Cannot Do
A Comparing Credit Cards Worksheet will not tell you whether a card issuer is stable, whether your credit score qualifies you for the best offers, or whether the sign-up bonus terms have changed since you last checked. Issuers update their fine print frequently, sometimes without public notice. I have seen several cases where a bonus requirement increased from $2,000 to $3,000 overnight, which completely invalidates a projection built on the old terms. Always verify the current offer on the issuer's official page before trusting your spreadsheet numbers. The worksheet also cannot account for behavioral changes. If you switch to a new card and start spending more because you feel rewarded, your projections become self-defeating. The math assumes a fixed spending pattern, which is a generous assumption for anyone who has ever fallen for a big sign-up bonus. Keep your spend estimates honest or the entire exercise is pointless. There is also the question of card churning. A spreadsheet can model the math of opening multiple cards for bonuses, but it cannot accurately predict approval odds, hard inquiry impacts, or issuers' tendency to close accounts they suspect of abuse. Those variables exist outside the model. If you are relying on churning to maximize value, treat the worksheet as one input among many, not the final authority.

For people who only compare two or three cards a year, a full spreadsheet might feel like overkill. In that case, a simplified version works: list the annual fee, the effective reward rate on your top two spending categories, the sign-up bonus net of any fee, and the standard APR. If you carry a balance, the APR line is the most important one. A card that saves you $50 in rewards but charges eight percentage points higher APR will lose every time. The best approach is to build the Comparing Credit Cards Worksheet once, fill it with your real spending data, and reuse it whenever you evaluate a new offer. It takes about twenty minutes to set up properly, then another five minutes to update each time you add a card to compare. That investment pays off the first time you avoid picking a card that looks good on the surface but underperforms in practice.