Understanding Comparison Rate Calculators in Practice
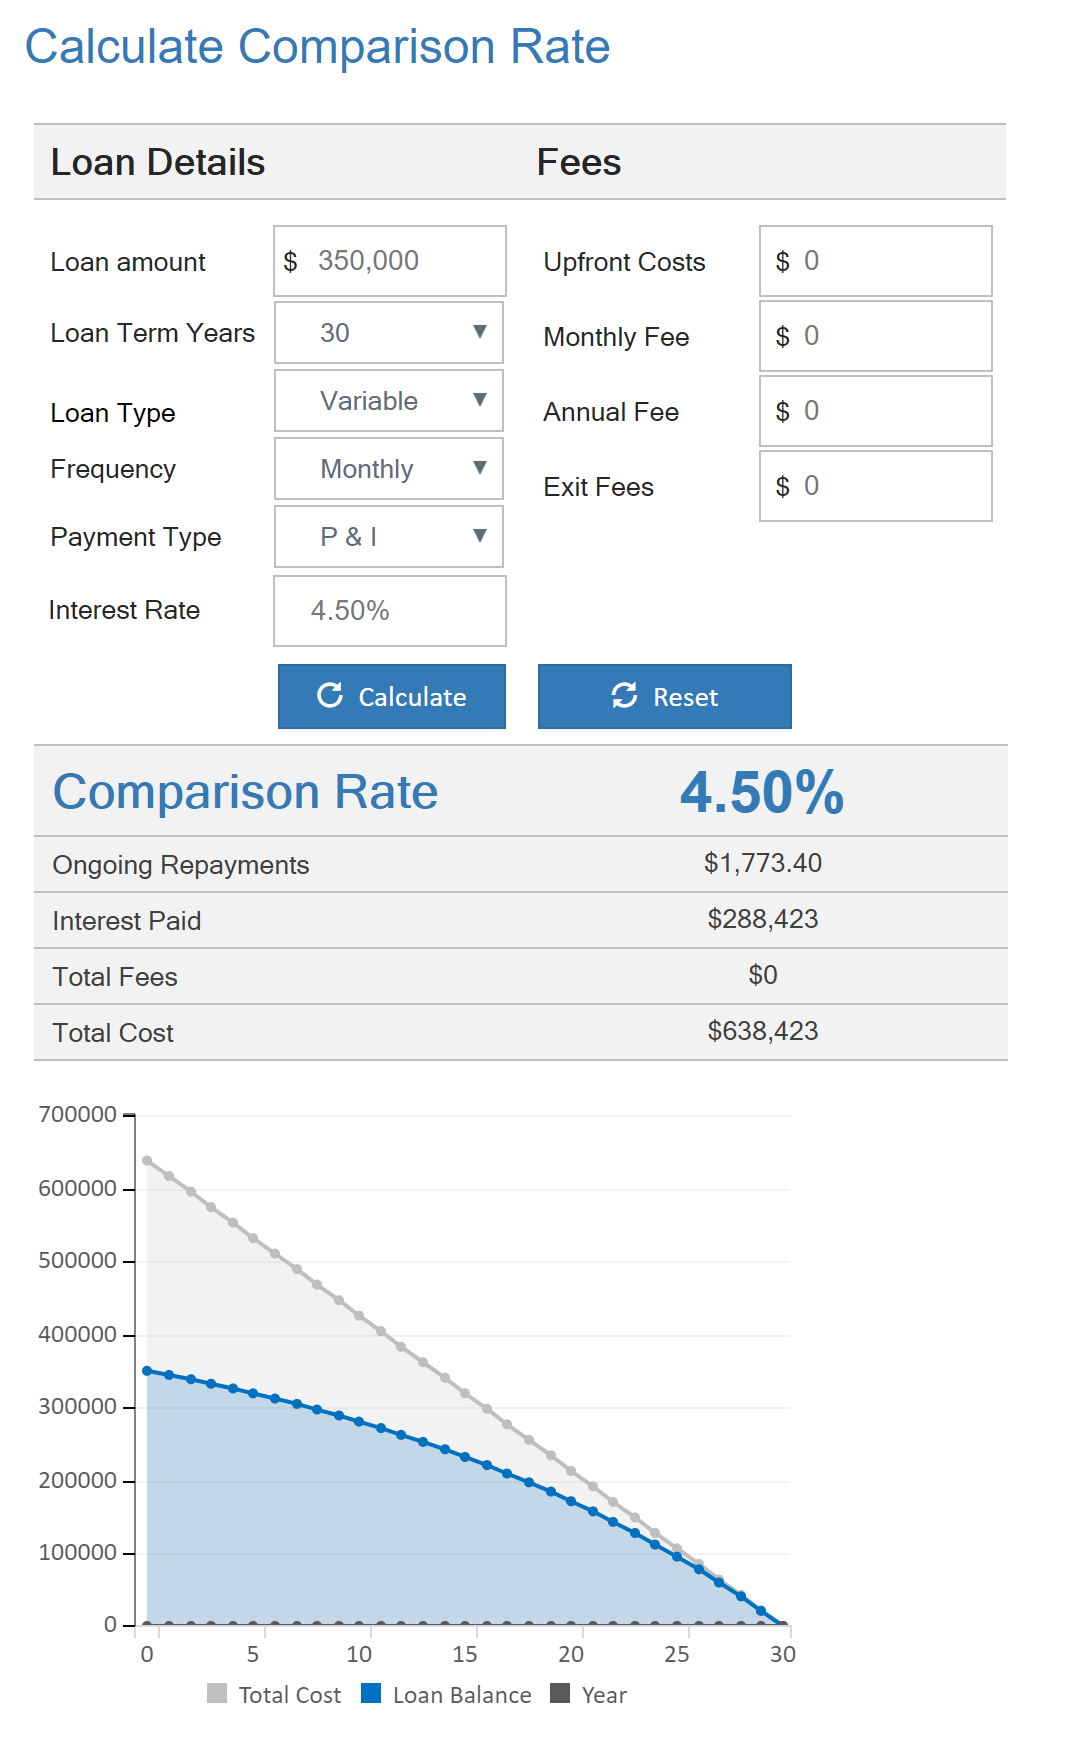
A comparison rate calculator takes a loan's advertised interest rate and factors in most of the associated fees and charges to produce a single percentage that represents the true annual cost of borrowing. This is not the same as the nominal rate. In Australia, for instance, lenders are required by law to display a comparison rate on most consumer credit products. The calculation itself solves for an internal rate of return across the full loan term, combining the nominal rate with upfront fees, ongoing charges, and any other mandatory costs into one composite figure. The basic mechanics are straightforward enough, but the devil is in how fees get structured and which ones actually make it into the calculation. A $3,000 establishment fee on a $200,000 loan over 25 years will push the comparison rate noticeably higher than the headline rate. The relationship is not linear because the fee gets annualized differently depending on the loan amount and term. Shorter terms concentrate that fee impact more aggressively.
How the Comparison Rate Calculator Actually Works
The calculation requires solving for the rate that makes the present value of all repayments equal to the net amount the borrower actually receives after deducting eligible fees from the loan principal. This is fundamentally an iterative numerical problem, not a closed-form equation. You set up the cash flow: the borrower gets the loan amount minus upfront fees, then makes regular repayments at the stated nominal rate, plus any ongoing annual fees, until the balance is paid down to zero. Most implementations use a Newton-Raphson or bisection method to converge on the rate. A well-tuned solver typically hits convergence in five to eight iterations when starting from a reasonable initial guess. The main inputs you need are the loan amount, the nominal interest rate, the loan term, the repayment frequency, and a complete list of fees with their timing. Omitting even a small quarterly account-keeping fee can shift the result by a few basis points over a long term. I spent a few weeks building one of these from scratch for a mortgage brokerage tool, and the first version had a bug where the solver was treating the comparison rate as a monthly figure instead of annual. It returned numbers that were exactly twelve times too small, which is the kind of mistake that flies under the radar until someone actually compares two loans side by side and the results look wrong. Fixed that by normalizing everything to an effective annual rate before displaying.
What the Formula Actually Captures
The standard comparison rate formula in Australia, which most calculators follow, is: P = [R / (1 + r)^t] Where P is the net amount financed after deducting included fees, R represents each repayment including fee portions, r is the periodic comparison rate, and t is the period number. The formula essentially solves for r. A comparison rate calculator automates this by iterating across possible values of r until the equation balances.
Get the Full Details
The key insight most people miss is that the comparison rate only applies to the specific loan amount and term used in the calculation. If you take a smaller amount or pay the loan off early, your actual cost diverges from what the comparison rate suggests. The comparison rate is a standardized snapshot, not a personalized cost projection.
A Practical Edge Case That Cost Me Time
One loan product I worked with had a large upfront establishment fee but also offered a discretionary redraw facility. The comparison rate calculation did not account for redraw at all because it is not a mandatory feature. A borrower who planned to use redraw regularly would effectively have a lower cost of funds than the comparison rate indicated, since they could park surplus payments and pull them back when needed. The comparison rate treated every dollar borrowed as irrecoverable for the full term. The workaround was straightforward: I built a secondary field into the calculator that let users optionally input estimated redraw usage as a percentage of the loan, then adjusted the effective cost display accordingly. This made it clear to users that the comparison rate was a conservative floor, not necessarily the ceiling. The formal comparison rate stayed unchanged for regulatory compliance, but the adjusted figure gave a more realistic picture for certain borrower profiles.
Common Pitfalls When Using These Calculators
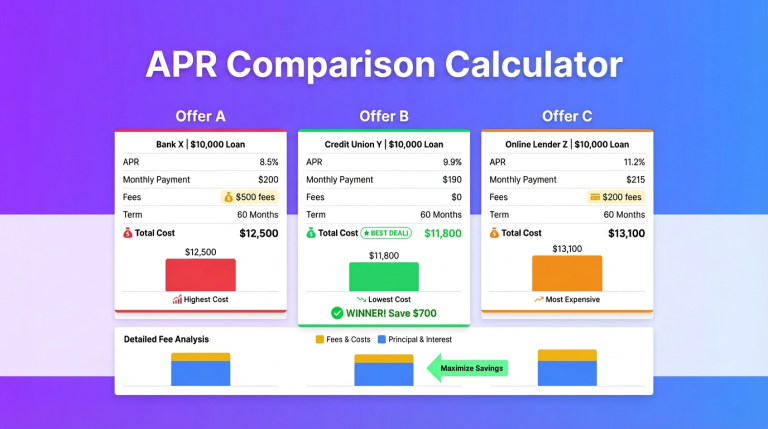
The biggest issue is that not all fees are included in the comparison rate. Lenders can often find legitimate ways to structure costs outside the comparison rate calculation. Service fees, package discounts, and occasional transaction charges may not feed into the figure at all. A loan with a lower comparison rate might still end up costing more if it has hidden fees that the calculator ignores. Another problem is the assumption of equal repayments throughout the entire term. Many modern loans have interest-only periods followed by a principal and interest phase. A proper comparison rate calculator needs to handle variable repayment schedules, but many simpler implementations assume level repayments from day one. This creates a meaningful distortion for interest-only products where the early cash flows are materially different. Loan amounts below $50,000 tend to produce disproportionately high comparison rates because the fixed fees eat up a larger share of the principal. A $500 establishment fee on a $100,000 loan raises the comparison rate by roughly 0.1 to 0.2 percentage points. The same $500 fee on a $30,000 loan could add 0.5 to 0.7 percentage points. This is why comparison rates are most useful for medium-to-large loan amounts, typically above $100,000.
When Comparison Rates Mislead
Balloon repayment structures are another area where comparison rates can be misleading. A loan with a 30 to 40 percent balloon at the end of the term will show a lower comparison rate than an identical loan with equal repayments throughout, because the regular payments are smaller. The borrower still owes the balloon amount, but the comparison rate calculation spreads that final obligation across the periodic repayment stream in a way that understates the real burden if the borrower cannot refinance the balloon. Offset accounts present a similar issue. A loan with a full offset account effectively reduces the interest cost by allowing the borrower to earn the loan rate on their deposit balance rather than a savings rate. The comparison rate does not factor in this benefit because offset availability depends on individual behavior. Two loans with identical comparison rates could have very different actual costs if one has a robust offset facility and the other does not.
Building or Choosing a Reliable Tool
If you are building a Comparison Rate Calculator, the main things to watch are accurate fee classification, proper handling of different repayment structures, and correct year-day conventions. Most jurisdictions use a 365-day year, but some calculations use 365.25 to account for leap years. This matters less for consumer-facing displays but affects precision when you are back-testing against regulatory benchmark results. Validation is critical. Run your calculator against known regulatory test cases whenever possible. Australian lenders must submit their comparison rates to APRA for audit, and those published rates can serve as a verification baseline. If your calculator produces a result that differs from a published rate by more than two basis points for the same product, something in your fee inclusion logic or solver is off. For anyone using these tools rather than building them, treat the comparison rate as one data point among several, not the final answer. Check the nominal rate, list every fee you can find in the product disclosure statement, and run a quick manual sanity check. The comparison rate will almost always be higher than the nominal rate unless there is a significant discount or concession built in. If you see a comparison rate lower than the advertised interest rate, something unusual is happening, and you should investigate before committing.