Buying gold is less about the metal and more about the process around it
I spent years handling gold transactions at a small pawn and bullion shop before moving into pure investment advisory. The guys who do the best tend to be the ones who don't treat it like a mystery subject. Most of the confusion comes from people not understanding what they are actually paying for. Here is how it works in practice. The first decision is what form of gold you are buying. Bars and coins dominate the market, but they serve different purposes. A bar is straightforward—it is melted gold in a specific shape with a recognized assay mark. Coins are the same metal but with a face value, mint mark, and sometimes historical or numismatic premium layered on top. If you are buying purely as an investment, bars are simpler. If you want liquidity across multiple markets and easier resale in smaller denominations, coins make more sense. I always tell people to buy what they are comfortable selling later, because that comfort level matters more than you would expect when market conditions shift.
Complete Guide To Buying Gold
Spot price vs. premium. The spot price is the current market rate for one troy ounce of pure gold. Every dealer adds a premium on top of that to cover refining, minting, distribution, and profit. Premiums vary wildly. A 100 oz bar might carry a premium of $3 to $8 per ounce over spot. A 1 oz gold coin from the Perth Mint or the American Eagle could run $40 to $80 over spot depending on market volatility and demand. During the 2020 pandemic rush, I watched 1 oz coin premiums spike to over $200. That is not normal, but it is real, and it is why timing your purchase matters more than most people realize. Where to buy matters more than you think. Major mints like the Royal Canadian Mint, Perth Mint, and US Mint sell directly, but their product availability is limited and they rarely sell retail at spot. Most people end up buying through authorized dealers like APMEX, JM Bullion, or local coin shops. Online retailers are fine if you stick to established names with verifiable track records. Local dealers let you handle the product before it leaves the counter. That inspection step is worth the hassle of driving somewhere. I have seen too many people order online, receive the shipment, and only realize something felt off after the window for a hassle-free return had closed. Purity and verification. Investment-grade gold is typically 99.5% pure or higher. Standard bars are 99.99%. American Eagles are 91.6% gold with copper and silver making up the rest, which actually makes them more durable for handling. The purity you choose depends on your use case. For long-term storage, 99.99% is fine. If you plan to buy and sell physically on a regular basis, 22k coins like the British Sovereign or South African Krugerrand are worth considering. They trade at lower premiums relative to their gold content and are universally recognized, which makes selling faster in most markets.
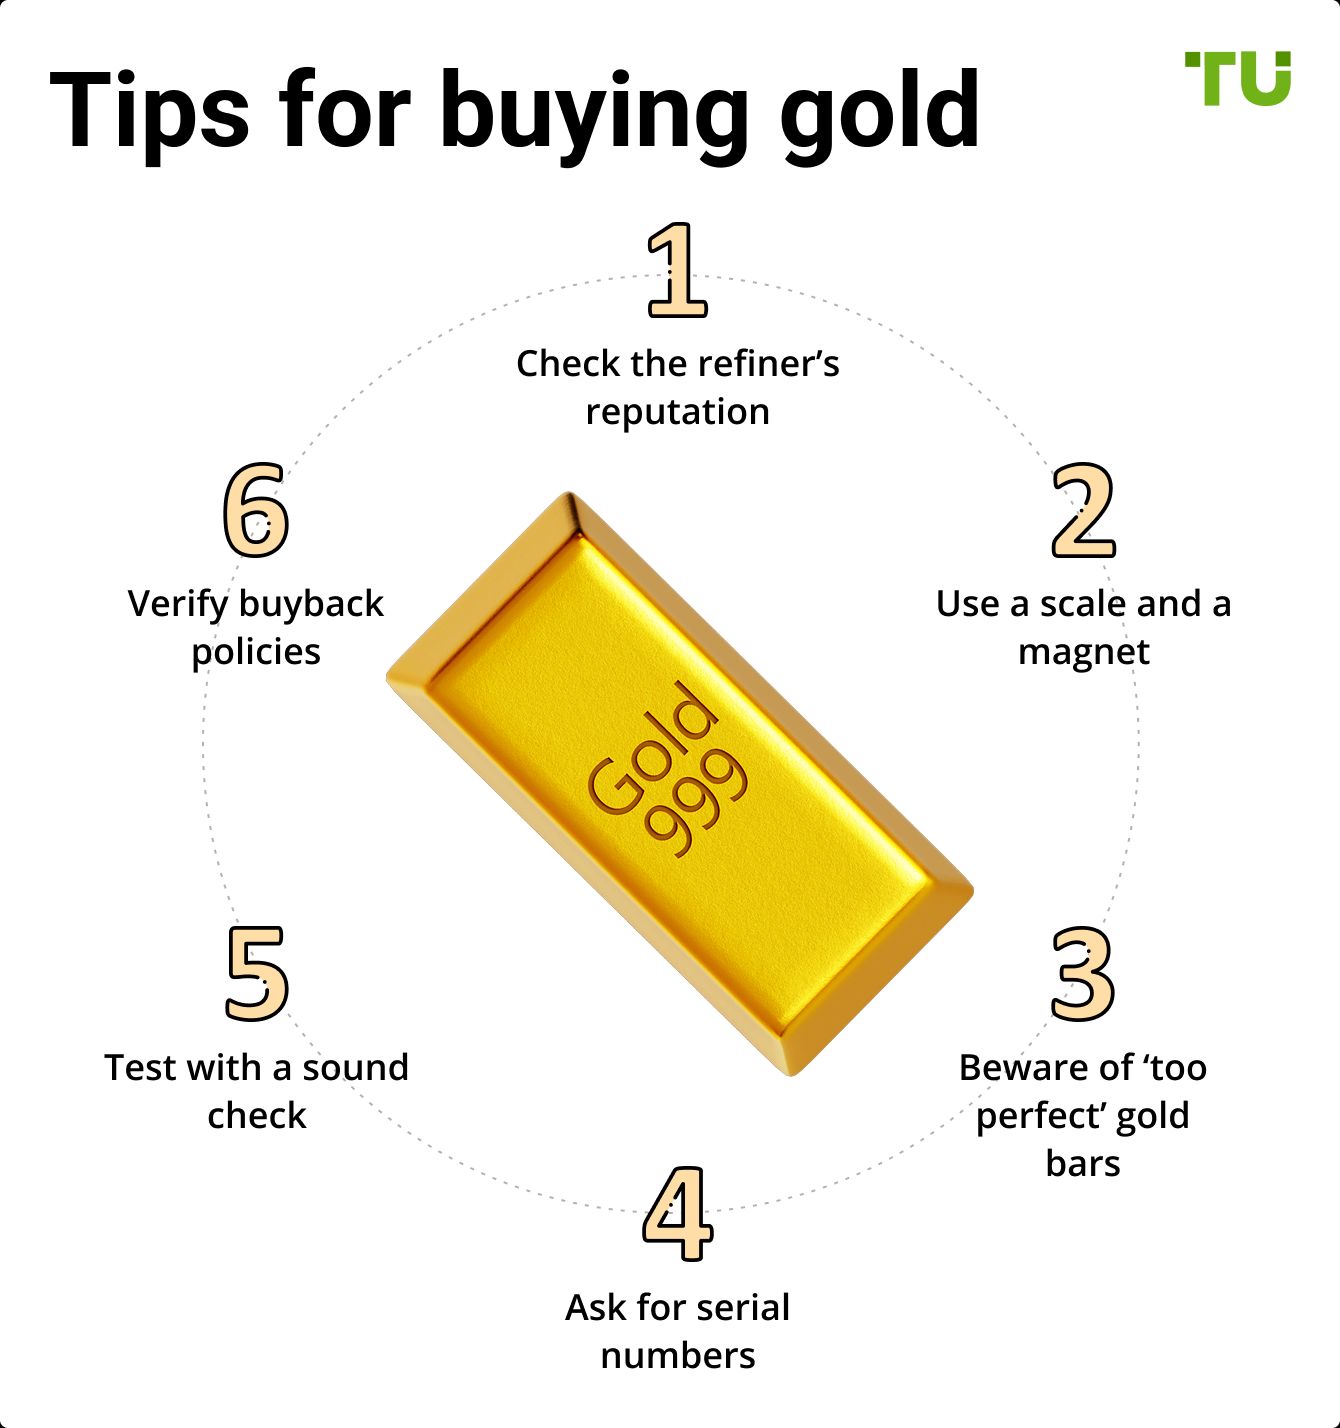
Tax considerations. In the United States, collectible coins like the American Gold Eagle and Gold Buffalo are considered legal tender and have specific tax treatment. IRS Schedule D applies capital gains rules, and the holding period determines whether you pay short-term or long-term rates. Bullion bars and coins from non-US mints may fall under different rules. Some states exempt precious metals from sales tax, but not all. If you are buying significant quantities, a quick call to a CPA who understands precious metals is cheaper than figuring out a mistake after the fact. I had a client who bought $15,000 in gold bars without checking his state's sales tax rules and got hit with an unexpected charge he did not budget for. Storage is not optional. You can keep gold at home, but that introduces risk. Home safes are rated for fire and water, not for a determined burglar. Safe deposit boxes at banks are common, but they are not insured by the government. If the bank has an issue or your box gets locked out, you are dealing with bureaucratic delays. Some people use allocated storage through their dealer or a third-party vaulting company. This adds a cost but removes the anxiety of tracking down your metal when you need to sell. The average cost for allocated storage runs between $0.50 and $2 per ounce per month, depending on the provider and the quantity you hold. I ran into a specific issue a few years back that illustrates why verification is not just a suggestion. A customer brought in a stack of Canadian Maple Leafs that looked correct at first glance. The colors matched, the weight was right, the reeding on the edges looked proper. But the magnet test—a simple neodymium magnet you can pick up for ten dollars—revealed the truth. The coins were slightly magnetic, which genuine gold and silver alloys are not. They were tungsten-core fakes, a problem that has become increasingly common. Tungsten is dense enough to fool a scale and non-magnetic in its pure form, but alloyed differently it can show weakness. I walked the guy through the process of getting them tested with a precise electronic checker and a pH solution dip. Both confirmed they were counterfeit. He never would have known without those two simple tests, and he would have lost nearly two thousand dollars if he had sold them as real.
Get the Full Details
Selling is where most people lose money. Buying at spot plus premium and selling back at spot minus a dealer spread is the basic math. That spread is how dealers make money, and it is unavoidable. The difference between what you pay and what you get back when you sell is your transaction cost. For bars, the buy-sell spread is usually tighter—maybe $5 to $15 per ounce total. For coins, it can be $30 to $60 per ounce depending on the type and market conditions. I advise people to think of gold as a multi-year hold, not a short-term trade. Every time you buy and sell, you are paying that spread. Over five or ten years, gold can easily overcome those costs. Over months, it usually cannot. One counter-intuitive point that confuses people: having your gold appraised does not mean you can sell it for that appraised value. Appraisals are for insurance purposes, not market pricing. An appraiser might value a rare coin at three times its melt value because of its rarity. But unless you find a buyer who agrees with that rarity assessment, you are selling the gold content, not the collector premium. The exception is genuine numismatic coins with certified grading from PCGS or NGC. Those carry their own market, but they require knowledge to trade profitably, and that knowledge is not cheap to acquire. The biggest mistake I see is buying based on fear rather than a plan. Gold is a store of value and a portfolio hedge, not a get-rich mechanism. It does not pay dividends. It does not grow. It sits there and preserves purchasing power over decades, sometimes gaining, sometimes staying flat. If you are looking for growth, you are buying the wrong asset. If you are looking to diversify and protect a portion of your wealth from currency debasement or systemic risk, then gold makes sense. A common allocation range is 5% to 15% of a portfolio, though nobody likes to give you a definitive answer on that number because it depends on your entire financial picture.
Another thing people underestimate is the psychological friction of owning physical gold. You buy it, you store it, and then for years you do nothing with it. The temptation to sell during a dip or buy more during a run-up is real, and acting on it without a clear rule set turns gold into just another speculative position. I suggest writing down your buying and selling criteria before you make the first purchase. Decide how much you will hold, under what conditions you will add to or reduce your position, and what your target timeline is. Then stick to it. The people who end up happiest with their gold purchases are the ones who treated it like infrastructure, not like a stock to day trade. If you are new to this, start small. Buy one ounce. Handle it. Store it. Sell it if you need to. The process teaches you more than any article or video ever will. By the time you have completed a full cycle of buying, holding, and selling, you will know exactly what works for you and what does not. Everything else is just noise.