The formula and the thing nobody tells you about it
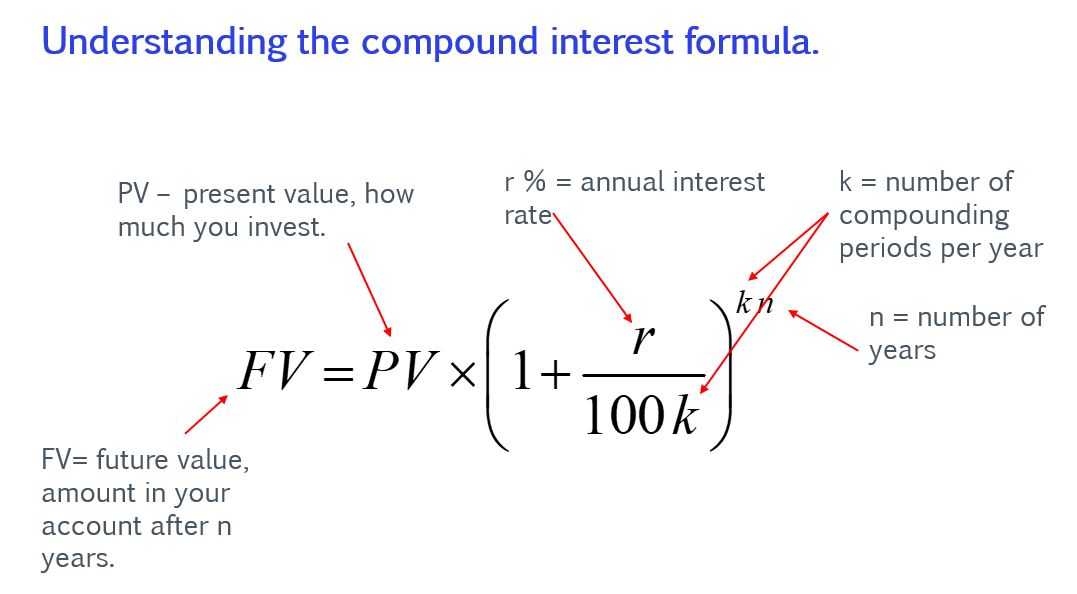
When you first see the compound interest formula, it looks deceptively simple. Multiply your principal by one plus the rate divided by the number of compounding periods, all raised to the power of the periods times the years. It works. Most people use it wrong though, and the mistake usually costs them real money. I ran into a specific problem about two years ago that still makes me sigh. A client came to me with a calculation for a bond that paid semi-annual coupons but they wanted the effective yield compounded quarterly. They had plugged the semi-annual rate directly into a quarterly compounding formula. The result was off by about forty basis points on a $2 million position. That is roughly $8,000 depending on how you round. The fix was straightforward: convert the stated rate to an equivalent effective annual rate first, then redistribute it across the target compounding frequency. I wrote a small spreadsheet macro that does this conversion automatically so I never have to think about it again. Saved me probably fifteen minutes per calculation going forward, which sounds small until you are doing thirty of these a week.
What compound interest actually means in practice
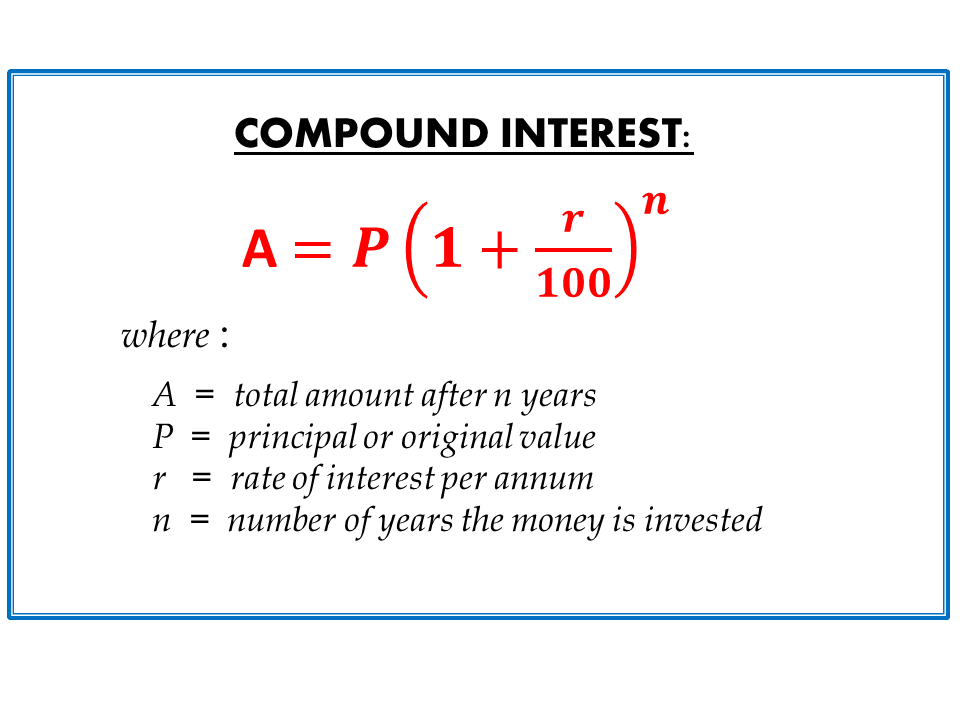
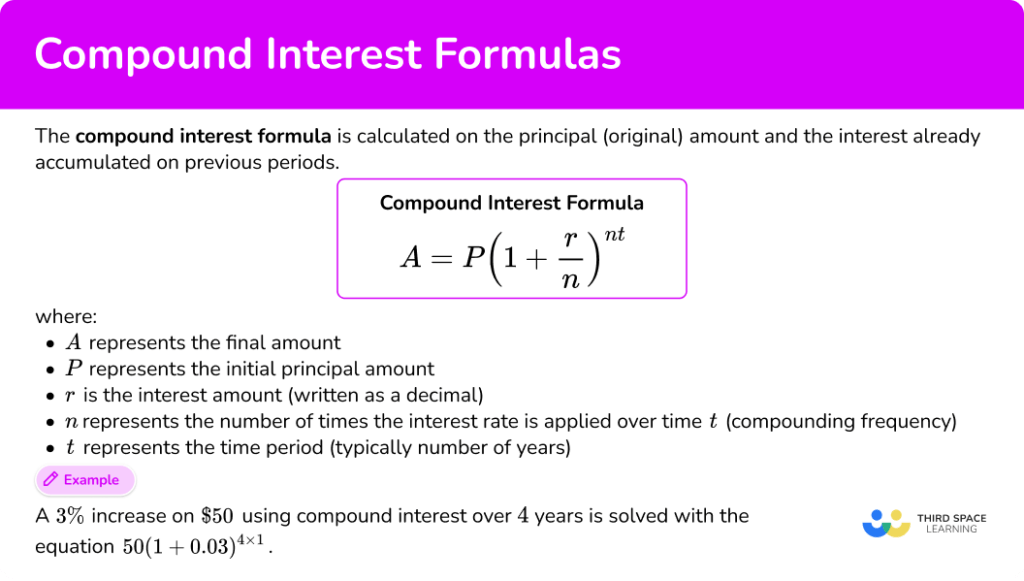
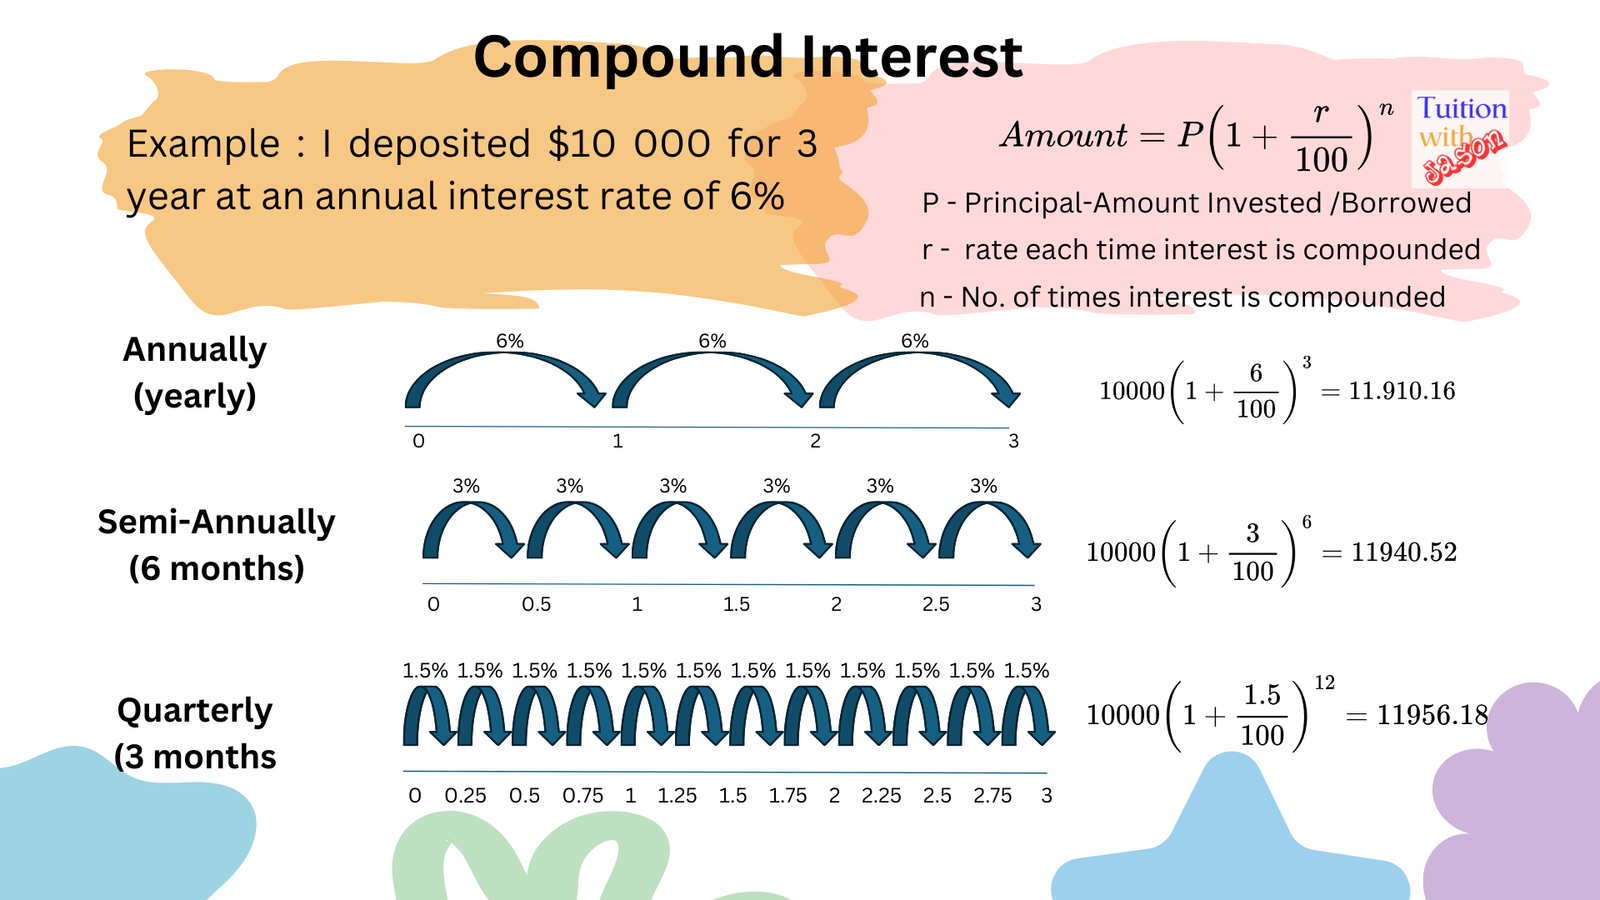
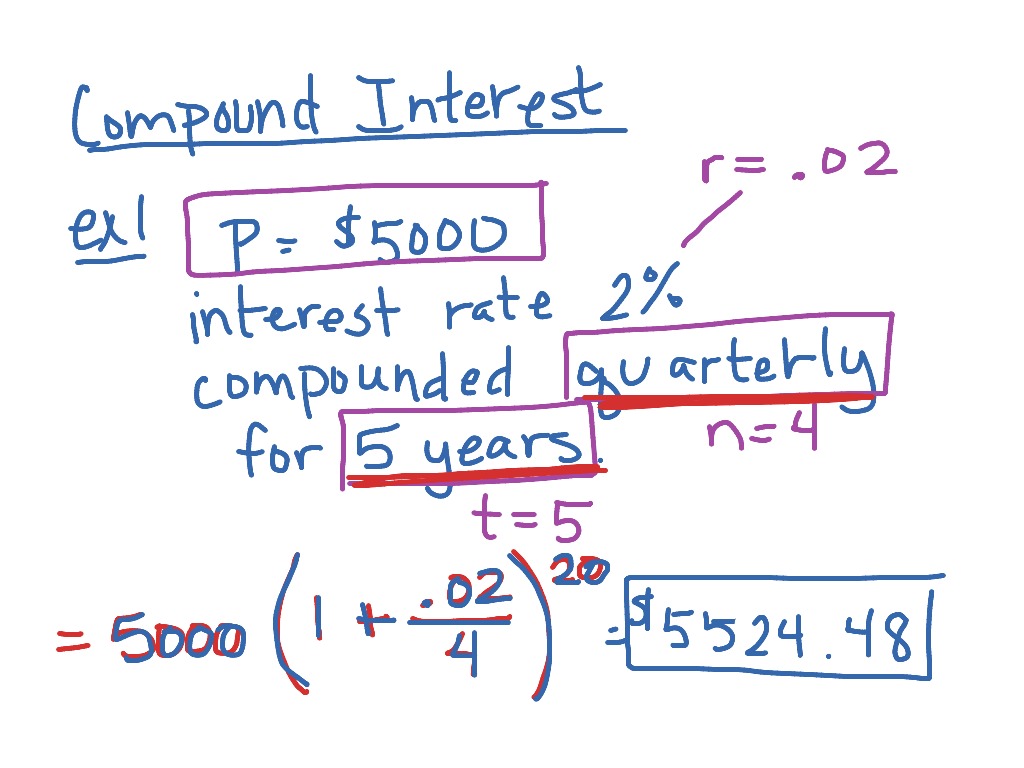
Compound interest is interest calculated on the accumulated balance, not just the original principal. That difference sounds trivial until you watch it play out over five or ten years. The key insight that separates people who understand this from people who just memorize a formula is recognizing that the compounding period matters more than the nominal rate. A 6 percent annual rate compounded daily is not the same as 6 percent compounded monthly. The daily version gives you an effective annual yield of about 6.18 percent. The monthly version sits at roughly 6.17 percent. On its own that difference is nothing. On a $500,000 investment over twenty years it becomes approximately $3,200. Small numbers add up when the time horizon stretches. The formula you should have running in your head is A equals P times the quantity one plus r over n, all raised to the power of nt. P is the principal amount. r is the annual nominal interest rate expressed as a decimal. n is the number of compounding periods per year. t is the number of years. A is the total amount after t years including interest.
Let me walk through a real example. Say you deposit $10,000 into an account that pays 5 percent annual interest compounded monthly. The monthly rate is 0.05 divided by 12, which gives you 0.00416667. You raise one plus that rate to the power of 120, which is 12 times 10 years. The result is about 1.647009. Multiply by the principal and you end up with $16,470.09 after ten years. The interest portion is $6,470.09. If that same account had used annual compounding instead, you would have only $16,288.95. The difference is $181.14. Not dramatic in isolation, but the direction matters. This is Compound Interest In Math at its core. You take a principal, apply a rate, let the earnings feed back into the base, and repeat. The math is clean. The application is where people trip.
Get the Full Details
Where the standard formula breaks down
The standard compounding formula assumes a fixed principal, a fixed rate, and regular compounding intervals. None of those assumptions hold in the real world for very long. Here are the three failure modes I see most often. First, irregular cash flows. Deposits and withdrawals that do not line up with compounding periods will throw off any straight formula application. I deal with this constantly when modeling retirement accounts where the contributor changes their payment amount every year or skips months entirely. The workaround is to track the balance period by period rather than trying to force everything into one equation. You compound for the period at the given rate, then adjust the principal for any deposits or withdrawals, then compound again. It takes longer to set up but it is accurate. Spreadsheet modeling handles this fine. Mental math does not. Second, rates that change. The formula requires a single constant rate. Financial products rarely work that way. Variable rate loans, inflation-linked bonds, and floating rate notes all have rates that adjust. You have to recalculate at each adjustment date. I keep a running table with columns for the rate, the compounding frequency, and the period end balance. When the rate resets I update the rate column and continue compounding from the new balance. The process is mechanical once you have the table structure in place. It usually takes me about ten minutes to set up a fresh projection for a new product, and then each rate change is a two-minute update.
Read more
Third, the edge case of negative interest rates. Several European central banks have operated at negative policy rates. When that trickles down to retail accounts, the compounding formula still works mathematically, but the psychological and practical effects are different. A balance of $100,000 at a negative 0.5 percent rate compounded annually shrinks to $99,500.50 after one year. After ten years it is roughly $95,132. The formula does not care that this feels wrong. It just computes. The limitation here is that most consumer products do not compound negative rates in the same way they compound positive ones. Banks often floor negative rates or apply them differently to different tranches of your balance. Always check the product terms before trusting the raw formula output. People often treat continuous compounding as an unlimited growth mechanism. It is not. The formula A equals P times e to the power of rt has a clear ceiling for any given rate and time combination. The constant e is approximately 2.71828. If you compound continuously at 8 percent for thirty years, your money grows by a factor of about 10.93. Compounded daily at the same rate, the factor is about 10.92. The difference is one cent per dollar. The extra compounding frequency past daily gives you diminishing returns that become almost invisible at normal financial rates. The more useful application of continuous compounding is in theoretical finance and derivatives pricing, not in your savings account. Banks and brokers use it because the math is cleaner for certain calculations involving options and bonds with continuous cash flows. For everyday investing, monthly or quarterly compounding is the relevant benchmark. Daily compounding is the practical upper limit unless you are doing quantitative work.
Common mistakes that cost money
The most expensive mistake I see is mixing time units. Using a monthly rate with a yearly time period, or vice versa. If your rate is 6 percent per year and your compounding is monthly, your periodic rate is 0.5 percent. Your time period in the exponent must be in months, so ten years becomes 120. If you plug in 10 for the exponent with a monthly rate, you understate the result significantly. On a $100,000 investment at 6 percent over ten years, the correct monthly compounding gives you about $181,940. Using the wrong time unit gives you roughly $182,194 depending on how you mess it up. The direction of the error matters less than the fact that it exists and is easy to make. Another mistake is treating the nominal rate as if it were the effective yield. A certificate of deposit advertising 4 percent compounded quarterly does not pay you 4 percent. It pays you an effective annual rate of about 4.06 percent. The difference is small at low rates and low balances. At higher rates it compounds the error. A 9 percent CD compounded monthly gives you an effective rate of 9.38 percent. That is almost a full percentage point of unaccounted return if you ignore it. Rule of 72 estimation is another area where people get sloppy. Dividing 72 by the interest rate gives you a rough doubling time. At 8 percent that is nine years. The actual doubling time at 8 percent compounded annually is about 9.006 years. The rule is close enough for quick mental math. At 20 percent it gives you 3.6 years when the true answer is 3.8 years. The approximation error grows at higher rates. Use it for estimates. Do not use it for contract negotiations.
When compound interest models fail completely
The model assumes reinvestment at the same rate forever. That is almost never true. If you are planning for retirement with a projected 7 percent return and the market delivers 4 percent for a decade, your actual balance will be materially lower than the projection. The compound interest formula does not account for rate volatility. It gives you a single path. Reality gives you many paths. The model also breaks down with very large time horizons and very small rates due to floating point precision in digital calculators. This is not a real problem for humans but it is a real problem if you are coding a financial calculator app. I learned this the hard way when my first version of a compound interest tool gave slightly wrong results for balances over $10 million at rates below 0.1 percent over 50 years. The fix was switching to arbitrary precision arithmetic for the exponentiation step. Most users will never encounter this. Financial app developers will.
Practical tooling
You do not need special software for basic compound interest calculations. A spreadsheet with the right setup handles most real world cases. I use a simple structure with columns for the period number, the opening balance, the interest earned that period, the deposits and withdrawals, and the closing balance. Each row references the previous row. You can drag it down for decades of projections. The formula per row is opening balance times the periodic rate plus net deposits minus net withdrawals. For anything involving changing rates or irregular contributions, a short Python script saves hours. Here is the kind of thing I run:
def compound_interest(principal, annual_rate, compounding_periods, years, contributions=None):
    balance = principal
    rate_per_period = annual_rate / compounding_periods
    total_periods = compounding_periods * years
    for period in range(1, total_periods + 1):
        balance *= (1 + rate_per_period)
        if contributions and period in contributions:
            balance += contributions[period]
    return balance
This handles scheduled extra contributions at any period you define. It is not elegant. It is functional. I have used versions of this for eight years and it has never failed me on a calculation I needed to trust. The deeper you go into compound interest, the more you realize it is less a formula and more a framework for thinking about time value. The math is straightforward. The assumptions underneath it are where the work actually happens.