Working Through Compound Interest Problems
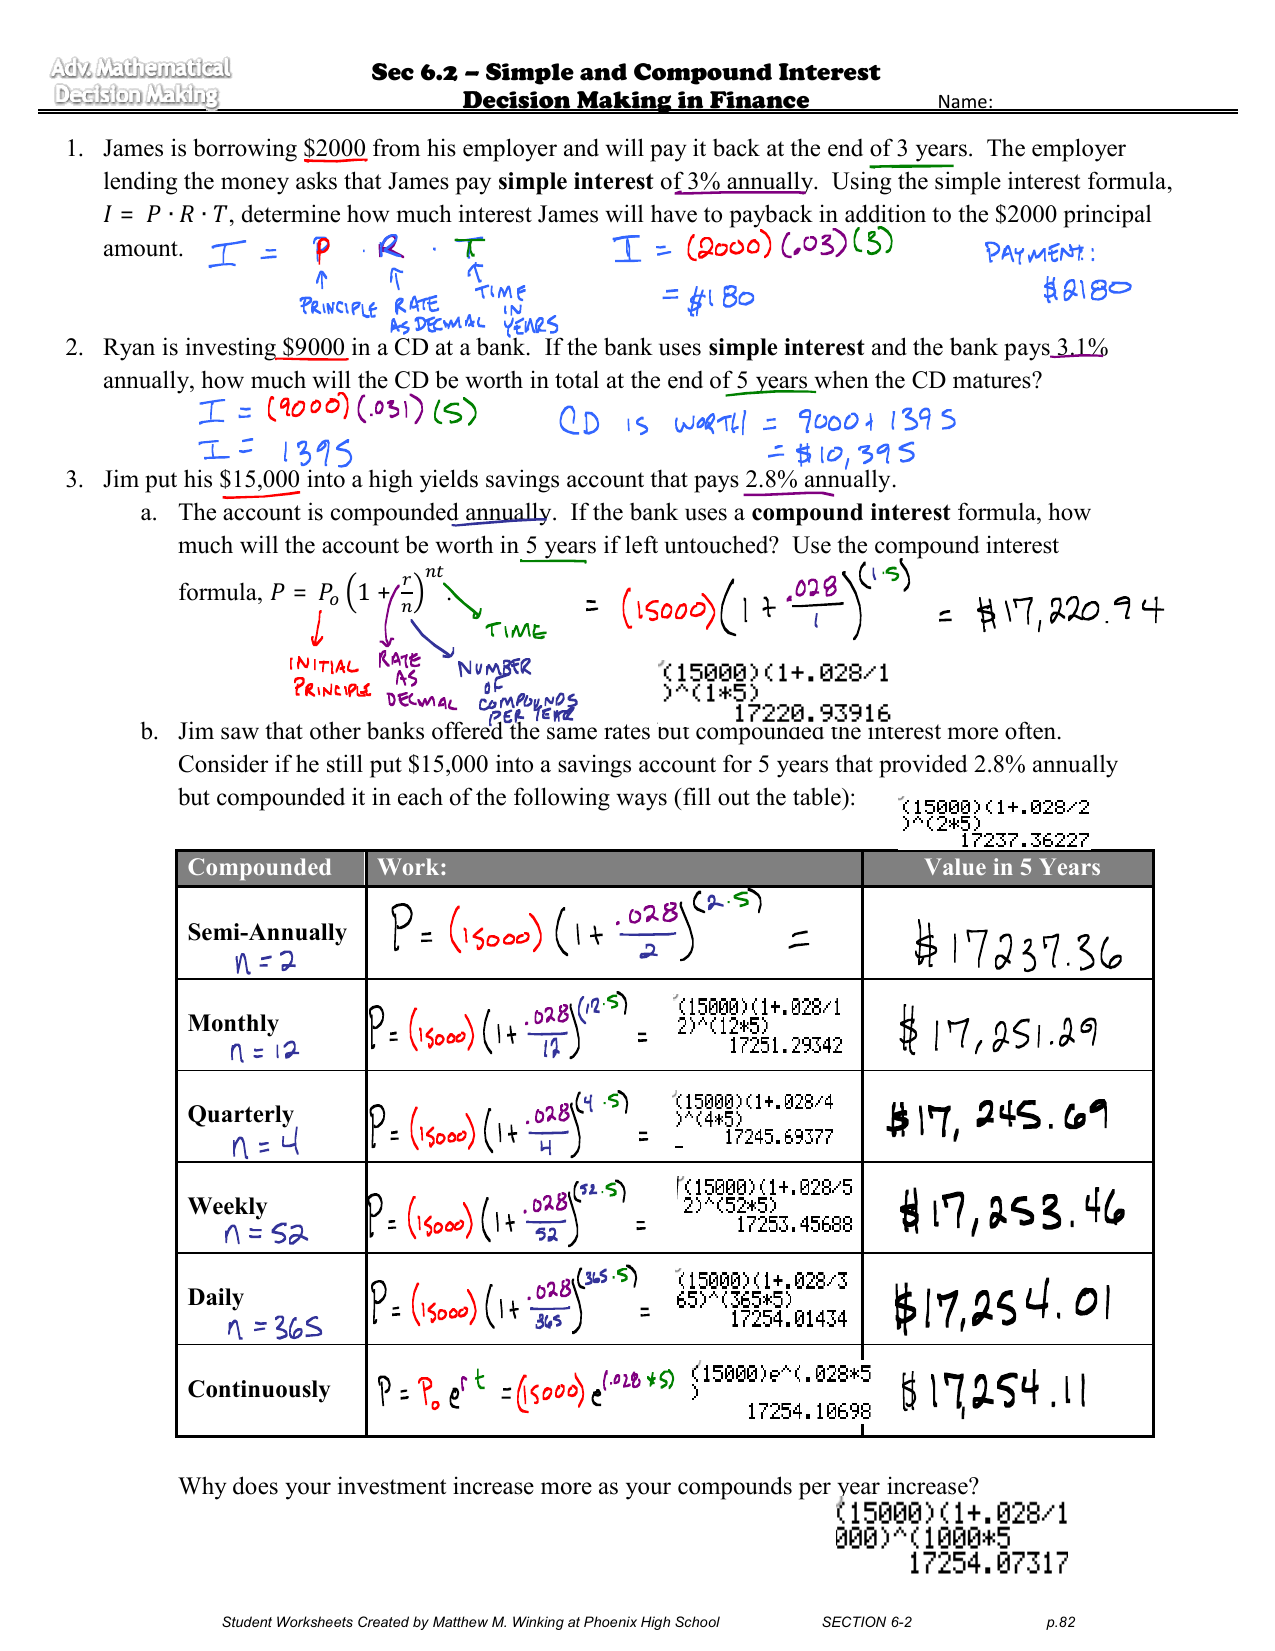
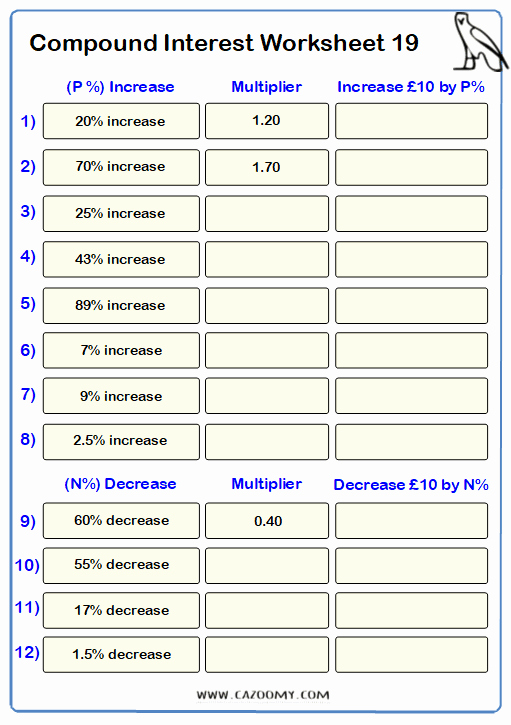
Compound interest worksheets are a standard part of any high school or intro college math curriculum. Students get a set of problems asking them to calculate future value, principal, rate, or time using the compound interest formula. The answers follow directly from plugging numbers into A = P(1 + r/n)^(nt), but the worksheet itself is where most people trip up. Not because the math is hard, but because the setup is messy and the rounding varies between answer keys. Most teachers post answer keys at the end of the workbook or on a separate sheet labeled "Key." If you're working from an online resource, some sites like Khan Academy, Purplemath, or IXL include worked solutions alongside practice sets. For textbook-based worksheets, the back of the book usually has abbreviated answers, but they often skip intermediate steps. That means your answer might match the final number but look nothing like what the key shows as the path there. It's useful to know that before you spend twenty minutes wondering if you made a mistake. I spent a lot of time grading these worksheets early in my teaching career, and the most common issue wasn't the formula itself. It was students misreading the compounding frequency. The problem would say "compounded quarterly" and someone would divide the annual rate by 12 instead of 4. The answer looked close but was wrong. I started requiring that they write down what n equals before doing any calculation. It cut the error rate significantly and gave me an easier way to give partial credit when the arithmetic was right but the setup was wrong.
The Formula and What Each Piece Actually Means
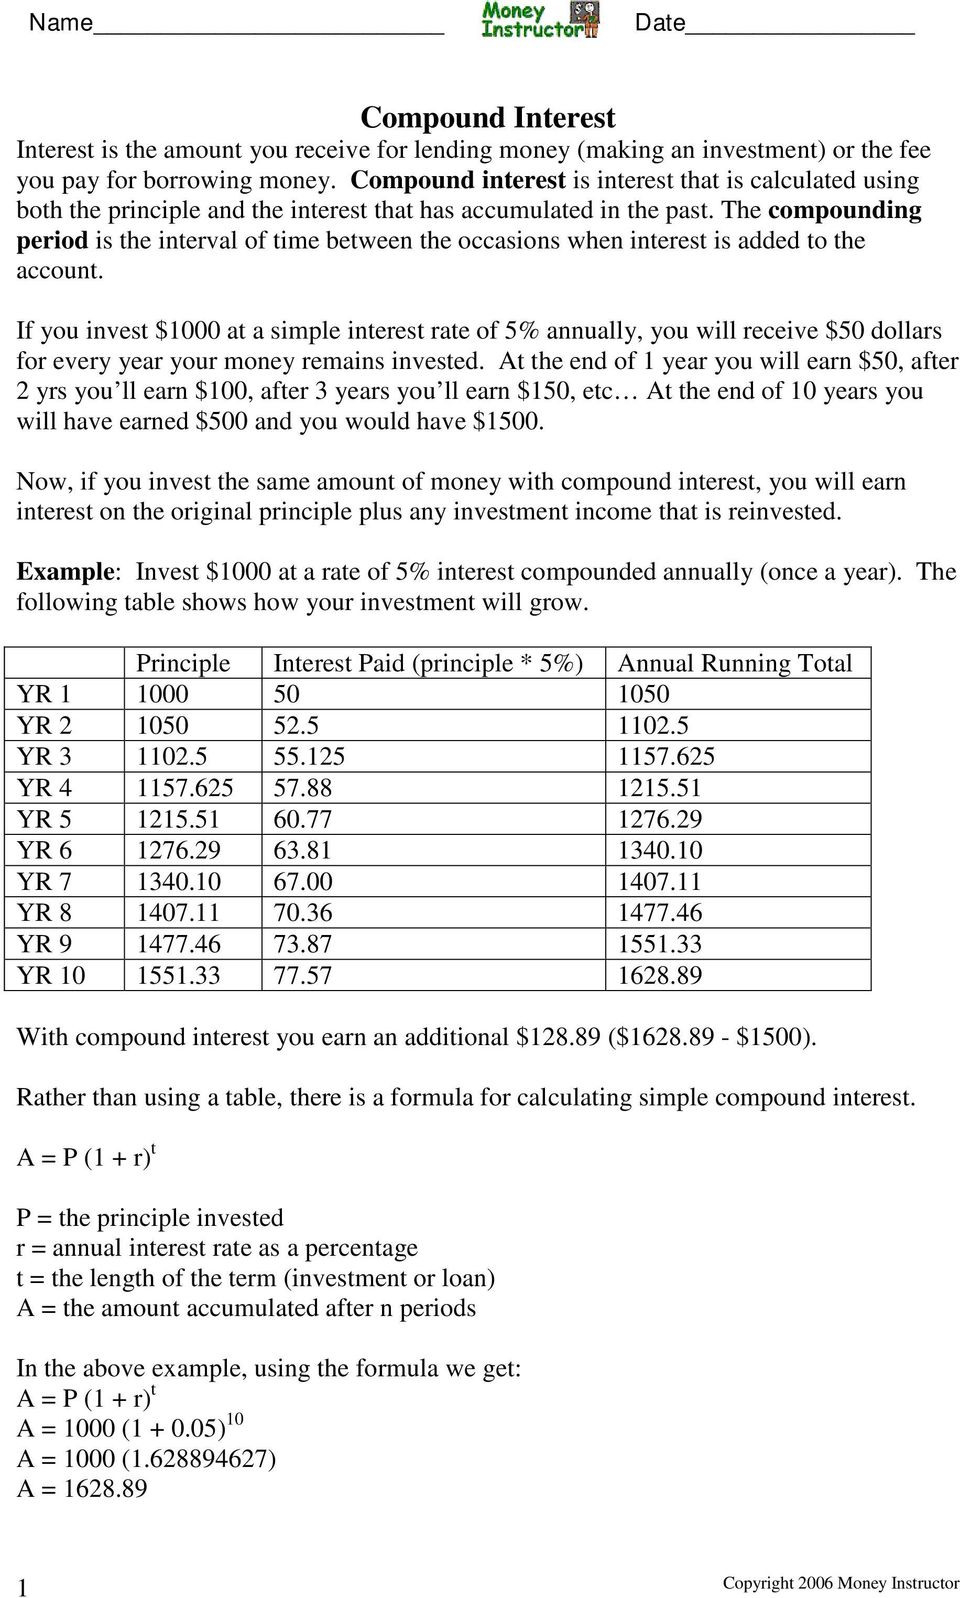
The compound interest formula is A = P(1 + r/n)^(nt). A is the future value. P is the principal, or starting amount. r is the annual interest rate written as a decimal, not a percentage. n is the number of times interest compounds per year. t is the time in years. You have to convert the percentage to a decimal first. That step gets skipped so often it's almost a rite of passage for students to forget it and end up with an answer ten times too large. Here is a typical problem. You deposit $5,000 into an account earning 4.5% annual interest compounded monthly for 3 years. You need to find the final amount. First, convert 4.5% to 0.045. Monthly compounding means n = 12. Time is 3 years. Plug those in: A = 5000(1 + 0.045/12)^(12*3). That becomes A = 5000(1.00375)^36. Calculating the exponent gives approximately 1.144247. Multiply by 5000 and you get about $5,721.24. Round to the nearest cent since this is money. The reverse problems are where it gets trickier. Solving for P, r, or t requires rearranging the formula and sometimes using logarithms. When you're solving for t, you end up with something like 2 = (1 + r/n)^(nt), and taking the natural log of both sides is the standard move. Students who haven't seen logs yet struggle here. They might try to guess and check, which works for simple cases but falls apart quickly. Knowing when a problem requires logs versus when algebraic manipulation is enough is a skill that separates people who just memorize from people who understand the structure.
Common Mistakes and How to Avoid Them
Rounding too early is the biggest enemy in these problems. If you round the interest rate division or the growth factor before finishing the calculation, your final answer drifts. I've seen answer keys that differ by a few cents purely because the author rounded at different points. The fix is to keep as many decimal places as your calculator allows through every step and round only at the very end. Another frequent issue is mixing up continuous compounding with regular compounding. The formula A = Pe^(rt) looks related but is fundamentally different. Worksheets sometimes include one problem with continuous compounding mixed into a set of regular ones, and students apply the wrong formula without noticing. Continuous compounding shows up in finance courses more than high school classes, but if your worksheet has it, you'll need to recognize e as approximately 2.71828 and use the exponential function on your calculator rather than a simple power. Time units also cause problems. A problem might state the period in months instead of years, or give you days and expect you to convert to a fraction of a year. One worksheet I worked with had a problem stating 180 days at 6% compounded quarterly. The expected answer treated the time as 180/365 0.4932 years, while another version of the same problem assumed a 360-day banker's year and got 0.5 years exactly. Both approaches show up in real financial calculations, and the difference matters depending on the context. Always check whether your class or textbook uses the 360-day convention or the actual 365-day year.
Get the Full Details

Practical Tips for Working Through These Worksheets
Write down what each variable represents before substituting. This takes ten seconds and prevents more confusion than anything else. When you're solving for an unknown, isolate the variable algebraically first, then plug in numbers. Substituting values into an un rearranged equation and trying to solve numerically works on a calculator but doesn't teach the structure and makes errors harder to catch. Use a spreadsheet for multi-step problems. I built a simple sheet that handles the compounding formula automatically and can back-solve for any variable. It usually cuts the process down from maybe 10 or 15 minutes per problem to under a minute once the template is set up. The spreadsheet approach also lets you test sensitivity easily. Changing the compounding frequency from monthly to daily or annually shows how much the final amount shifts, which is something most worksheet problems never ask but is genuinely useful in practice. When checking your work against answer keys, a difference of a few cents is normal due to rounding variations. A difference of more than a dollar means something is wrong with your setup, not your rounding. Double-check that you used the correct compounding frequency and that the rate is in decimal form. These two mistakes account for the vast majority of incorrect answers I see.
There is also a practical limit to how much compound interest worksheets can prepare you for real financial decisions. The formulas assume a fixed rate and consistent compounding periods, which barely exists outside of textbook problems. Real accounts have variable rates, fees, and irregular transactions. The worksheet answers you're looking at represent an idealized model, and that model is still useful for building intuition about exponential growth, but it shouldn't be treated as a complete guide to how money actually works in the real world. For that, you need to understand annual percentage yield, which adjusts the nominal rate for the effects of compounding and gives a more honest picture of what you're actually earning.