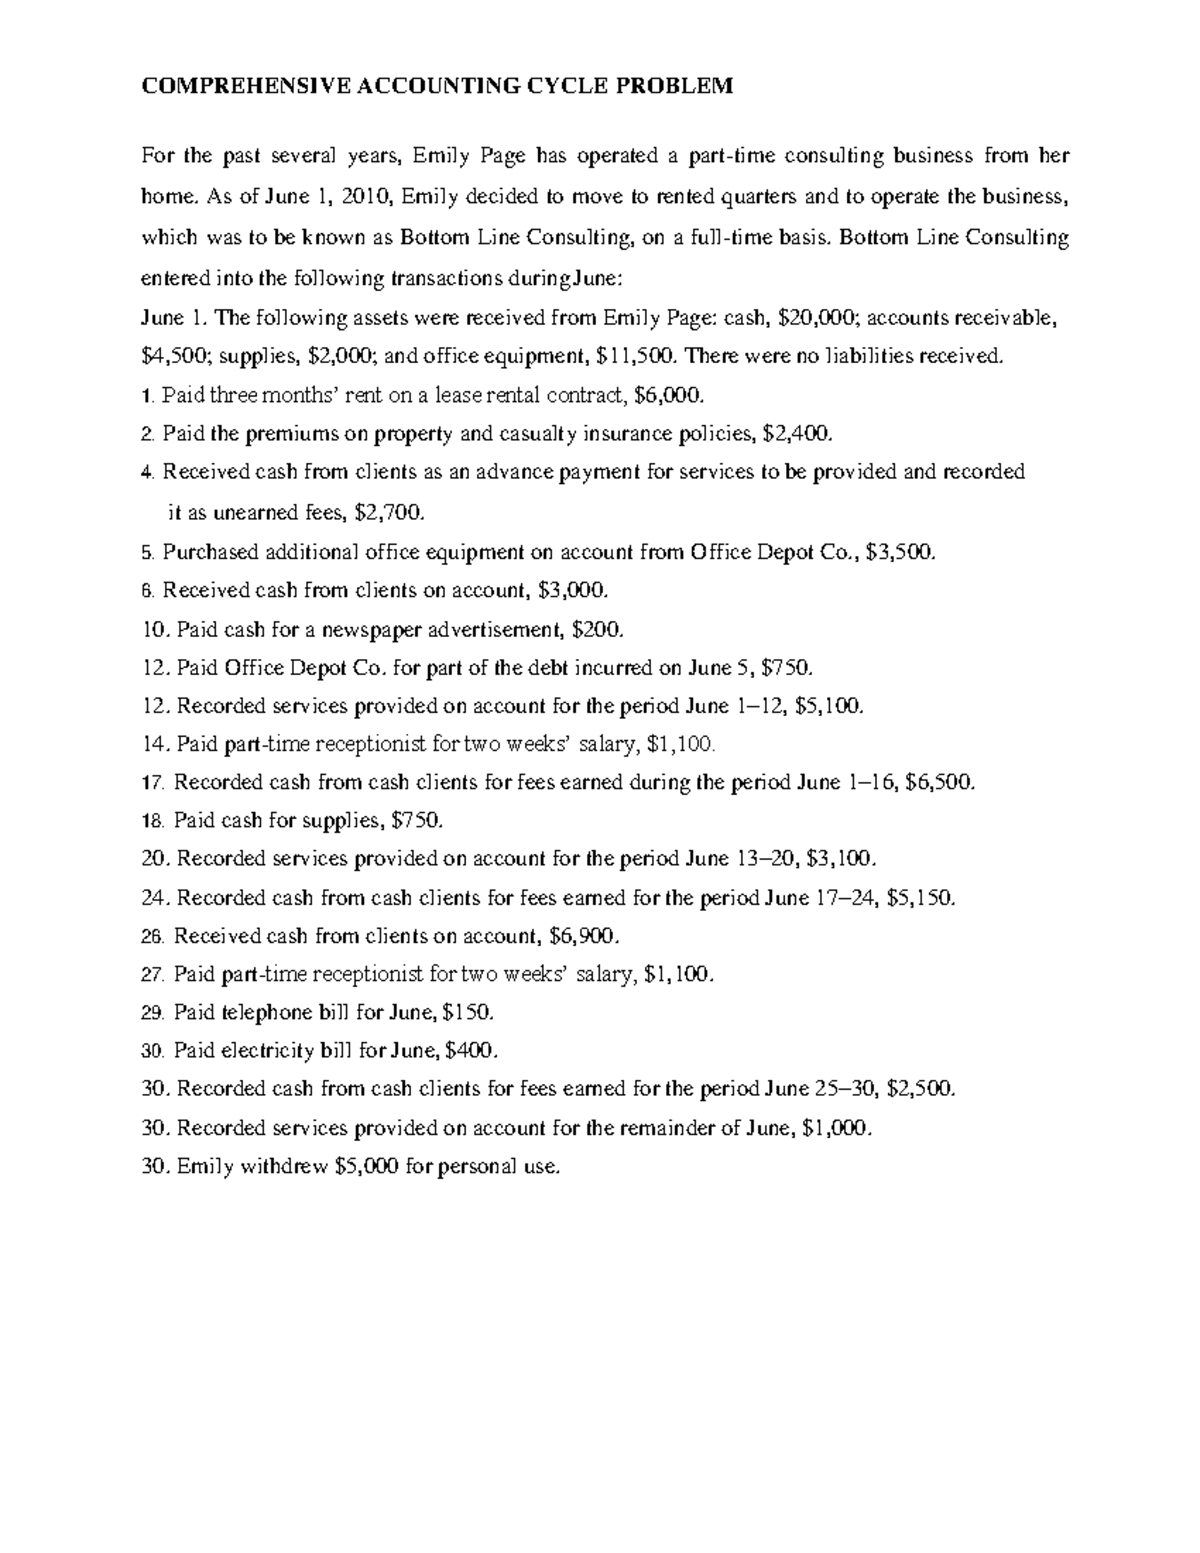
The Accounting Cycle in Practice
Most people think the accounting cycle is just a textbook concept. It's not. When you actually work with it, you learn quickly that it's a series of decisions about timing, classification, and verification. Get one step wrong and the whole month gets messy. I started managing entries for a mid-size manufacturing firm back in 2018. We had a recurring problem where depreciation schedules didn't align with the actual asset disposal dates. The cycle should catch this during reconciliation, but it doesn't always. I spent three weeks tracking down why our fixed asset register showed twelve machines that were already sold.
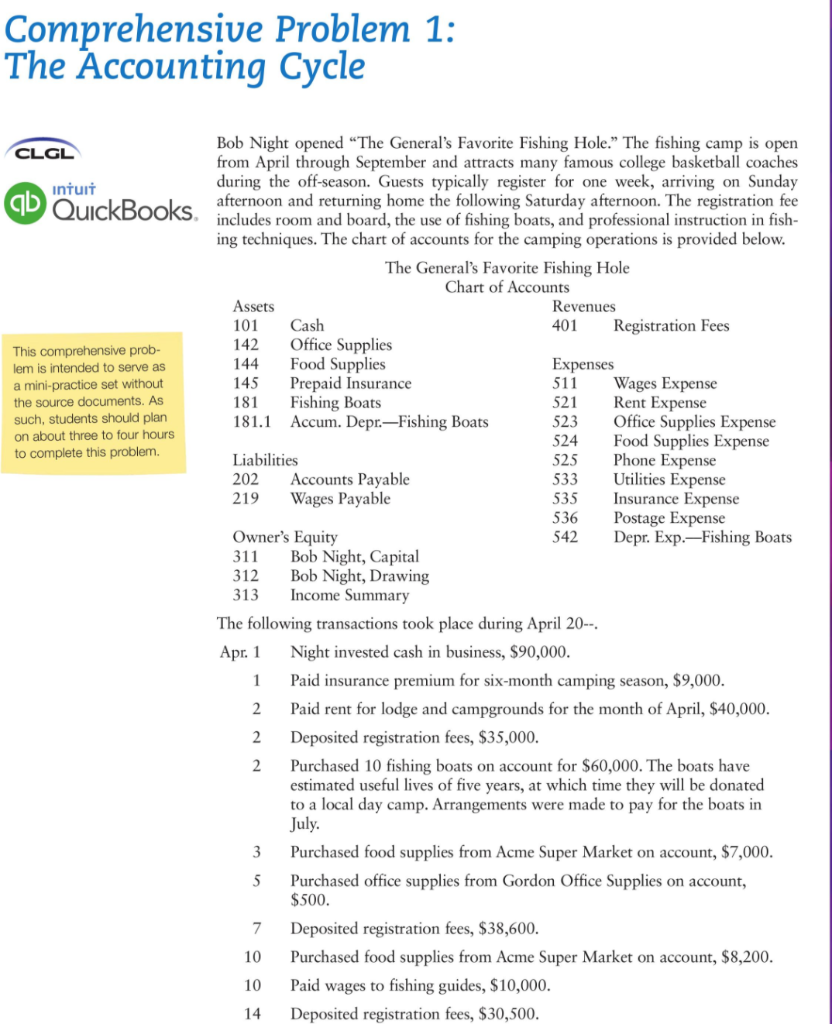
Comprehensive Problem 1 The Accounting Cycle
The cycle itself follows a standard sequence. You identify transactions. You record them in journals. You post to ledgers. You prepare an unadjusted trial balance. You make adjusting entries. You verify with an adjusted trial balance. Then you create financial statements and close the books. That sounds straightforward. In reality, each step has failure points. Here's what actually goes wrong. Step one: transaction identification. This is where most errors start. You need to catch every business event that affects the financial position. Revenue received in advance. Expenses paid before the period starts. Accrued wages not yet disbursed. Depreciation on equipment used throughout the month.
The common mistake is focusing only on cash movements. That misses accruals and deferrals. If you only record what hits the bank account, your financial statements will look clean but be wrong. Step two: journal entries. Double-entry bookkeeping isn't optional. Every transaction needs a debit and a credit of equal amount. If they don't balance, something is missing. I once saw a company where the AP clerk recorded vendor invoices but never posted the corresponding liability entries. The expenses looked correct on the income statement, but the balance sheet liability was zero. It took two months to find. Step three: posting to ledgers. This step transfers journal data into individual account records. Most small businesses use software that does this automatically. But automatic doesn't mean correct. Garbage in, garbage out still applies.
Get the Full Details

I worked with a client whose software was posting customer payments to the wrong accounts. The system was mapping payment references incorrectly. The cash account was fine. Every other receivable account was wrong. Reconciliation took four days because the error wasn't obvious until the third cycle. Step four: unadjusted trial balance. This verifies that debits equal credits. It catches mathematical errors. It does not catch classification errors. If you recorded a $5,000 expense as an asset, the trial balance will still balance. You need to verify the logic, not just the math. Step five: adjusting entries. This is where most beginners struggle. You need to match revenue to the period earned and expenses to the period consumed. Accruals. Deferrals. Estimates. These aren't optional adjustments. They're what make the financial statements useful.
Here's a practical example I deal with regularly. A client runs a software company. They collect annual subscriptions in January. The cash comes in all at once. But the revenue should be recognized monthly over twelve months. If you don't adjust, January looks incredibly profitable and February through December look terrible. The adjusting entry moves eleven-twelfths of the revenue to unearned revenue liability and recognizes one-twelfth each month. Another common adjustment involves bad debt expense. You don't know exactly which customers will default. But history shows a pattern. Most companies estimate this using percentage of sales or aging of receivables. Both methods have trade-offs. Percentage of sales is simpler but ignores the actual collectibility of current receivables. Aging is more accurate but requires detailed data entry. Step six: adjusted trial balance. This verifies everything after adjustments. If debits still equal credits here, you can proceed. If not, something went wrong during the adjustment process.
Step seven: financial statements. The income statement comes first. Then retained earnings. Then the balance sheet. Then cash flows. Each depends on the previous one. You can't prepare the balance sheet without the income statement because net income flows into retained earnings. I've seen people try to rush this step. They prepare the balance sheet before the income statement. The numbers never reconcile. Take your time here. The statements should tell a coherent story about the business. Step eight: closing entries. Temporary accounts need zero balances for the next period. Revenue, expense, and dividend accounts close to retained earnings. Permanent accounts carry forward. If you forget to close, your next period starts with this period's numbers still in the accounts.
This happens more often than you'd expect. One client ran the closing process manually and missed the dividends account. Retained earnings showed higher than it should have. It took the auditor three weeks to identify the error during the annual review.
Common Pitfalls and Workarounds
Pitfall one: incomplete transaction capture. This occurs when business events happen but aren't recorded. Examples include accrued expenses, prepaid items expiring, or revenue earned but not invoiced. The workaround is a regular review of supporting documents. Match bank statements to entries. Verify subledger balances against general ledger totals. Check that every balance sheet account has a reasonable explanation for its current value. Pitfall two: incorrect adjusting entries. This usually involves wrong amounts or wrong accounts. Common causes include misunderstandings of accrual accounting or errors in calculation. I once saw a company that recorded prepaid insurance as an expense immediately. The adjusting entry should have moved the unexpired portion to a prepaid asset. Instead, they left it in expense. Their profit was understated by $18,000 for that quarter. The workaround is to review each adjustment against the underlying transaction. Verify the calculation. Check the account classification. Make sure the adjustment serves the matching principle.
Pitfall three: failing to verify the trial balance before proceeding. Some people move quickly to financial statements. If the trial balance is wrong, everything downstream is wrong. Always verify debits equal credits before preparing statements. Always review unusual account balances before finalizing. Pitfall four: ignoring reconciling items. Bank reconciliations often reveal differences between the books and the bank statement. These need investigation. Outstanding checks. Deposits in transit. Bank fees not yet recorded. Interest earned not yet recorded. Each one represents a transaction that needs to be captured in the cycle. I deal with a client whose bank reconciliation showed a $2,500 difference every month. The error was a recurring bank fee that wasn't being recorded. The cycle should have caught this during reconciliation. Instead, they just wrote it off as an unavoidable difference. After I insisted on investigating, we found the fee and started recording it properly.
Advanced Nuances
The accounting cycle has layers that most introductory courses skip. Here are two I consider important. Layer one: materiality thresholds. Not every error matters. A $5 difference in a company with $5 million in revenue is immaterial. A $5,000 error in a company with $50,000 in revenue is significant. You need judgment about what to correct and what to ignore. The textbook answer is to correct everything. The practical answer is to focus on material misstatements. I worked with a nonprofit that spent two days correcting immaterial errors during their annual close. They could have finished in four hours if they'd applied materiality thresholds properly. The board was unhappy about the time spent but appreciated the clarity on priorities.
Layer two: system limitations. Automated accounting systems make the cycle faster but introduce new failure modes. Data imports can map accounts incorrectly. Recurring entries can accumulate errors. Integration between systems can lose transactions. You need to test these systems regularly. One client had an integration between their CRM and accounting system that dropped transactions under certain conditions. Sales over $10,000 sometimes failed to create invoices. The cycle should catch this during reconciliation. But the errors accumulated over three months before anyone noticed. Now we run daily exception reports instead of relying on monthly reconciliation alone. Layer three: period-end pressure. The cycle creates natural deadlines. Month-end. Quarter-end. Year-end. Pressure to close quickly leads to shortcuts. Missing accruals. Incorrect estimates. Unreconciled accounts. The shortcuts seem harmless at the time but cause problems later.
I recommend building time into your schedule for proper cycle completion. Close within five business days of period end. Review all reconciling items before signing off. Don't accept incomplete documentation just to meet a deadline.

When the Cycle Fails Completely
The accounting cycle assumes certain conditions. It assumes transactions can be identified and measured. It assumes records are maintained accurately. It assumes the business is a going concern. When these assumptions fail, the cycle produces unreliable results. Examples include businesses with poor record-keeping, companies facing liquidation, or organizations with fraudulent activity. In these cases, the cycle alone won't produce useful financial statements. You need additional investigation, possibly forensic accounting, and often external verification. One client operated a small retail business with minimal record-keeping. The owner kept receipts in shoeboxes and guessed at inventory values. The cycle produced numbers, but they were meaningless. We ended up reconstructing a year of transactions from bank statements, credit card records, and supplier invoices. It took six weeks and cost more than the accounting fees for three years combined.
The lesson is that the cycle is only as good as the data you feed it. Garbage in, garbage out applies at every step. Invest in proper transaction capture from the start.
Practical Recommendations
Build checklist procedures for each cycle step. Use them consistently. Review completed cycles periodically for errors. Keep documentation accessible for audit purposes. Train staff on the full cycle, not just their individual steps. Understanding the whole process helps everyone do their part better. The cycle is a tool. It requires skill to use correctly. It requires judgment to interpret results. It requires discipline to complete thoroughly. Treat it as a core business process, not an administrative burden. The quality of your financial statements determines the quality of your decisions. I've seen companies make significant strategic errors because they didn't understand their financial position. The cycle provides the information needed for sound decisions. Use it properly.