Getting Historical Data for COP Without Losing Your Mind
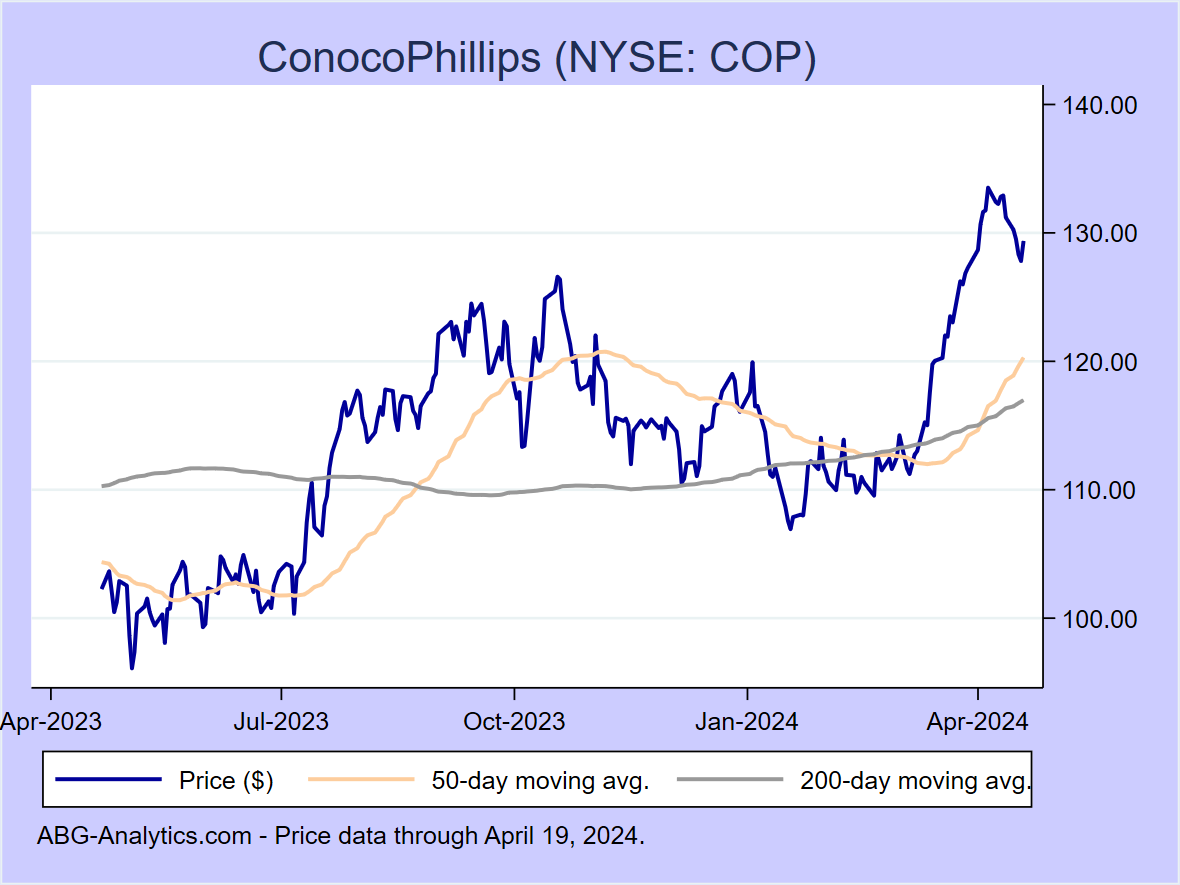
Fetching Conocophillips Stock Price History sounds straightforward until you actually try to do it cleanly. You open a browser, go to Yahoo Finance or similar, and hit download. The CSV that lands on your desktop looks fine at first glance, then you notice the timestamp on the closing prices is UTC midnight instead of New York close, the adjusted close column is missing, or the data quietly drops trading days without warning. This happens more often than it should. The most accessible source is Yahoo Finance. Type "COP" into the quote search, click Historical Data, set your date range to something useful like 2000-01-01 through today, and hit Download. You get a CSV with Date, Open, High, Low, Close, Adj Close, and Volume. That's your starting point. Free, no API key, immediate. The second option is Alpha Vantage. Free tier gives you 25 requests per day with daily granularity, which covers most retail needs. You register, grab an API key, and use the TIME_SERIES_DAILY endpoint with symbol=COP and outputsize=full. The response is JSON, which is harder to work with in a spreadsheet but much more structured if you're processing anything programmatically. They also offer an ADJUSTED_TIME_SERIES_DAILY endpoint that returns adjusted closes baked in, saving you a column manipulation step.
For anyone who needs to go further back or wants intraday precision, Polygon.io and IEX Cloud are the next tiers. Polygon's free plan is basically useless for history — you hit the limit fast. Their paid plans start around $49 monthly and give you reliable OHLCV back to IPO. IEX Cloud used to be the go-to mid-tier option until they restructured their pricing model in 2022 and made historical data significantly more expensive. Polygon is the more honest choice at that level because their documentation actually matches what the API delivers.
What the Data Actually Looks Like
COP went public long before the modern electronic era, so you have complete daily data back to the late 1980s for most practical purposes. The tickers have shifted a bit — it was ConocoPhillips for a while after the 2002 split, then briefly COPX before reverting — so if you're pulling pre-2010 data through a raw terminal or database, verify the ticker matches the corporate action timeline. The merger with ExxonMobil was blocked by regulators in 2015, which matters if you're seeing anomalous volume spikes around June of that year. The adjusted close column is where most people trip up. It accounts for dividends and splits. If you're calculating returns over a 20-year period and you use unadjusted close prices, your numbers will be wrong. A single special dividend in 2008 reduced the adjusted close by roughly 8 percent in one day. Unadjusted close shows a gap down that never actually existed in real portfolio terms. Use adjusted close for any return calculation. Period. One thing most beginner guides don't mention: the volume column on Yahoo Finance is sometimes inconsistent for older records. Around 2005 to 2007, daily volume numbers for COP occasionally diverge from what Bloomberg and Refinitiv show. The price columns are reliable, but the volume is not. If your analysis depends on accurate historical volume, cross-reference with a paid provider or use the adjusted series from Alpha Vantage, which tends to be cleaner for pre-2010 data.
Get the Full Details

My Actual Workflow
I use Python for everything. The yfinance library handles the Yahoo download with a single call. Here's what a typical pull looks like in practice: import yfinance as yf
cop = yf.download("COP", start="2000-01-01", end="2026-07-01", progress=False)
cop.to_csv("cop_history.csv") That's it. The output includes a MultiIndex column structure that yfinance constructs automatically — the columns become (Adj Close, Close, High, Low, Open, Volume) with a DatetimeIndex for the date axis. Clean, but you need to flatten it before putting it into Excel or a database. I do that with cop.reset_index() and then explicitly cast the Date column to datetime to avoid timezone parsing issues later.
For anything that requires reliability beyond a personal backtest, I pull the same data from Alpha Vantage and merge on date. The merge catches any row mismatches. If Yahoo has 6,200 trading days and Alpha Vantage has 6,198 for the same period, I know two dates are missing and I can decide whether to fill them from a secondary source or flag them.
Common Pitfalls
The biggest issue people run into is survivorship bias in the ticker itself. COP absorbed Phillips Petroleum in 2012. Before that, Phillips had its own independent price history. If you're comparing metrics across the merger boundary, the corporate fundamentals shift discontinuously. Revenue, assets, reserve base — everything changed overnight. Adjusted close handles the stock price side, but it does nothing for fundamental time series. You need to note the merger date, which is May 30, 2012, and treat the pre- and post-merger periods as separate analytical windows unless you specifically want to study the combined entity from day one. Another issue is dividend reinvestment. The adjusted close column assumes a theoretical reinvestment, but the assumption is approximate. It compounds daily reinvestment at the ex-dividend price, which is close enough for most purposes but not exact. If you need precise total return numbers for institutional reporting, use the S&P Dow Jones Indices total return methodology or pull from a provider like Quandl that offers TR columns specifically.
Limitations Worth Stating Clearly
Free data sources have real constraints. Yahoo Finance occasionally drops data points during market stress events. During the March 2020 crash, there were several days where COP showed zero volume and stale prices because the data feed from the underlying exchange had a brief reporting lag. Alpha Vantage's free tier throttles at 25 requests per day, which means you can't batch-download multiple symbols or intraday intervals without paying. The JSON responses are also slow — expect 2 to 4 seconds per request on the free tier, which adds up if you're pulling monthly rebalanced portfolios with 500 stocks. If you need this data for production-grade work — backtesting a fund, regulatory filing, or anything where accuracy is auditable — the free options are insufficient. The jump to a paid service like Polygon ($49 monthly minimum for meaningful historical depth) or FactSet reduces the error rate to near zero and gives you consistent timezone handling, corrected corporate action adjustments, and guaranteed uptime. For personal analysis or learning, the free sources are adequate if you validate against a second provider on a sample basis. The file you end up with should always include at minimum: Date, Open, High, Low, Close, Adjusted Close, Volume. Anything less and you'll regret it when you need to back out splits or calculate returns properly. Save it as CSV with UTF-8 encoding, label the adjusted close column explicitly, and keep a copy of the raw download from the source alongside your cleaned version. Data drifts. Source files change. Having the original lets you trace exactly what went wrong when a column doesn't match what you expected.


