
How construction financing actually works in practice
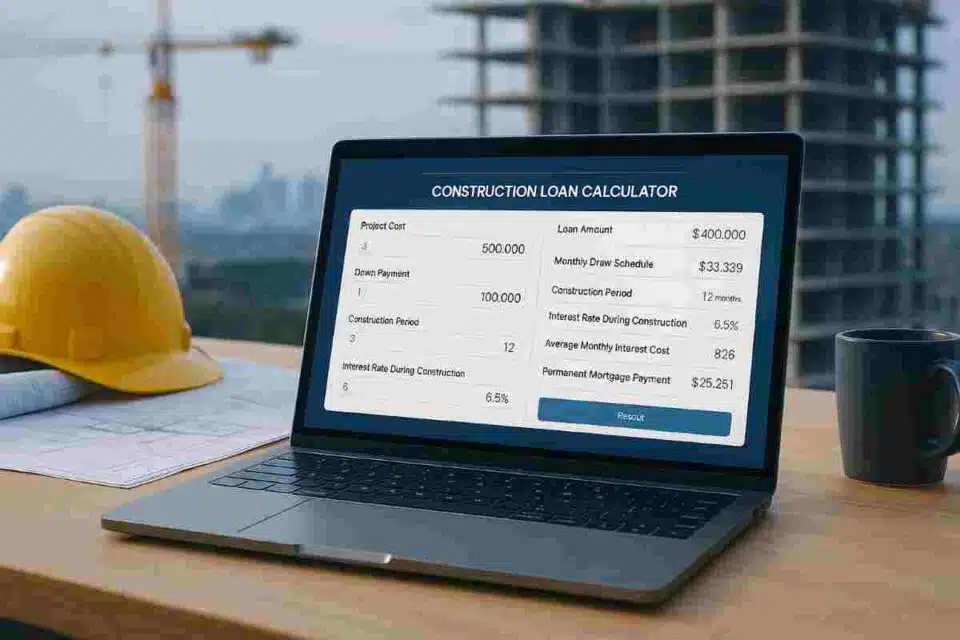
A Construction Financing Calculator is really just a spreadsheet that figures out how much money you need at each stage of a build. Banks use them. Developers use them. Most people who try to figure this out on their own end up with something that looks correct but breaks when the real numbers show up. I've watched it happen enough times to know the difference between a calculator that works on paper and one that works in a real deal. The core problem most people miss is that construction loans aren't paid out as a lump sum. They're drawn down in milestones, and interest accrues on whatever portion has been disbursed. Get this wrong and your cost projection looks fine until month four when you realize you've run out of money halfway through framing. Happened to a contractor I worked with back in 2019. He had a spreadsheet that calculated total project cost correctly, but it assumed the full loan amount was outstanding from day one. His interest reserve was off by about 18 percent. That came out of his pocket because the bank wouldn't adjust the draw schedule after closing.
How to build a Construction Financing Calculator that doesn't lie to you
Start with the loan structure. Most construction loans are either interest-only during the build phase with the principal due at completion, or they're structured as variable rate draws tied to inspections. The calculator needs to handle both because mixing them up is how people get blindsided. Here's what the basic inputs should be: total project cost, down payment or equity contribution, loan-to-cost ratio, interest rate, draw schedule, and the timing of each draw. That last one matters more than people think. A draw scheduled for week six that actually gets approved in week eight changes your interest calculation for two full months. The calculator should model that gap, not assume everything happens on schedule. For the math itself, you need a cumulative disbursement column. Each row represents a draw date. You calculate how much has been paid out up to that point, then apply the daily interest formula: outstanding balance times rate times days since last draw divided by 360. Banks use the 360-day year, not 365. Using 365 will make your numbers slightly too high, which sounds good for the borrower but gives the lender inaccurate data and can create compliance issues on the back end.
Then add an interest reserve line. This is the amount set aside to cover interest payments during construction. It's usually calculated as the average outstanding balance times the annual rate times the projected construction period in years. But here's the thing nobody warns you about: if your draw schedule is lumpy, using an average balance understates the actual interest because you're carrying more principal earlier than a flat distribution would suggest. I solved this by having the calculator run two scenarios side by side. One uses the average method for a quick estimate. The other does the day-by-day compounding. The difference is small on a 12-month project under two million dollars, but on a 24-month project at four million, it can be forty thousand dollars or so. That's material.
Get the Full Details
What most online calculators get wrong
I've seen a lot of these floating around. The typical free version online takes total project cost and an interest rate and spits out a monthly payment. That's not useful for construction. It's a mortgage calculator wearing a construction costume. Construction financing doesn't have a single monthly payment. It has draws, and the interest portion changes every time another tranche gets released. Another common flaw is that these calculators don't account for the fact that draw requests get held up. Inspections fail. Change orders slow things down. The lender holds the money longer than expected. When I built my own version of the Construction Financing Calculator, I added a field for expected delay per draw in weeks. It doesn't predict the future, but it forces you to run a stress case where everything takes three weeks longer than planned. If the project doesn't work under that scenario, you're already overleveraged before you start. There's also the issue of rate locks. Most construction loans have floating rates during the build phase. The calculator should let you input a rate lock period and a subsequent adjustment. A rate locked at 7.5 percent for six months and then floating at prime plus 2.25 percent tells a very different story than a flat rate assumption. The market situation right now makes this especially relevant. Rates have been moving, and projects that looked viable at closing can become marginal once the rate adjusts mid-build.
When this tool falls apart
A Construction Financing Calculator is only as good as your inputs. If your cost estimates are optimistic, the output will be optimistic too. There's no formula that corrects for a contractor who quoted you thirty thousand for HVAC when the actual bid comes back at forty-eight thousand. The calculator can flag the gap if you build in contingency buffers, but it can't prevent you from using bad numbers in the first place. It also doesn't handle tax implications, insurance costs, or the impact of owner-funded changes. Those need separate spreadsheets or a project management tool. Some people try to fold everything into one massive sheet and end up with something that's impossible to audit. Keep the financing calculator focused on debt service and draw timing. Put the rest elsewhere. For fixed-price projects, a straightforward draw-based model works fine. For cost-plus contracts where the final number isn't known until the end, the calculator becomes speculative by design. You can model scenarios, but you're essentially guessing. In those cases, running multiple sensitivity analyses on the total cost variable gives you a range instead of a single number, which is more honest about what you actually know going in.
The download
Below is the file. It's an Excel workbook with two tabs. The first tab is the basic model with standard inputs and monthly draw summaries. The second tab runs the day-by-day interest compounding with the delay stress test built in. There are instructions on the third tab. If you've never built anything like this before, start with the basic tab and make sure the numbers match your bank's disbursement schedule before you touch the advanced tab. The advanced model assumes you understand how draws, reserves, and rate adjustments interact. If you don't, you'll get numbers that look precise but aren't grounded in how the loan actually gets funded.


