Understanding How Construction Mortgage Rates Actually Work
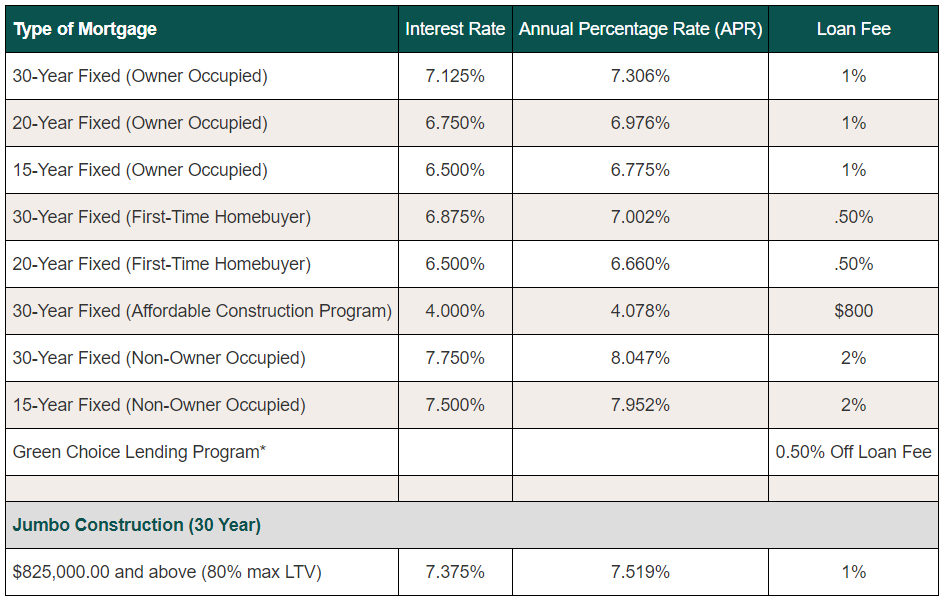
Most people think a construction loan rate is just a number you lock in and forget about. It's nowhere near that simple. The rate itself is typically 1 to 2 percentage points higher than a standard purchase mortgage rate, but the real complexity comes from how the loan is structured and drawn down over time. A construction loan is a short-term bridge product. You borrow money to build, then either pay it off or convert it to a permanent mortgage once the project is complete. Because the lender takes on more risk during the construction phase, they charge more for it. That's the basic mechanism. But the specifics matter a lot more than most borrowers realize.Navigating the Construction Mortgage Rate Landscape
The interest rate on a construction loan is usually variable during the construction period. It's tied to an index like the Prime Rate or COFI, plus a margin set by the lender. This means your rate can fluctuate between draws. I had a client in Colorado last year who locked at 7.25%, but by the time we were three months into construction, the Prime had jumped enough that her effective rate was creeping toward 8%. She hadn't anticipated that exposure, and it added roughly $1,200 to her total interest cost over the life of the loan. One thing nobody tells you about construction rates is that the draw schedule directly impacts your total interest cost. The lender only releases funds when a phase is inspected and approved. If you're waiting two weeks for an inspection, you're not paying interest on money you haven't received yet. But if the timeline drags because of permit delays, weather, or material shortages, you can end up needing multiple extensions on your rate lock. Each extension typically costs 0.125% to 0.25% in points, and some lenders won't even allow a second extension beyond the original lock period. Here's another counter-intuitive detail: the Construction Mortgage Rate you see advertised is rarely the rate you actually get. Lenders often quote the base index plus a flat margin, but they layer on origination fees, underwriting fees, appraisal fees, inspection fees, and sometimes mandatory points to buy your rate down. A lender quoting 6.75% with 2 points and $4,500 in fees might actually be cheaper than a lender quoting 7.125% with zero fees. You have to calculate the effective rate, not just look at the headline number.
I learned this the hard way back in 2019. I was helping a friend compare three lender offers for a custom home build in the suburbs. Offer A had the lowest rate by a full quarter point. Offer B had mid-range pricing but included a free rate lock extension. Offer C looked expensive on paper but had a very specific clause that waived the extension fee if the build exceeded six months due to supply chain issues. Two years later, those supply chain disruptions hit. Offer A's client ended up paying $1,800 for a lock extension. Offer C's client paid nothing extra. The best rate on paper became the most expensive loan in practice. Permanent conversion is another area where people get blindsided. Many construction loans are structured as "construction-to-permanent" loans, meaning they automatically convert to a standard mortgage after the Certificate of Occupancy is issued. The rate for the permanent phase is often locked in at the beginning of construction, which can be a genuine advantage if rates are rising. But the conversion rate usually has its own set of conditions. Some lenders require you to requalify at conversion, which means a full credit check, income verification, and appraisement at that point. If your credit score drops or your debt-to-income ratio changes because you financed the interior upgrades out of pocket, you could fail underwriting at the worst possible moment. The down payment requirement is another structural difference from standard mortgages. While a conventional purchase loan might go as low as 3%, construction loans typically require 20% to 25% down. This is because the collateral is incomplete until the building is finished. A partially built house is worth less than the land alone in a tight market. Lenders protect themselves by demanding more skin in the game. If you don't have the equity to put down, you'll need a co-signer or a portfolio lender willing to take the risk, and portfolio lenders will charge you even higher rates to compensate.
Practical Steps to Secure a Favorable Rate
Start by getting pre-approved before you even select a lot. Construction lenders need to evaluate both your financial qualifications and the feasibility of the build. They'll want to see detailed plans, a construction timeline, and a finalized budget from your builder. Without these documents ready, you're just another applicant with no substance behind the rate quote. Choose a builder who has an established relationship with your lender. This sounds minor, but it matters significantly. Lenders trust builders who have completed multiple projects with them. The builder's track record affects how quickly inspections get approved, how smoothly draws are processed, and sometimes even what margin the lender is willing to offer. A lender working with a builder they know and trust will move faster and with fewer surprises. I've seen the same loan take 45 days with an experienced builder and 90 days with a first-time builder, even when everything else was identical. Build a realistic contingency into your budget. The standard advice is 10% to 15% of total construction costs. Stick with at least 10%. If you come in under budget, great. If you hit unexpected soil conditions, material price increases, or change orders, that contingency is the difference between financing the overrun from your own pocket and triggering a costly and time-consuming loan modification. Modifications during construction can delay your completion timeline by several weeks and may force a rate adjustment.
Get the Full Details
Don't skip the conversation about rate lock duration. Standard locks run 6 to 12 months depending on the lender and the expected construction timeline. If your build is projected to take longer than your lock period, negotiate for a lock extension option upfront, before you close. Lock extension terms are easier to agree to when you're in the underwriting phase than when you're six months into construction and desperate to stay locked. This is the exact scenario where having that documented agreement from day one prevents costly surprises later.
Common Pitfalls That Sink Construction Loans
The biggest mistake I see is borrowers who focus exclusively on the interest rate and ignore the lender's track record with construction loans. Some lenders specialize in construction finance. Others treat it as a side product. A lender who rarely does construction loans will process your draws slowly, question inspection results, and create friction at every turn. That friction costs you time, and time costs you money in this context. You'll pay interest on each draw for the entire period between approval and disbursement. Delays add up. Another frequent problem is underestimating the total cost of borrowing. Beyond the rate and fees, you're looking at appraisal fees ($600 to $1,200), environmental assessments, engineering reports, title insurance, and sometimes even impact fees from the municipality. These are not optional costs. They're mandatory prerequisites for closing. Budget for them separately from your construction costs so they don't eat into your contingency fund. There's also the issue of interest reserves. Some lenders require you to set aside a portion of the loan proceeds to cover interest payments during construction. This reduces the amount of capital available for actual building. If your loan is $400,000 and 6% of it is reserved for interest, you only have $376,000 to spend on construction. That matters when you're working with tight margins on materials and labor. Ask the lender upfront whether an interest reserve is required and how much.
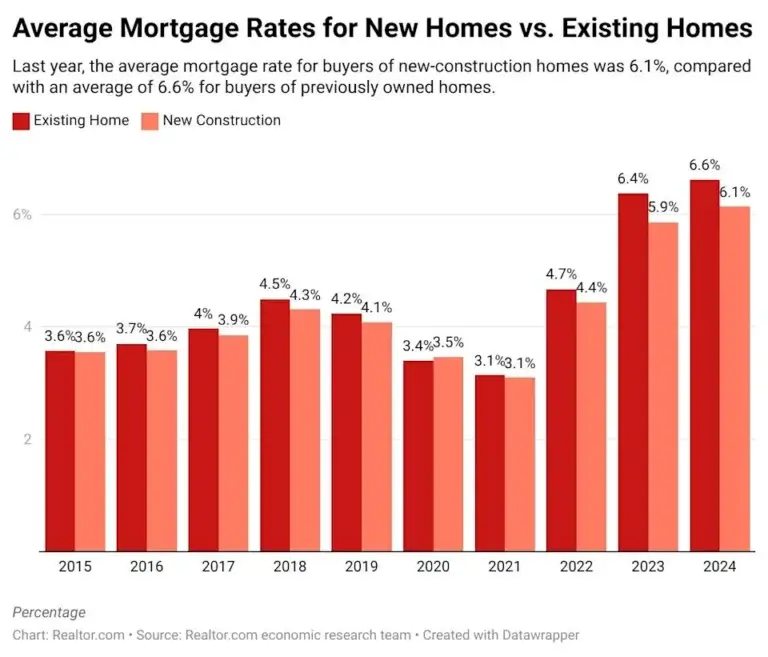
If your project runs long or your financial situation changes mid-construction, some lenders will require you to bring additional cash to the table. This is called a capital call, and it's a real risk. Lenders can revise their loan terms if the property value drops, if the builder falls behind schedule, or if your credit profile deteriorates. There's no universal rule protecting you from this. Read your contract carefully before you sign. For borrowers who can't meet the 20% to 25% down payment requirement, government-backed options exist. The FHA 203(k) loan allows you to finance both the purchase and renovation through a single mortgage with as little as 3.5% down. The Fannie Mae HomeStyle Renovation loan works similarly for conventional financing. These programs have stricter eligibility requirements and more documentation, but they bypass the high equity barrier entirely. The rates on these products tend to be competitive with standard purchase mortgages rather than the premium charged on pure construction loans, which makes them worth exploring if your situation fits. The bottom line is that the Construction Mortgage Rate is just one variable in a much larger equation. The terms, the lender's experience level, the builder relationship, the draw schedule, and the lock extension policy all interact with each other in ways that a simple rate comparison never captures. Take the time to understand the full structure before you commit. The people who do end up with loans that don't surprise them when things go sideways. And in construction, things always go sideways at some point.